


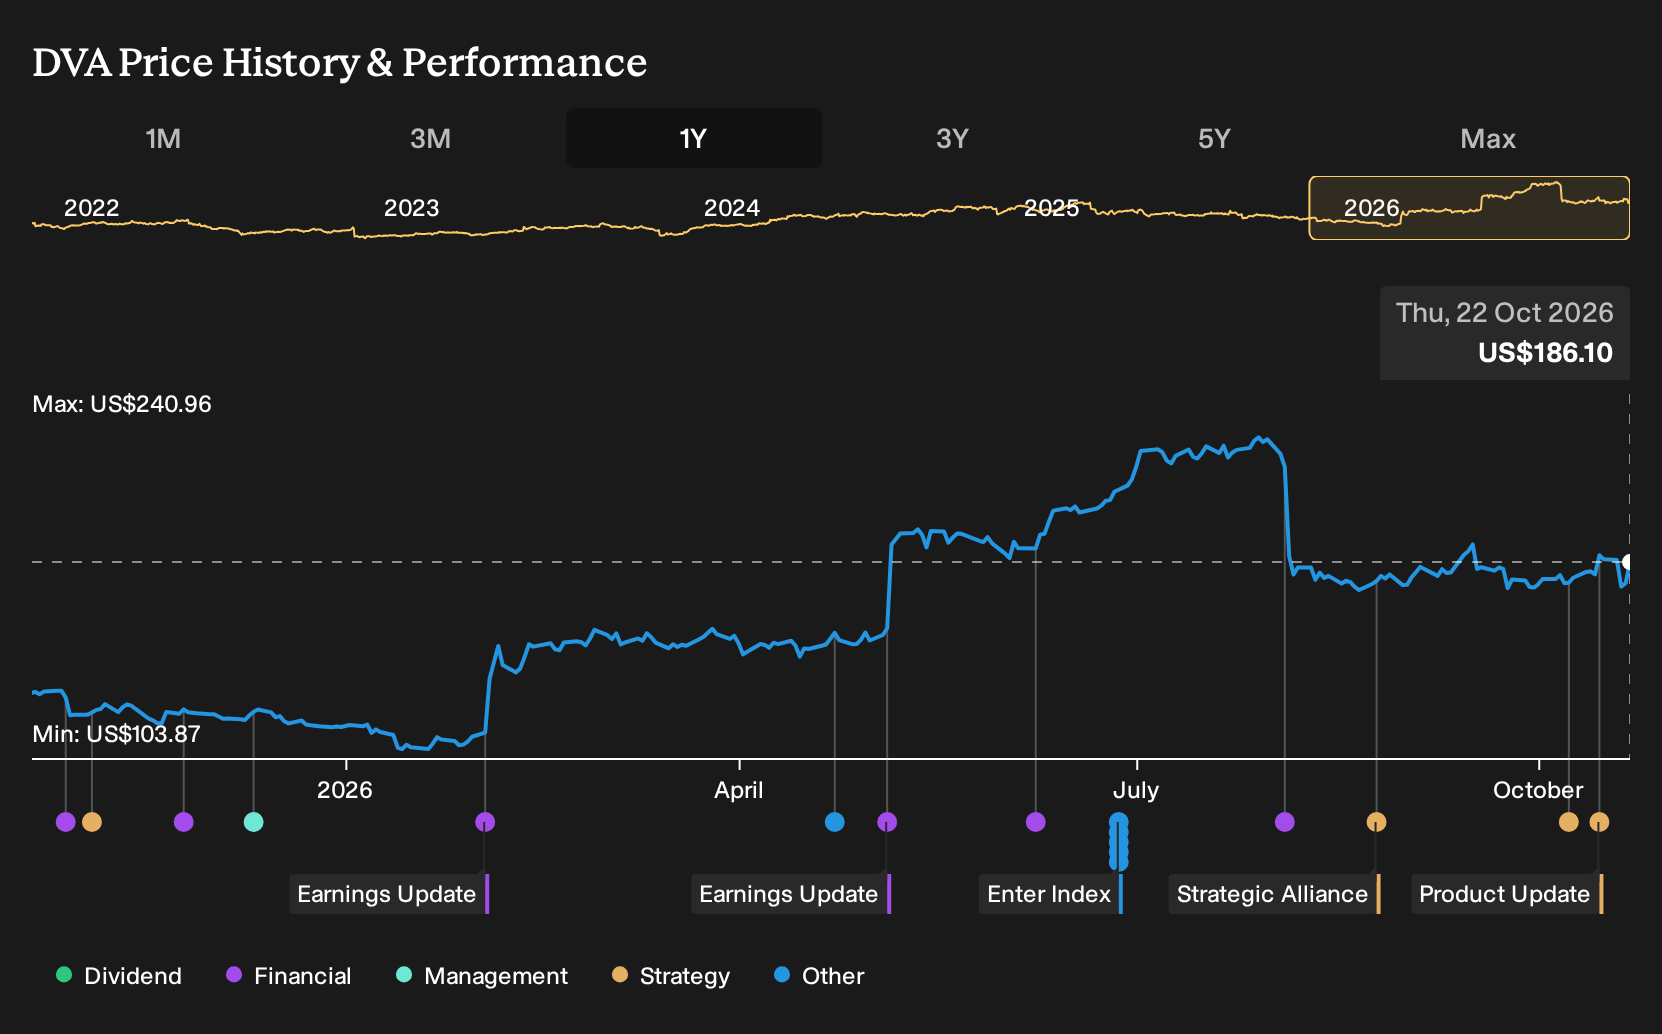
- DaVita reported quarterly results with revenue above expectations, but with mixed profitability metrics and revised full-year guidance that shifted the earnings outlook.
- The combination of stronger top-line performance and more cautious guidance highlighted the ongoing pressure from reimbursement, payer mix, and operating costs on DaVita's core dialysis business.
- The focus now turns to how DaVita's mixed earnings and updated guidance might reshape the broader investment narrative around its kidney care platform.
DaVita Investment Narrative Recap
For DaVita, the big picture is still about whether integrated kidney care, technology deployment and cost discipline can offset tight reimbursement and payer mix pressure in U.S. dialysis. The recent revenue beat but softer earnings guidance keeps that question open and leaves near term sentiment tied to how quickly management can steady margins and cost growth.
The key short term swing factor remains U.S. dialysis economics, particularly reimbursement updates and payer mix as ACA premium tax credits roll off. Rising G&A tied to tech and support functions adds another layer of risk. The recent guidance reset does not remove these pressures; it simply puts them in sharper focus.
The most relevant update here is DaVita’s plan to present seven studies at ASN Kidney Week 2026, with a heavy emphasis on expanded hemodialysis and middle molecule clearance. That research directly links to its planned broader deployment of expanded HD dialyzers, which management has framed as a way to pursue better outcomes without large new capital needs.
If the Kidney Week data reinforce prior findings around non inferior performance versus hemodiafiltration in real world settings, it could help DaVita build clinical support for expanded HD across its network. That kind of evidence matters for the firm’s biggest earnings catalysts, including treatment adherence, integrated kidney care performance and potential operating efficiency, even as reimbursement and cost inflation remain the main operational risks.
DaVita's current analyst story centers on revenues projected at US$16.1b and earnings of US$1.1b by 2029, based on 4.6% yearly revenue growth and an earnings increase of about US$277.5m from US$822.5m today.
Uncover why DaVita's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts DaVita’s clinical research and AI tools at the center of the story. The most cautious analysts were working off slower top line assumptions of roughly US$14.9b revenue by 2029 and a lower 9.7x P/E multiple, so they saw less upside. These Kidney Week results could prompt that narrative to evolve.
Explore 2 other DaVita fair value estimates, including one that suggests it could be worth just $219.86.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DaVita research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DaVita. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DaVita's overall financial health at a glance.
Looking For More Ideas Beyond DaVita?
If DaVita's kidney care story caught your attention but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other opportunities that fit different risk and return profiles.
- If capital preservation matters most, start with sturdier balance sheets and stronger fundamentals through this list of solid balance sheet and fundamentals (26 results).
- If you prefer steadier income streams, focus on companies with higher payout potential by checking out these 6 dividend fortresses.
- If you are hunting for less crowded opportunities, widen the search to businesses with solid metrics that are still off most radars using these 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com