


- Sectra received approval from Swedish authorities for its quantum resilient Tiger/S stationary phone, which supports SECRET level secure communication and conference calls between and within government entities.
- The new stationary unit links with the already approved mobile Tiger/S devices, creating a unified secure communications system that can deepen Sectra's role in long term national security infrastructure.
- This development may influence how investors view Sectra's investment narrative in light of Swedish approval of its SECRET grade stationary Tiger/S system.
Scan beyond Sectra's security push and line up other defence and secure-communications plays using our hand picked 222 resilient stocks with low risk scores as a starting universe.
Sectra Investment Narrative Recap
Sectra appeals to shareholders who buy into a long haul mix of secure communications and hospital imaging software, with most of the value resting on sticky, recurring contracts. The Swedish Tiger/S approval supports the secure communications story but does not change that near term focus is still on executing large SaaS deployments and managing implementation costs.
The biggest short term swing factor remains how cleanly Sectra converts big enterprise imaging and Sectra One Cloud wins into profitable recurring revenue. A key risk is still project timing and delivery costs, especially if secure communications assignments or large cloud rollouts slip or carry higher infrastructure expense than usage based billing covers.
The Diagnexia agreement in the UK fits directly into those catalysts. It puts Sectra’s imaging IT in the middle of digital pathology case sharing across NHS organisations, which leans into the push for long term cloud and service contracts. That type of usage focused deployment is what supports recurring income visibility.
At the same time, it highlights execution risk. Handling up to 100,000 digital pathology cases in the first year adds operational complexity across integrations, uptime and support. If deals like Diagnexia scale smoothly, they can support the as a service narrative. If delivery drags or costs bite, they can cap the upside investors are hoping for.
Sectra's current analyst storyline points to forecast revenues of SEK 5.8b and earnings of SEK 1.2b by 2029, based on an assumed 15.7% yearly top line growth rate and an earnings increase of roughly SEK 581m from SEK 619.1m today.
Uncover why Sectra's fair value suggests a valuation that is roughly in line with its current price.
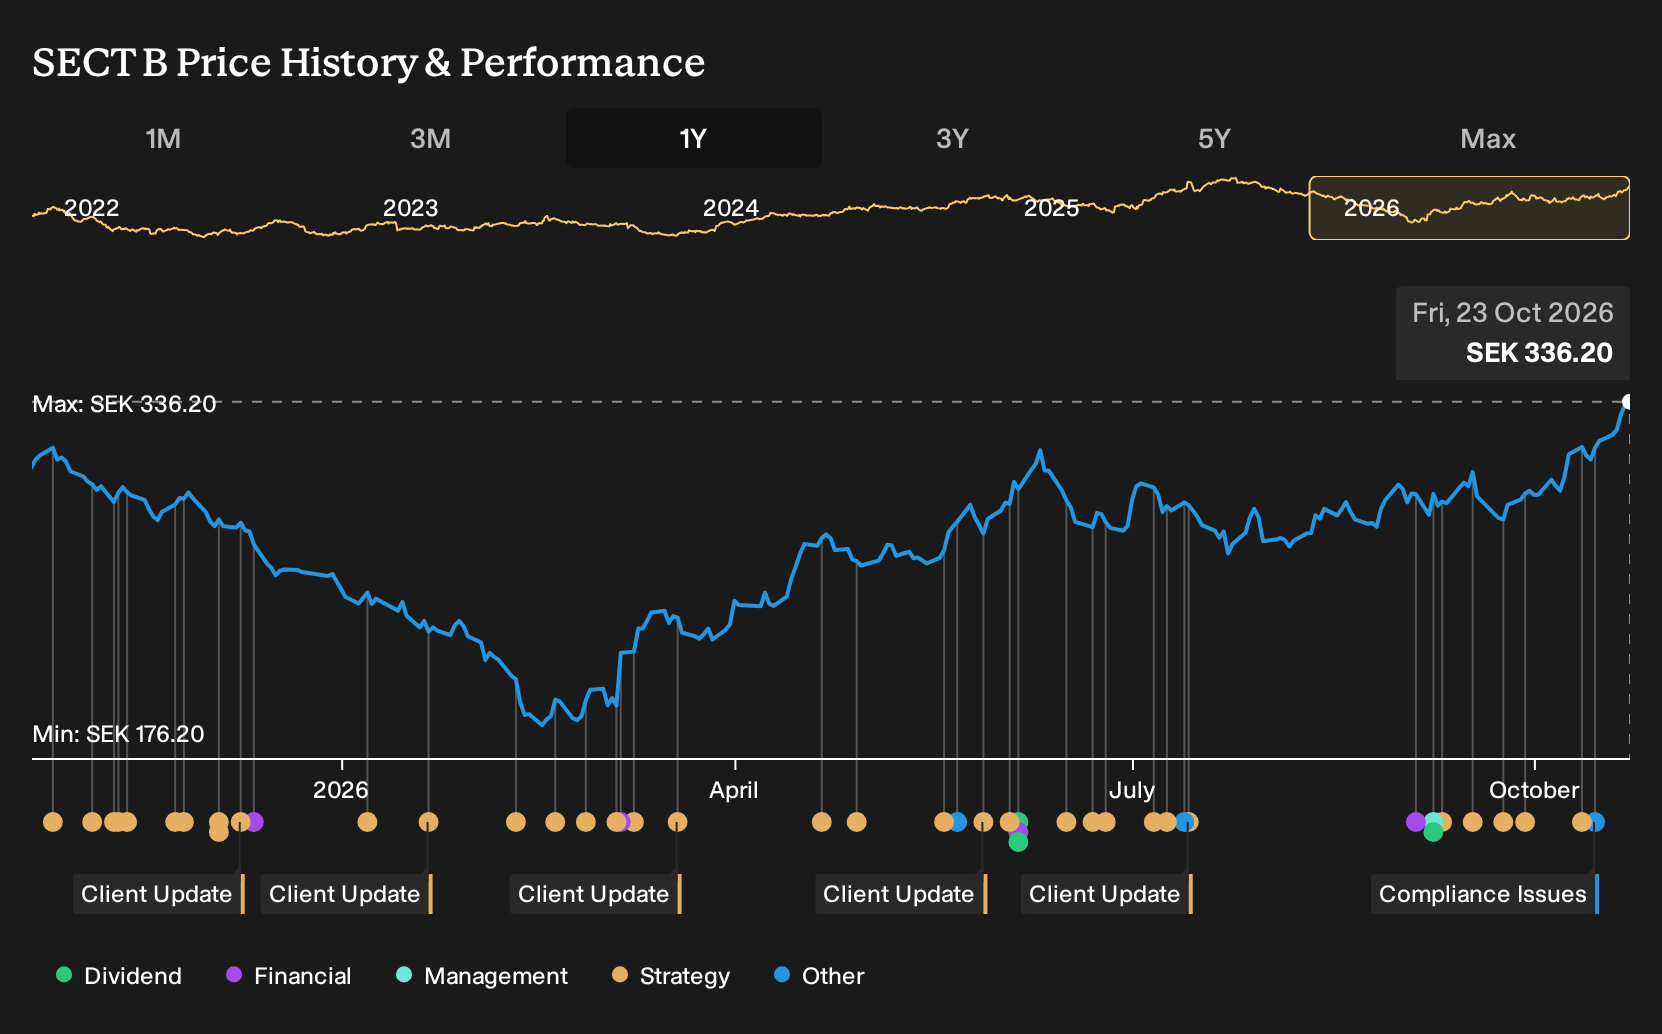
Exploring Other Perspectives
You can interpret this Swedish Tiger/S approval in different ways. The most optimistic analysts already model revenue of about SEK 5.8b and earnings near SEK 1.3b by 2029 for Sectra, which is above the SEK 1.2b consensus. That camp views secure communications as a major accelerator. You can consider whether this news nudges your view closer to that bullish story or keeps you nearer the middle of the range.
Explore 3 other Sectra fair value estimates, including one that suggests it could be worth as much as SEK340.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Sectra research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Sectra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sectra's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sectra?
If this Sectra update has sharpened your thinking but you want a broader watchlist, it helps to line up a few curated shortlists that match different risk and return preferences.
- For potential mispriced opportunities with stronger fundamentals, start with our hand picked 201 high quality undervalued stocks that already pass a quality and value screen.
- If capital preservation sits high on your priority list, build out a watchlist from a list of solid balance sheet and fundamentals (205 results) that can help anchor a more resilient portfolio.
- For investors hunting for less crowded stories with healthy metrics, widen your field of view with a 615 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com