


Yum China Holdings has seen its share price move around over the past few years, and the question now is whether the current US$44.76 level lines up with the cash flows the business can realistically generate. With a Discounted Cash Flow (DCF) estimate available, the stock invites a closer look at how its price stacks up against those underlying streams of cash.
- Over the past 5 years the share price has fallen 16.5%, which puts the focus squarely on whether the cash flow outlook justifies staying invested or taking a fresh look today.
- Recent expansion of the Lavazza coffee joint venture in Hong Kong, including plans to grow the store base and introduce higher end drinks, may support expectations for longer term consumer traffic and cash generation from newer formats.
- Prefer to judge Yum China Holdings on earnings? See what Yum China Holdings's 15.6x P/E says about the price.
For investors, the debate is whether Yum China Holdings' current price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) view over the coming years.
If you want a cleaner comparison point for Yum China Holdings and its coffee led expansion, it can help to line it up against our screener containing 20 high quality undiscovered gems.
Does Yum China Holdings Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here uses a 2 Stage Free Cash Flow to Equity model based on Yum China Holdings' own cash generation. Latest twelve month free cash flow sits at about $872.7 million, with the projections assuming growing cash flows over the next decade rather than a sharp step change or decline.
Those rising cash flow estimates support an intrinsic value that the DCF suggests is meaningfully above the current US$44.76 share price. Because the Lavazza expansion in Hong Kong targets higher spending coffee drinkers in premium locations, that growth push helps explain why the model leans on steady future cash generation rather than a flat profile. For readers comparing price and cash flow, the gap implied here is what the valuation tool is designed to spell out in detail. Find out what Yum China Holdings could be worth using our Discounted Cash Flow (DCF) estimate.
The Yum China Holdings Narrative: What Would Justify Today's Price?
Narratives on the Simply Wall St Community page pick up where the Yum China Holdings valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the share price to move meaningfully above or below where it trades today. Each scenario ties a fair value to a specific mix of possible catalysts and risks so you can watch over time which version of the story Yum China Holdings' results appear to support.
One of the top community narratives on Yum China Holdings: 28% undervalued
"The main thing that has to go right is that Yum China executes on its modular, lower capex store formats and Pizza Hut China brand ownership…"
Discover why this Narrative puts Yum China Holdings at 28% undervalued.
One more unresolved piece in the Yum China Holdings story
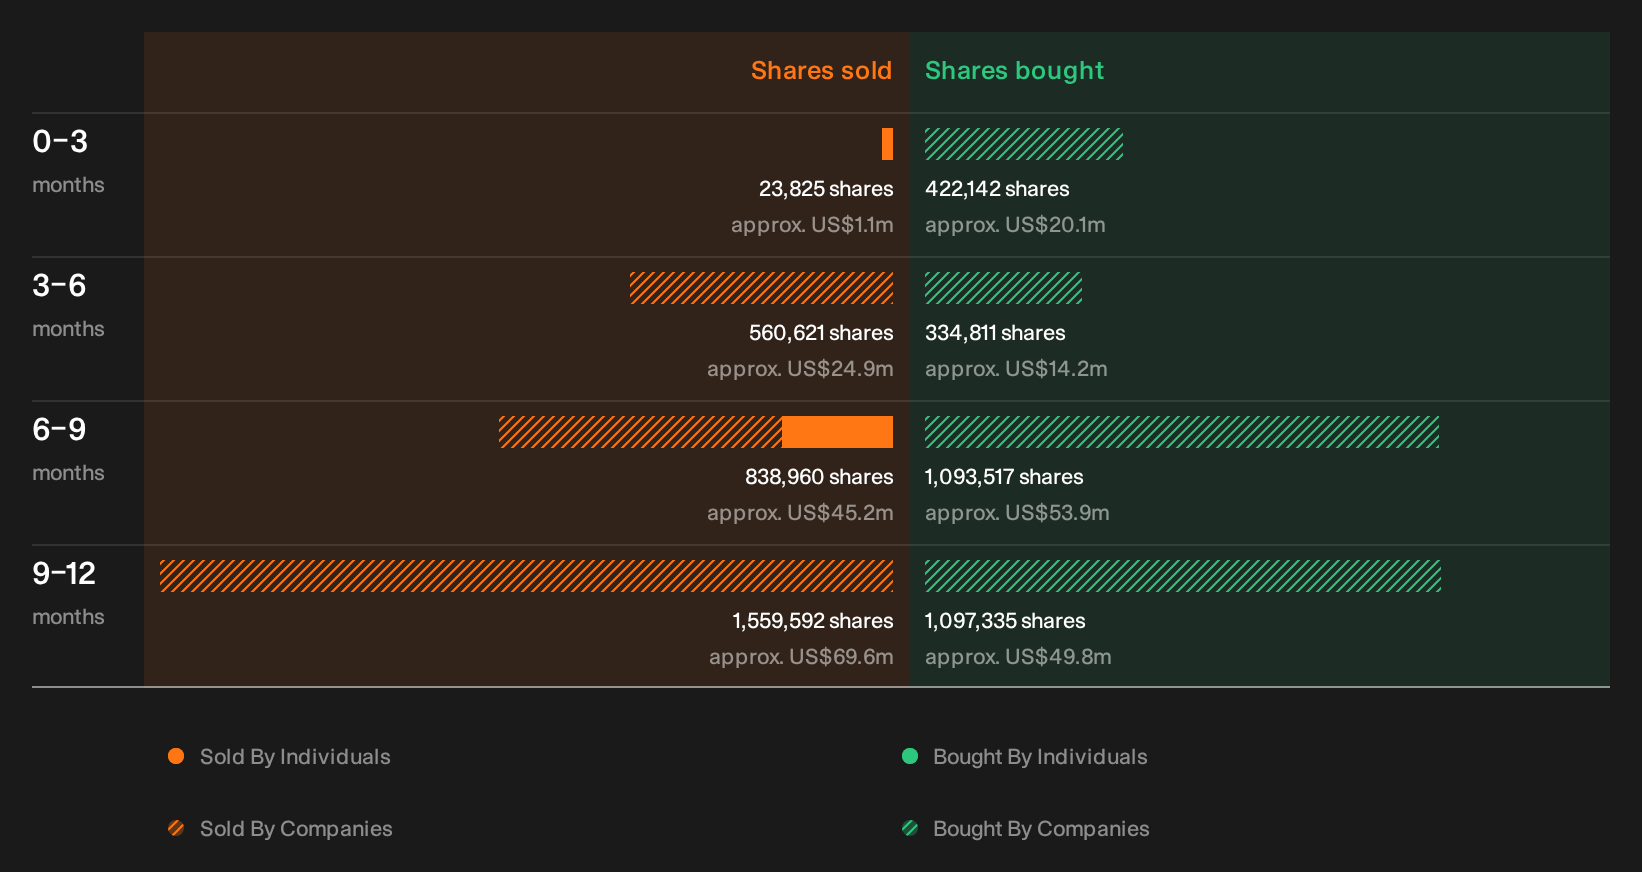
There is one data point the valuation work does not address: the recent selling by people on the inside, and the identities, sizes and possible angles are left for you to examine. See the recent insider selling flagged for Yum China Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com