


- Iron Mountain recently confirmed that it will report Q3 results on 5 November 2026, with analysts projecting a higher diluted EPS than a year earlier and pointing to consistent past outperformance versus expectations.
- The business is leaning more on digital services and data focused solutions, as new partnerships and industry recognition extend Iron Mountain beyond its traditional storage roots.
- We will look at how Iron Mountain's investment narrative is shaped by rising expectations around digital services and the upcoming Q3 earnings report.
Scan beyond Iron Mountain and line up other data focused infrastructure plays using our curated list of 55 AI infrastructure stocks as the earnings season unfolds.
Iron Mountain Investment Narrative Recap
Iron Mountain appeals to investors who buy into a simple idea. Its high cash generating records management arm funds expansion in data centers, digital solutions and asset lifecycle management. The Q3 report on 5 November is likely to matter most as evidence that these newer areas are scaling cleanly alongside the legacy storage operations.
The key short term swing factor is execution on that data center and digital build out, given the capital spend and power needs involved. The biggest risk right now is that heavy investment and leverage meet slower leasing or funding pressure. This earnings release may influence confidence in how well that balance is being managed.
With no fresh company announcements tied directly to this earnings date, the most relevant context is the existing plan to energize about 325 megawatts of data center capacity over the next 18 to 24 months. A portion of that capacity is not yet leased, so investors are watching how Iron Mountain converts pipeline interest into signed contracts.
Those build commitments sit alongside roughly US$553 million of recent growth capex and a US$1.5b senior notes issue at a 6.25% coupon, which raises the bar for execution. Detailed Q3 disclosure on utilization, power delivery timing and asset lifecycle management traction would relate directly to these catalysts and to the leverage and funding risks already highlighted by analysts.
Iron Mountain Earnings Expectations In Context
Iron Mountain's analyst narrative points to revenues of US$9.9b and earnings of US$764.5m by 2029, anchored to an assumed 9.5% yearly revenue growth rate and an earnings step up of about US$345.8m from the current US$418.7m level. That move is framed as a path from "earnings today" to a 2029 consensus target.
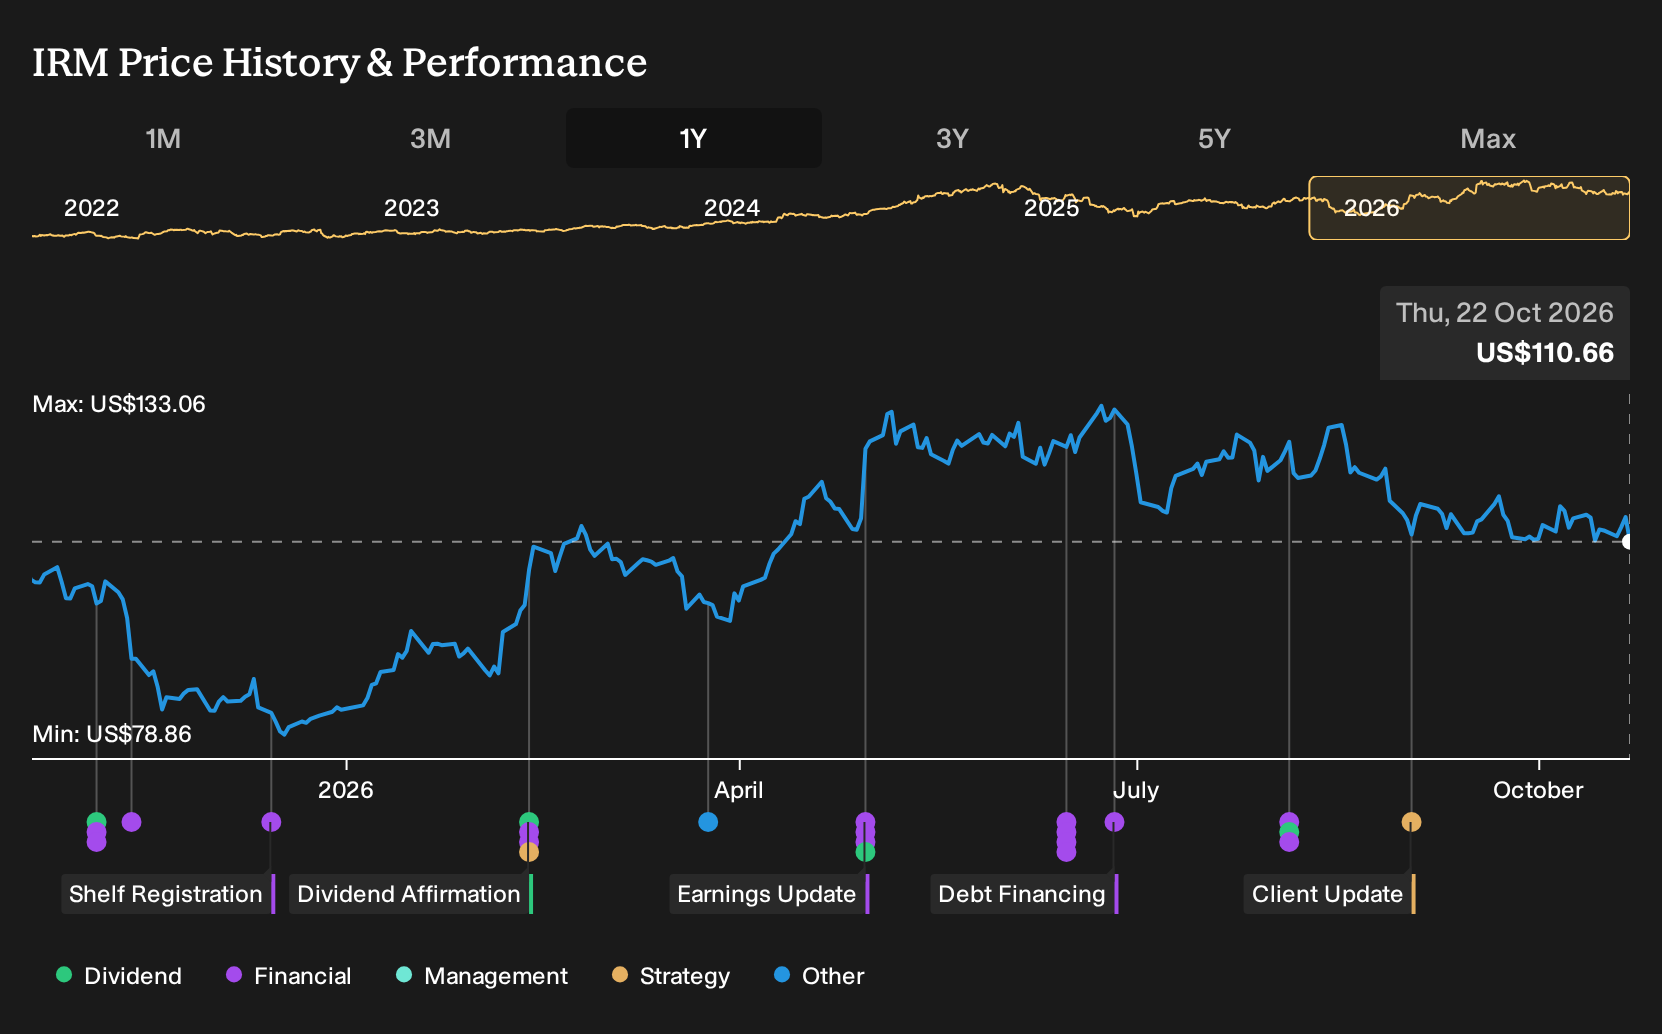
Uncover why Iron Mountain's fair value indicates a 31% potential upside to its current price. This gap could narrow quickly once sentiment shifts.
Exploring Other Perspectives
One alternate view worries less about data center leasing risk and more about lower margin Asset Lifecycle Management pulling on Iron Mountain’s profitability. The most cautious analysts were pencilling in about US$9.0b of 2029 revenue and US$554.4m of earnings. Those forecasts came before this Q3 update, so expect opinions to move.
Explore 4 other Iron Mountain fair value estimates, including one that suggests it could be worth just $144.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iron Mountain research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Iron Mountain. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iron Mountain's overall financial health at a glance.
Looking For More Investment Ideas Beyond Iron Mountain?
If Iron Mountain has sharpened your thinking about data rich infrastructure, use that momentum to broaden your watchlist. The Simply Wall St Screener can help you quickly scan for other opportunities that fit your risk tolerance and income needs.
- If you want potential mispricing on your side, start with a curated pool of quality businesses that trade below their estimated worth through our 29 high quality undervalued stocks.
- For investors who care most about resilience, narrow your search to companies with stronger balance sheets and solid fundamentals by using the list of solid balance sheet and fundamentals (26 results).
- If reliability and income sit at the top of your checklist, focus on firms offering higher yields and robust payout profiles using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com