


Applied Materials (AMAT) is back in focus after sector wide commentary on supply bottlenecks and tight cleanroom capacity dragged semiconductor equipment stocks lower, even as underlying chip demand signals remain firm.
Applied Materials has been hit hard in the recent semiconductor sell off, with the share price down about 8% in a day, 21% over the past month and nearly 30% over 90 days, as investors react to sector wide supply and cleanroom bottleneck headlines rather than demand weakness. Even after that pullback, the year to date share price return of 39.69% and 1 year total shareholder return of 65.10% reflect longer term momentum that is still ahead of the recent slump.
Spot opportunities beyond Applied Materials by reviewing our curated list of 55 AI infrastructure stocks.Applied Materials looks like a powerful franchise tied to AI chip spending, yet the recent 30% slide resets the entry point. Is this still a strong business at too rich a price, or has sentiment overshot the fundamentals?
Most Popular Narrative: 41% Undervalued
Applied Materials last closed at $375.58, while the most followed narrative pegs fair value at $638.94. This implies a wide valuation gap that investors now have to weigh against fresh guidance on growth, margins and capital intensity.
The mix shift toward leading edge foundry logic, DRAM including high bandwidth memory, and advanced packaging is expected to account for most wafer fab equipment growth in 2026 and 2027, and Applied Materials is forecasting more than 70% growth in advanced packaging revenue and more than 50% growth in process diagnostics and control in 2026. This points to a richer product mix that can support margins and net income.
See why 321 investors see Applied Materials as 41% undervalued.
Result: Fair Value of $638.94 (UNDERVALUED)
Still, the thesis around Applied Materials can crack if heavy EPIC and capacity spending keeps pressuring free cash flow, or if flat gross margin guidance limits future earnings leverage.
Find out about the key risks to this Applied Materials narrative.
Another View: What The P/E Says About Applied Materials
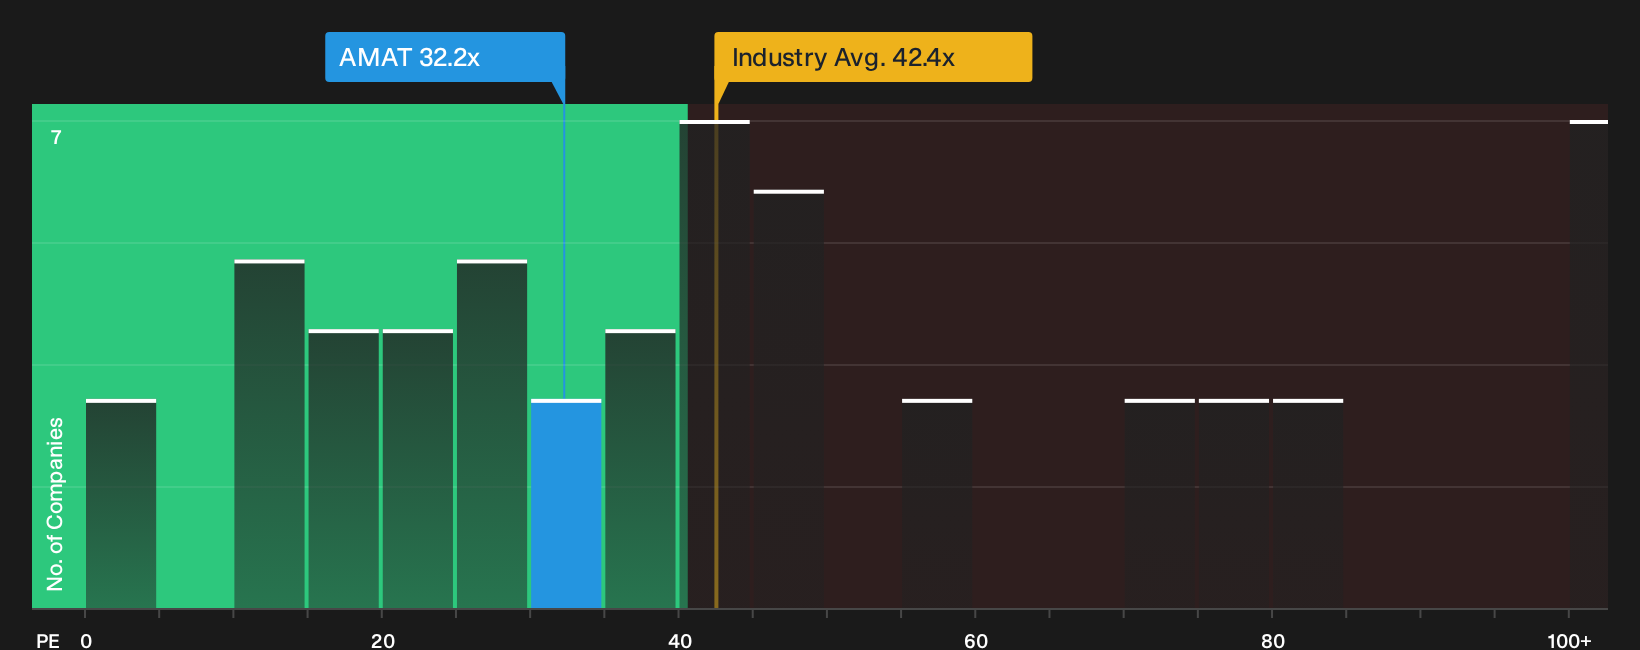
There is a very different signal once you switch from narrative fair value to the hard math of earnings multiples. Applied Materials trades on a P/E of 32.2x, below the US Semiconductor industry at 42.4x and under peers at 34x, while the fair ratio sits even higher at 42.8x.
That gap suggests the market is pricing in some risk that earnings or sentiment cool, even as current profitability and forecasts look strong on paper. The question for you is whether that discount feels like sensible caution or an opportunity that assumes too much pessimism.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Applied Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the bullish narratives and the clear pressure points around Applied Materials is normal, and the quickest way to cut through the noise is to work through the key data points yourself, then weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Applied Materials?
If you are serious about improving your returns, do not stop at Applied Materials. Let the data surface fresh opportunities that match your style and risk tolerance.
- Target potential mispricings early by scanning companies that screen as quality and are priced below their fundamentals with the 29 high quality undervalued stocks.
- Build a steadier income base by researching companies that consistently return cash to shareholders using the 6 dividend fortresses.
- Dial down portfolio stress by focusing on financially resilient businesses via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com