


Garmin (GRMN) just rolled out a fresh wave of cycling hardware, headlined by the voice-enabled Edge 1060, new Edge Explore units and the Tacx Nera smart trainer, putting connected fitness firmly in focus for shareholders.
That launch comes after an already strong run for Garmin, with a 90 day share price return of 21.55% and a year to date share price return of 45.92%. Total shareholder return over three and five years of 208.27% and 126.68% respectively signals momentum that long term holders have already experienced.
Scan Garmin’s latest connected fitness launch against hand-picked peers by reviewing the list of solid balance sheet and fundamentals (26 results), which may appeal to investors who care about both product strength and financial resilience.
Garmin’s share price already reflects a strong run and a crowded product slate in cycling and aviation. Does the current valuation still compensate you for the risk of buying in after this move, or has the easy upside already been taken?
Most Popular Narrative: 2% Undervalued
Garmin last closed at $295.40, which sits slightly below the most followed fair value estimate of $302, so the current story leans on a modest valuation gap rather than a deep discount.
The launch of the Garmin Connect+ premium service, which offers AI based health and fitness insights, is likely to boost subscription based revenue growth and improve overall margins through higher margin services.
The acquisitions of TrainingPeaks and TrainHeroic, which add endurance and strength training platforms around Garmin wearables, are expected to deepen the service ecosystem and create more recurring revenue streams that can support gross margin and operating margin over time.
See why 49 investors see Garmin as 2% undervalued.
Result: Fair Value of $302 (UNDERVALUED)
Still, the narrative can crack if weakness in the Outdoor segment persists or the Auto OEM segment slips back into operating losses and drags on Garmin’s group level profitability story.
Find out about the key risks to this Garmin narrative.
Another View: Garmin Through a P/E Lens
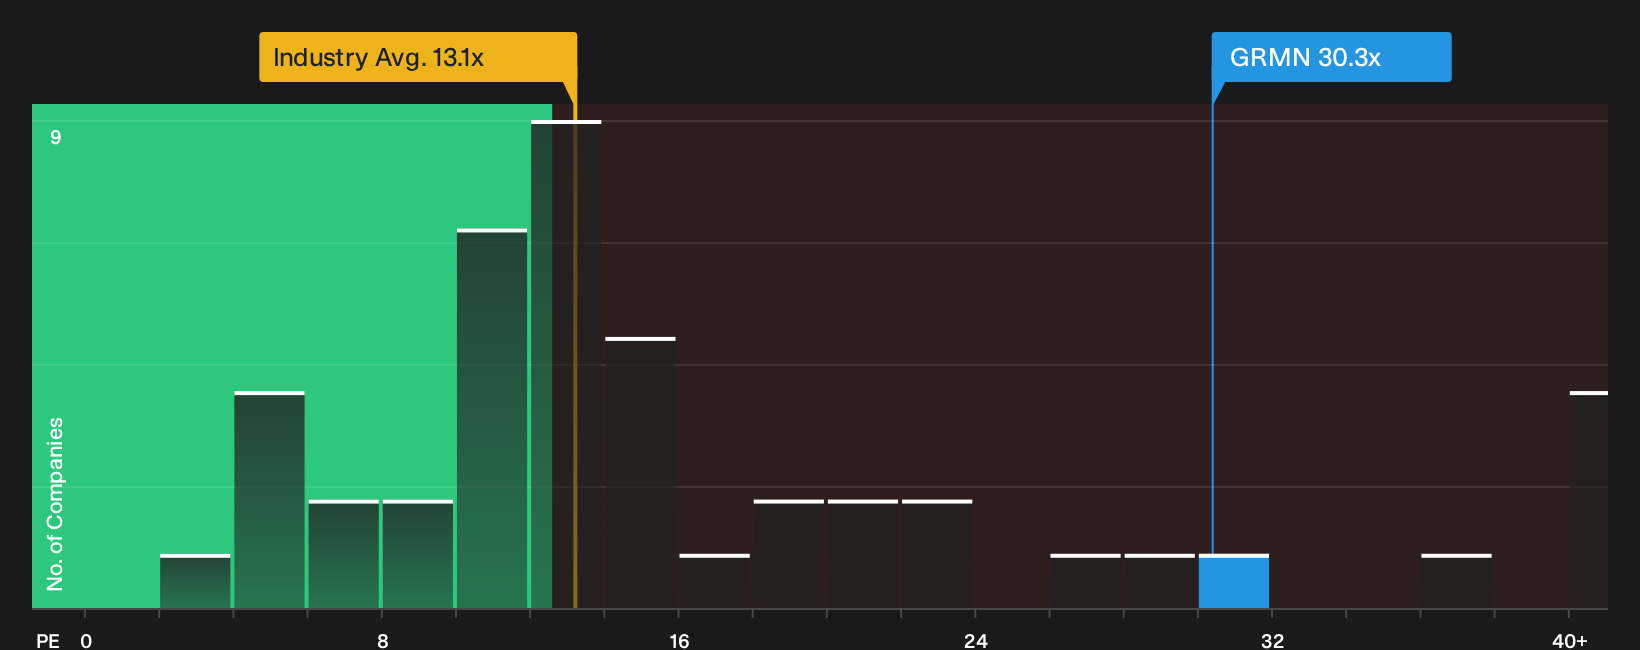
Garmin screens differently once you move away from fair value estimates and look at simple earnings multiples. The shares trade on a P/E of 30.3x, compared with a fair ratio of 22.5x, the Consumer Durables industry at 13.1x and peers at 27.3x. That gap points to richer expectations baked into the price, so the question is whether you think the story justifies paying a premium.
For a closer look at how these valuation gaps stack up against earnings power and sector peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism about Garmin and concern over specific weak spots feels familiar, that is exactly the point that should push you to inspect the data yourself and form your own stance. To weigh both sides with clear numbers and context, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Garmin?
Do not stop with a single ticker when the broader market is full of other potential opportunities that match different goals, timeframes and risk levels.
- Target potential mispricing by scanning a focused set of companies that screen as both financially strong and possibly overlooked through the 29 high quality undervalued stocks.
- Build a steadier income stream by reviewing a curated pool of higher yielding payers through the 6 dividend fortresses.
- Dial down portfolio risk by filtering for businesses that pair healthier balance sheets with sturdier fundamentals using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com