


Dorman Products (DORM) cut its full year net sales outlook to a range of 3% to 5% and clarified that a recent 46.1% adjusted gross margin was boosted by a one off tariff refund.
Dorman Products shares have reacted to the cut in sales guidance and the clarified gross margin boost, with the stock up 5.53% over the past month but still down 5% over the past three months as investors reassess growth risk.
Compare Dorman Products with other aftermarket and auto suppliers by scanning a curated set of list of solid balance sheet and fundamentals (26 results) that may better match your risk and growth preferences.
Dorman Products now trades between a trimmed growth outlook and a share price that already bounced on the news. Does fair value lean closer to the current US$127.49 or to analyst targets near US$161.63?
Most Popular Narrative: 21% Undervalued
Dorman Products is pinned between a last close of $127.49 and a widely followed fair value view of $161.63, which frames the current debate around whether the aftermarket parts supplier is being priced too cautiously. That gap reflects a thesis that aging vehicles, margin targets and balance sheet flexibility can support stronger earnings than the market is currently baking in.
The increasing average age of light duty vehicles to 12.9 years, together with higher vehicle miles traveled and riders holding specialty vehicles for longer, continues to feed a large installed base that still needs non discretionary repairs. This can support steady aftermarket volumes and revenue for Dorman Products.
Dorman Products is investing in differentiated new products such as OE Fix solutions, DEF aftertreatment components and accessory lines with proprietary designs and electronics. These products can shift mix toward higher margin content and support gross margin and operating margin expansion.
See why 7 investors see Dorman Products as 21% undervalued.
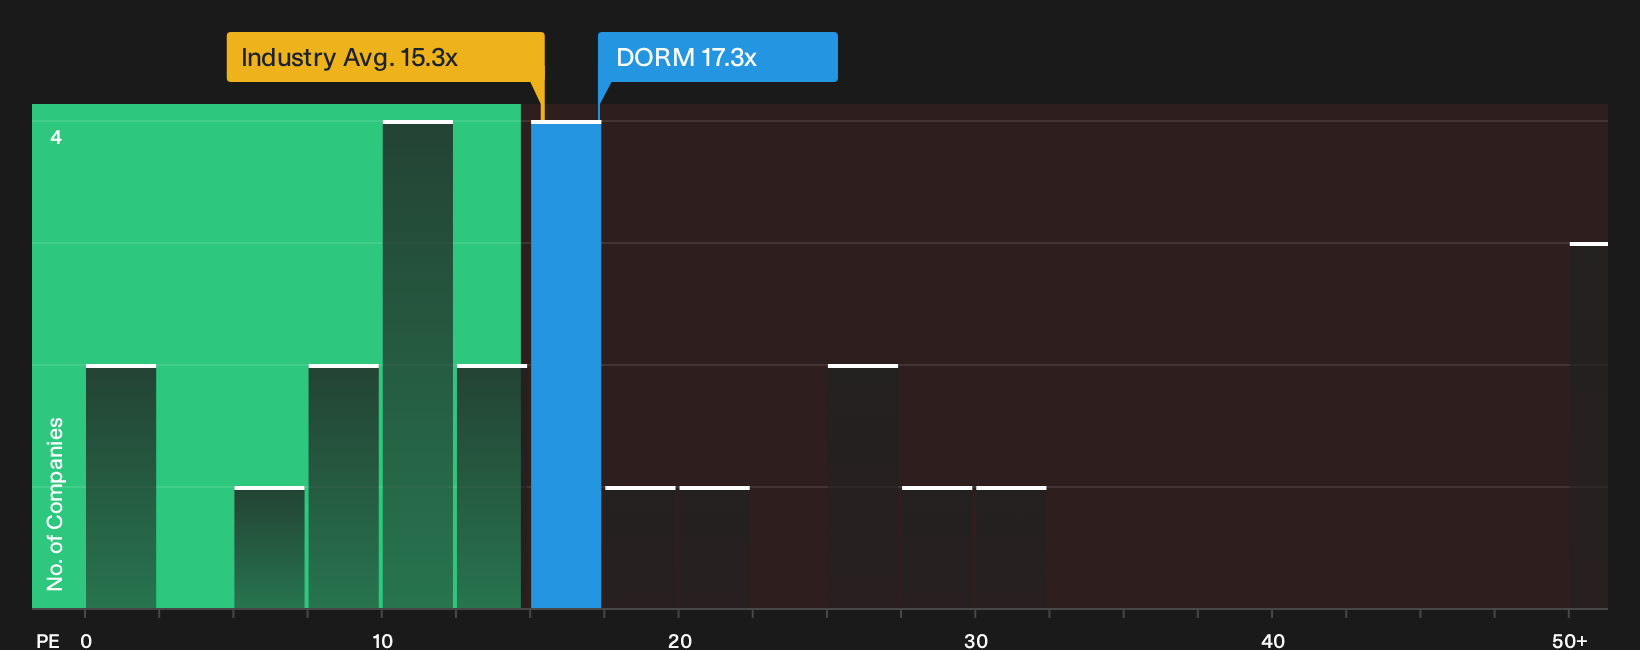
On this narrative, the $161.63 fair value is built using an 8.75% discount rate and analyst assumptions that Dorman Products grows revenue at about 5.2% a year, lifts profit margins from 10.2% to 13.4%, and continues to generate what Simply Wall St categorizes as high quality earnings. Those inputs imply earnings of $336.0m and a P/E of 16.8x by 2029, compared with a current P/E of 17.3x and an industry average of 15.5x. The story therefore leans on gradual earnings expansion rather than a rerating alone.
Set against the trimmed 3% to 5% net sales guidance and softer recent margin prints, this puts the burden on Dorman Products to convert that aging vehicle fleet and OE Fix pipeline into consistent volume and pricing while managing tariff swings and discretionary specialty categories. If the firm meets those hurdles, the current price sits only 1.1% below Simply Wall St's separate DCF fair value estimate of $128.90, yet about 21% below the narrative fair value, which is why many investors treat the stock as modestly undervalued rather than obviously cheap or clearly expensive.
Result: Fair Value of $161.63 (UNDERVALUED)
Still, trimmed 3% to 5% net sales guidance and margin pressure from tariff swings or weaker specialty vehicle demand could quickly challenge the bullish Dorman Products narrative.
Find out about the key risks to this Dorman Products narrative.
Another View: Dorman Products On Earnings Multiples
While the Dorman Products narrative leans on a US$161.63 fair value, earnings multiples tell a cooler story. The stock trades on a P/E of 17.3x, richer than the Auto Components peer average of 11x and above a fair ratio of 13.7x. This points to valuation risk if growth or margins disappoint. Does that premium reflect resilience, or is it simply optimism being paid for upfront?
To see how this earnings multiple picture fits with other valuation checks, including the fair ratio and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling that the Dorman Products story could tilt either way from here. Move quickly, review the upside signals, and weigh the 3 key rewards against your own expectations.
Looking for more investment ideas beyond Dorman Products?
If Dorman Products feels finely balanced for your portfolio right now, it makes sense to widen the net and compare it with a few targeted ideas on the Simply Wall St screener.
- Target potential mispricings by scanning a focused set of 29 high quality undervalued stocks that line up with your expectations on quality and balance sheet strength.
- Strengthen your income stream by reviewing a curated group of 6 dividend fortresses that match your tolerance for volatility and payout consistency.
- Get ahead of the crowd by checking a tight shortlist of 20 high quality undiscovered gems before attention and liquidity potentially shift toward them.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com