


Why Knowles Stock Is Back in Focus
Knowles (KN) moved into the spotlight after reporting third quarter 2026 results that topped analyst expectations on both revenue and earnings, alongside guidance for the fourth quarter and full year that analysts described as upbeat.
Despite the upbeat Q3 report and guidance, Knowles shares recently pulled back, with a 1-day share price return of 4.41% down and a 30-day share price return of 9.56% down, even though the year to date share price return is 52.07% up and the 3-year total shareholder return is 153.26% up. This suggests short term profit taking against a still strong longer term narrative around earnings progress and perceived risk.
Scan other companies showing similar earnings momentum and sector exposure as Knowles with the curated 20 high quality undiscovered gems.
Knowles recently rallied on improving earnings, then slipped as some holders locked in gains. At this price and after this swing, does the balance of potential upside and downside still appeal to new buyers?
Most Popular Narrative: 31% Undervalued
On the most followed view, Knowles is worth $48.00, which sits well above the recent $33.38 close and frames the recent pullback as a valuation gap driven more by sentiment than by the latest fundamentals.
The specialty film pulse power platform, including the large energy order that is now running at yields better than planned, provides a template Knowles can apply to future medical, defense, and industrial film programs. This could widen the product mix at higher contribution margins and lift overall gross margin for Precision Devices.
See why 2 investors see Knowles as 30% undervalued.
Result: Fair Value of $48.00 (UNDERVALUED)
Still, the bullish Knowles story frays quickly if recent double digit revenue gains cool, or if the past five year pattern of declining sales and modest EPS growth returns.
Find out about the key risks to this Knowles narrative.
Another View: Knowles Looks Rich On Earnings
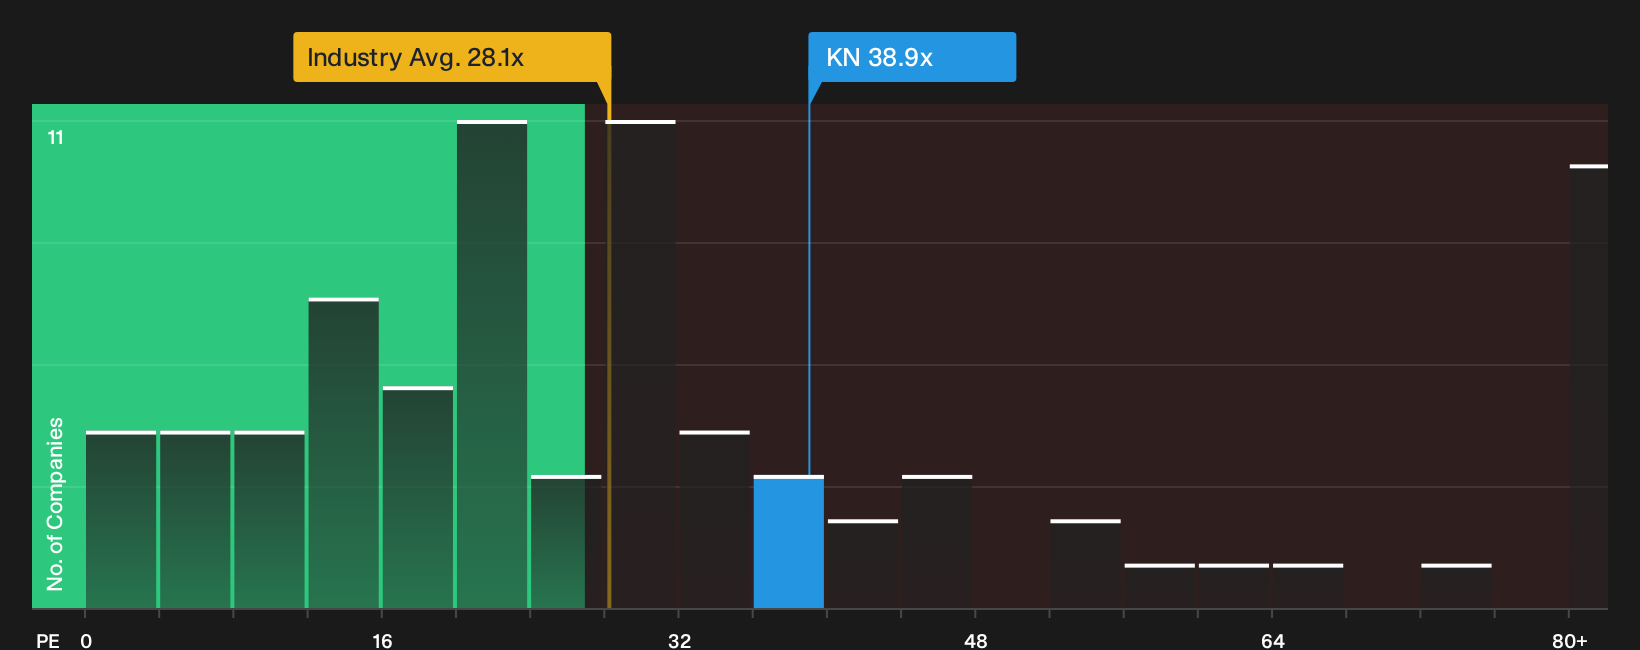
The popular fair value of $48.00 paints Knowles as undervalued. A second lens tells a different story. The shares trade on a P/E of 38.9x, which is lower than peer averages at 69.9x, but higher than both the US Electronic industry on 28.5x and a fair ratio of 28.8x. That gap points to valuation risk if sentiment cools or earnings expectations ease.
To see how this earnings based picture could evolve as results come through, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Knowles for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The story so far paints Knowles as promising yet finely balanced, so move fast, pressure test the assumptions, and decide where you stand. To see which potential upsides our work highlights, review the 3 key rewards
Looking for more Knowles style investment ideas?
Do not stop with Knowles. Broaden your watchlist now, or you risk missing other opportunities that match your approach and risk comfort.
- Target potential mispricing by scanning a focused set of companies that combine quality with appealing entry points through the 29 high quality undervalued stocks.
- Strengthen your defensive side by checking companies that pair financial resilience with cleaner balance sheets using the list of solid balance sheet and fundamentals (26 results).
- Round out your research with stocks that score well on internal risk checks by reviewing the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com