


Eurozone growth is losing steam, political stress in France is rising and inflation pressures are lingering, so capital is quietly drifting toward companies that can keep paying investors even when confidence cools. That shift creates a window in which high quality dividend payers exposed to this latest PMI shock could either offer resilience or introduce fresh risk. This article examines three eurozone stocks shaped by those forces and outlines what that could mean for your portfolio.
The three stocks covered next are a sample, while the full screen surfaced 16 more large eurozone dividend payers with equally detailed stories that do not fit into this article. To identify and analyze the highest conviction income ideas in this universe, head straight to the Defensive, high-quality dividend stocks in the eurozone screener.
Ebro Foods (BME:EBRO)
Overview: Ebro Foods is a Spanish-headquartered food group that produces rice, pasta and prepared dishes for consumers worldwide across multiple brands.
Operations: The business generates about €2.3b from its rice division and €0.7b from pasta, with Spain a smaller share than overseas markets.
Market Cap: €2.8b
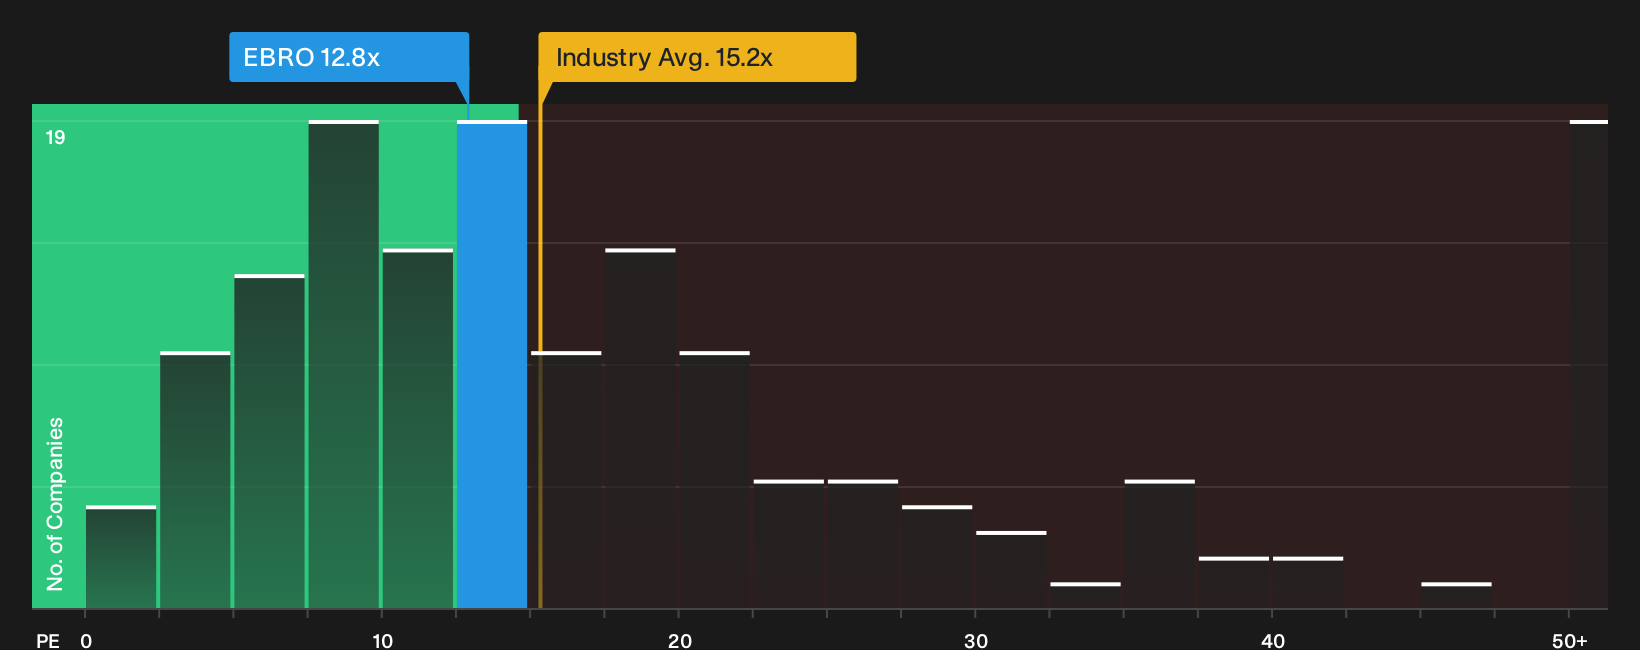
Ebro Foods fits this defensive eurozone dividend screen because it sells everyday food staples, generates cash and carries a mid-sized market value. Earnings have grown faster than the wider food sector and the shares trade on a lower P/E. This valuation can be relevant in periods when growth slows and rates remain high. Dividend reliability depends on how one unseen pressure plays out.
That unseen pressure is already moving beneath the surface. Go straight to the 3 key rewards and 1 important warning sign and see what the headline yield might be masking.
Siemens Healthineers (XTRA:SHL)
Overview: Siemens Healthineers develops medical imaging systems, diagnostic tests, cancer therapy equipment and related services that help hospitals and labs deliver everyday patient care worldwide.
Operations: Siemens Healthineers generates about €13.2b from Imaging and €4.1b from Diagnostics, with other segment effects taking reported revenue to around €22.2b.
Market Cap: €46.5b
Siemens Healthineers fits a defensive dividend screen because healthcare demand typically holds up when growth softens. The group combines scale, cash generation and global reach that many eurozone peers cannot match.
"Strong, ongoing innovation in advanced imaging and AI-driven diagnostic solutions is now reflected in an equipment book-to-bill of 1.27, with photon-counting CT already representing roughly 30% of total CT equipment order volume and supporting future revenue and earnings from a higher value mix."
The real swing factor is how one underappreciated segment reshapes future margins and the capacity to keep rewarding income focused shareholders.
That margin story is only sketched here, while the full narrative for Siemens Healthineers explains how Siemens Healthineers could see earnings power diverging from headline equipment orders.

Danone (ENXTPA:BN)
Overview: Danone is a Paris based food and beverage group focused on dairy, plant based products, specialized nutrition and bottled water worldwide.
Operations: Danone generates about €13.2b from Essential Dairy and Plant Based products, €9.4b from Specialized Nutrition and €4.9b from Waters.
Market Cap: €40.1b
Eurozone growth worries and French political noise have pushed more investors toward Danone, which combines everyday consumption, global reach and a long dividend record in a classic defensive staples profile.
"Continued innovation and expansion in health-driven, functional foods and specialized nutrition, such as high-protein, probiotic, and medical nutrition products, positions Danone to capture above-market revenue growth as global consumers become increasingly focused on wellness and science-based nutrition."
What happens to Danone’s income profile if one less visible funding and leverage constraint starts to bite just as that wellness story scales.
If that funding squeeze is on your mind, read the full narrative for Danone to see how Danone’s cash generation, payout capacity and wellness push could be decoupling.

Seeking Alternatives Before The Crowd
Fresh opportunities do not wait. Capital chases the next breakout while early data still matters and prices have not fully caught the momentum. Screen under the radar ideas and act now.
- Spot cash rich balance sheets before they get re rated by tracking the curated list of solid balance sheet and fundamentals (205 results). It filters for strength while others focus only on headlines.
- Ride earlystage AI momentum instead of chasing parabolic moves by scanning the hand built universe of 39 profitable AI stocks that aren't just burning cash. These are already turning algorithms into real earnings.
- Position ahead of the next power upgrade cycle by tracking infrastructure players inside the focused 42 power grid technology and infrastructure stocks while they are still priced like old economy utilities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com