


SK Hynix (SKHY) shares are extending gains on Friday after the memory chipmaker halted plans to list Solidigm separately. While investors welcomed the removal of a contentious fundraising proposal, SK Hynix confirmed that Solidigm’s expansion remains a priority, with alternative financing under consideration.
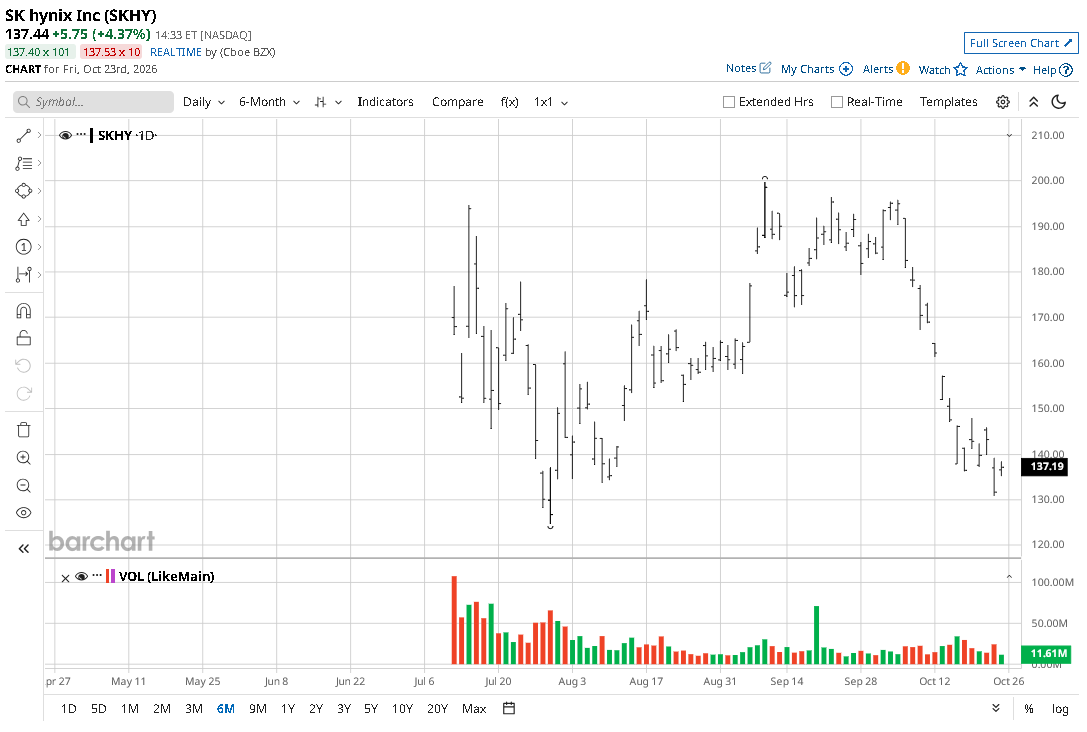
Despite today’s rally, SK Hynix stock is down more than 30% versus its year-to-date high.
What Solidigm News Really Means for SK Hynix Stock
SK Hynix discontinued reviews of both a potential Solidigm initial public offering (IPO) and pre-IPO fundraising, citing market volatility and semiconductor share-price trends.
The proposed listing had attracted shareholder opposition and regulatory scrutiny over concerns of dilution and a potential discount to SKHY valuation.
For investors, the positive interpretation is straightforward. Shelving the offering avoids issuing outside investors a separate stake in Solidigm for now, preserving existing shareholders’ indirect exposure to its growth.
That said, the financing challenge remains. Solidigm still needs additional U.S. production capacity to address growing AI memory demand, and SK Hynix must determine how to fund that expansion.
Should You Invest in SKHY Shares Today?
Beyond Friday’s announcement, SK Hynix shares present a tangible shareholder-return thesis.
In August, its board approved a $29 billion share repurchase and cancellation plan, equivalent to roughly 3.3% of issued shares at the reference price. Management also raised its return target to more than 50% of cumulative free cash flow for 2025–2027.
Cancelling repurchased shares can increase remaining investors’ proportional ownership and boost per-share earnings. The balance sheet adds support: SKHY posted roughly $52 billion in net cash at the end of Q2.
Investors should also note that the memory chip specialist is currently trading at a forward price-to-earnings (P/E) ratio of less than 6x, which makes it rather attractive for a key artificial intelligence (AI) beneficiary.
What’s the Consensus Rating on SK Hynix?
Wall Street analysts also remain convinced that SKHY stock is poised for significant further gains from current levels.
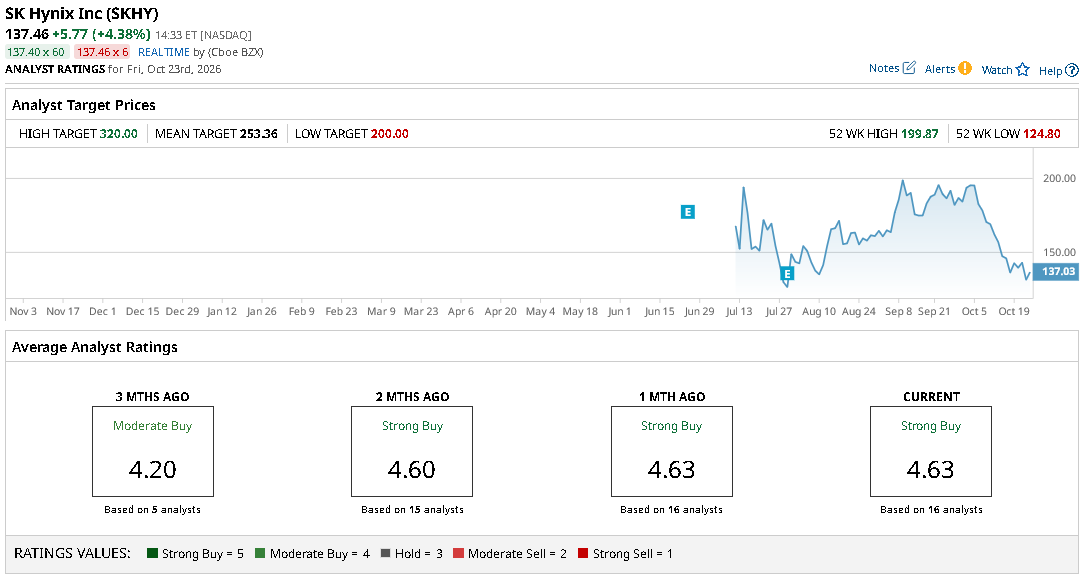
According to Barchart, the consensus rating on SK Hynix sits at “Strong Buy,” with the mean price target of about $253 indicating potential upside of nearly 90% from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.