


Flywire (FLYW) is back in focus after announcing that its Student Financial Software has powered more than 1 million student payment plans, along with upbeat client stories from its recent Flywire Fusion conference.
Recent trading has reflected that story. Flywire’s 1-day share price return of 2.79% and 30-day share price return of 11.08% contribute to a 37.77% year-to-date gain. The 1-year total shareholder return of 43.88% contrasts with a 3-year total shareholder return that is down 27.79%, suggesting short-term momentum is building after a tougher stretch for longer-term holders.
Capitalize on the momentum in Flywire’s education payments niche by scanning a curated 20 high quality undiscovered gems that may be quietly building similar traction in their own verticals.Flywire now trades at a single digit discount to both analyst targets and estimated fair value after a sharp rebound. Is that a sensible margin of safety, or a warning that caution is still warranted?
Most Popular Narrative: 9% Undervalued
On the most followed view, Flywire is worth $21.07 a share, compared with a last close of $19.15, which leaves a modest valuation gap that hinges on how efficiently the payments engine can scale.
Project ADAPT and wider digital transformation are expected to peak in investment in 2027. After that point, management plans to keep operating costs roughly flat while still funding priorities. Recent adjusted EBITDA margin expansion into the low 20% range indicates that further operating leverage could support higher net margins and earnings.
See why 9 investors see Flywire as 9% undervalued.
Result: Fair Value of $21.07 (UNDERVALUED)
Still, visa pressure in key education markets and a shift toward lower margin processing in healthcare and B2B could quickly weaken the bullish Flywire narrative.
Find out about the key risks to this Flywire narrative.
Another View: Flywire Looks Expensive On Earnings
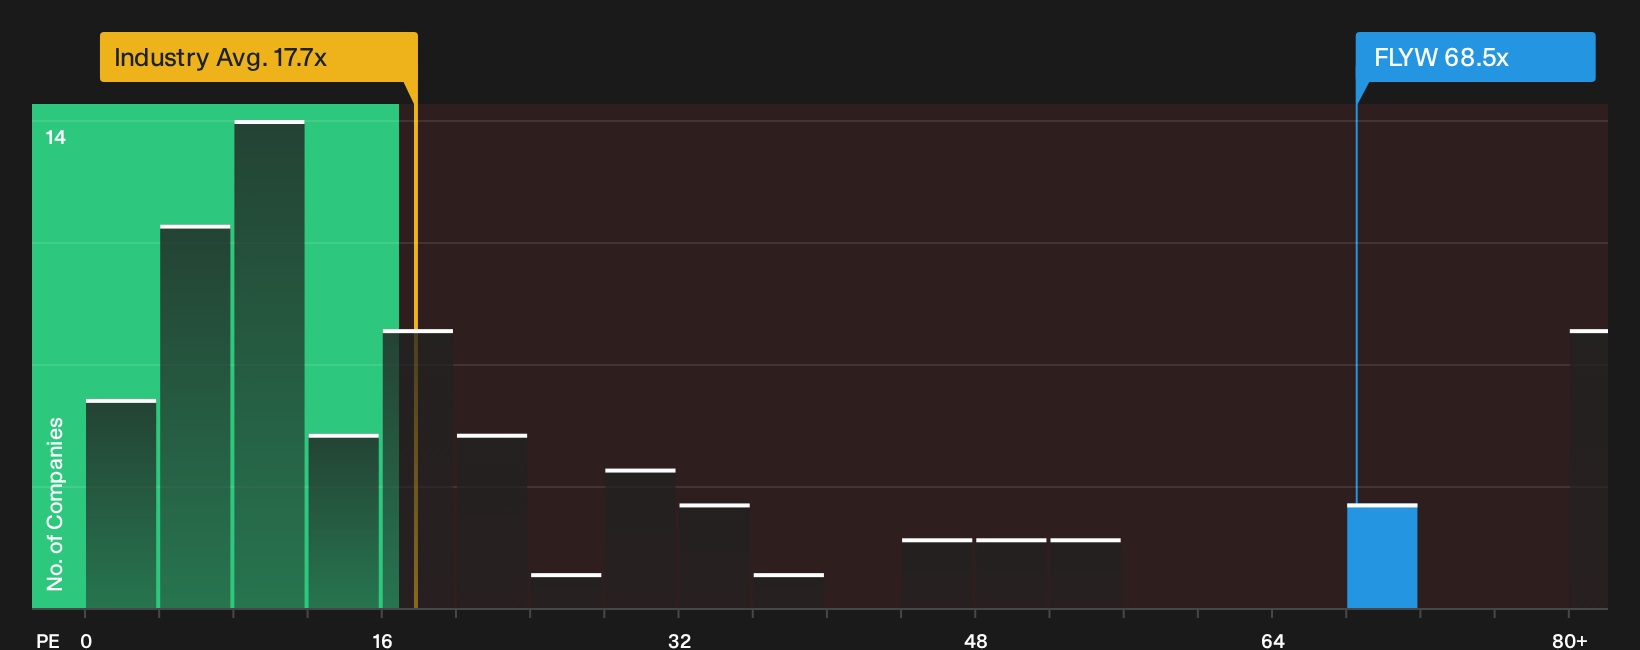
The earlier fair value work paints Flywire as modestly undervalued. A simple P/E check tells a very different story. FLYW trades on 68.5x earnings, while the US Diversified Financial industry sits near 17.6x and the fair ratio estimate is 21.4x. That is a wide gap that raises the risk the share price moves more on sentiment compression than on business progress.
Put differently, investors are paying a premium both to peers at 37x and to where the fair ratio suggests the market could gravitate over time. This limits room for disappointment if earnings or growth expectations are revised. If fair value and earnings multiples are pulling in opposite directions, which signal deserves more weight in your own process, and over what time frame?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Flywire story today. If you want to move before sentiment swings again, consider weighing the potential upside and downside yourself with 3 key rewards and 1 important warning sign
Looking for more Flywire sized opportunities?
Do not stop your research with Flywire alone. The right watchlist often starts with a few quality ideas, then widens into a broader opportunity set.
- Target resilient compounding potential by scanning companies with strong cash generation and supportive valuations through the 29 high quality undervalued stocks.
- Strengthen your income stream by checking out higher yielding payers screened in the 6 dividend fortresses.
- Prioritise capital preservation first by filtering for businesses flagged in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com