


Sany Heavy Equipment International Holdings (SEHK:631) has signed new framework agreements with SANY International Group that formalise revenue sharing for parts agency services and revise fee caps for after sales support through 2027.
For context, Sany Heavy Equipment International Holdings’ share price closed at HK$7.56, with a 1 day share price return of 3.28% that follows a 30 day share price decline of 7.69% and a year to date drop of 12.70%. The 1 year total shareholder return of 2.93% contrasts with a 3 year total shareholder return decline of 22.52%. This suggests that recent momentum has picked up slightly after a weaker multi year stretch as investors weigh these new service agreements against the longer track record.
Compare Sany Heavy Equipment International Holdings’ new service agreements with other capital goods plays by scanning our hand-picked list of list of solid balance sheet and fundamentals (205 results) for potential alternatives in the sector.
Sany Heavy Equipment International Holdings has clawed back a little ground after a weak stretch. The real debate now is whether that rebound reflects most of the opportunity or leaves meaningful upside still on the table as valuation comes into focus.
Preferred P/E Multiple of 12.4x: Is It Justified For Sany Heavy Equipment International Holdings?
Sany Heavy Equipment International Holdings trades on a P/E of 12.4x, which sits above both the Hong Kong Machinery industry average of 10.6x and the peer group average of 9x. At a last close of HK$7.56, that richer earnings multiple points to investors paying a higher price for each unit of profit compared with many sector alternatives.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how the market values a company’s profit stream. For a business like Sany Heavy Equipment International Holdings, which operates across mining equipment, logistics, oil and gas gear and emerging energy technologies, investors often use P/E to weigh how much of the current profit profile is already reflected in the HK$7.56 share price.
On one side, the stock is described as expensive relative to both the Hong Kong Machinery industry and its direct peers, which suggests the market is paying up for its recent 24.8% earnings growth and forecasts that call for 32.25% annual profit growth. On the other side, the estimated fair P/E of 15.5x is higher than the current 12.4x, which signals that if earnings and return on equity forecasts near 21.3% are met, the valuation level could move closer to that fair ratio over time. Result: Price-to-Earnings of 12.4x (ABOUT RIGHT)
Explore the SWS fair ratio for Sany Heavy Equipment International Holdings.
Still, Sany Heavy Equipment International Holdings faces risks if demand across mining or logistics weakens, or if its capital spending in emerging equipment fails to earn attractive returns.
Find out about the key risks to this Sany Heavy Equipment International Holdings narrative.
Another View On Sany Heavy Equipment International Holdings’ Valuation
The SWS DCF model paints a very different picture for Sany Heavy Equipment International Holdings. At a share price of HK$7.56, the stock screens as expensive relative to an estimated future cash flow value of HK$1.96. That gap implies material valuation risk if cash generation does not track optimistic earnings forecasts.
Look into how the SWS DCF model arrives at its fair value.
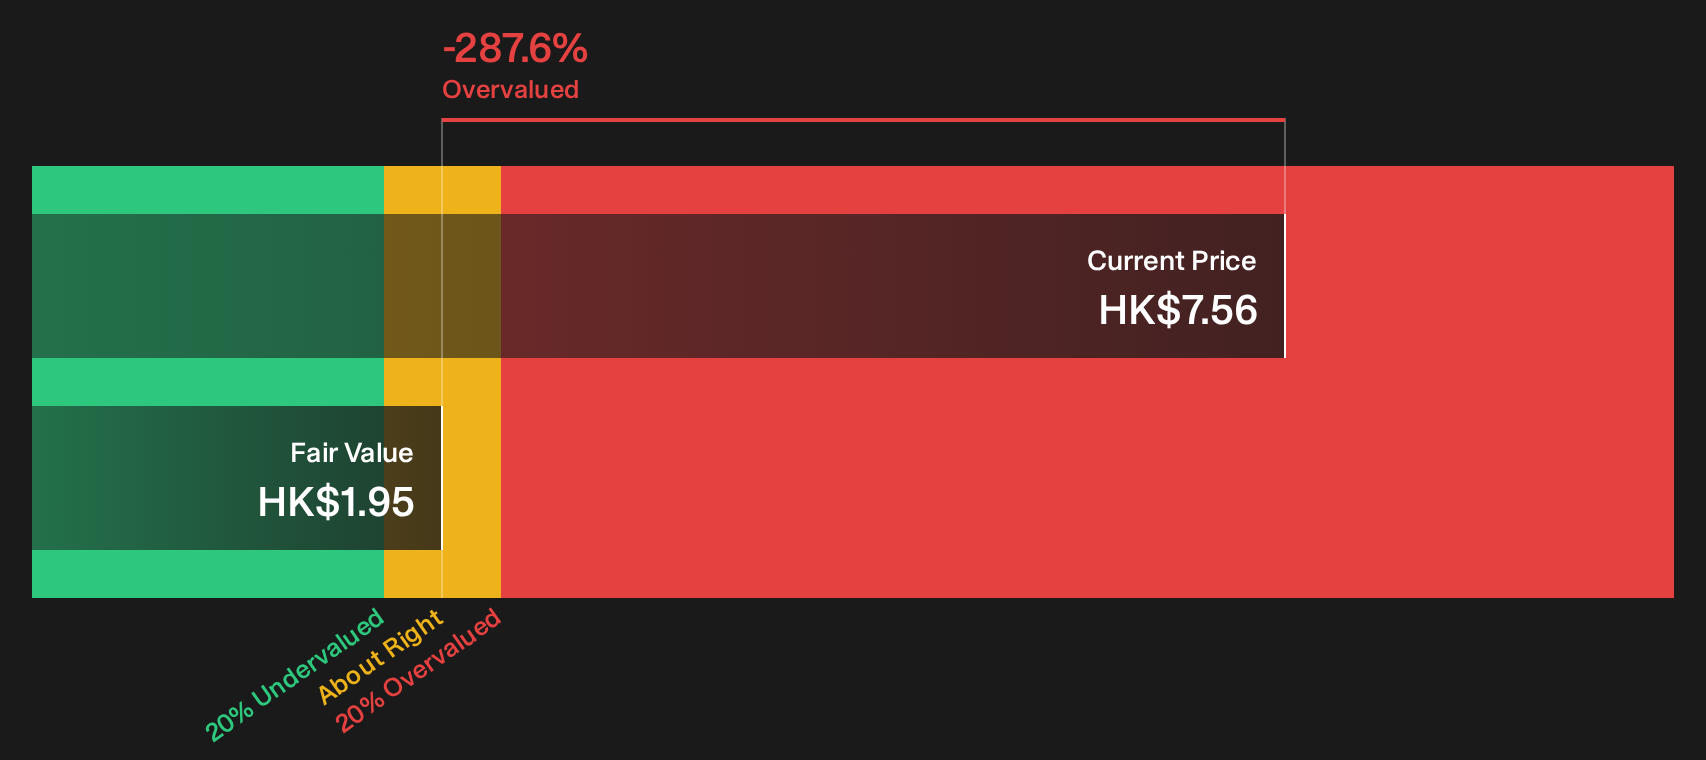
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sany Heavy Equipment International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 201 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sany Heavy Equipment International Holdings’ valuation can feel murky. Check the full data, compare scenarios and pressure test the balance of risks and rewards for yourself with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sany Heavy Equipment International Holdings?
Do not stop at just one opportunity. Use the Simply Wall Street screener to quickly scan different angles on quality, value and resilience across the market.
- Target potential mispricing by reviewing a focused set of 201 high quality undervalued stocks that combine quality fundamentals with appealing valuations.
- Prioritise resilience first by checking a 221 resilient stocks with low risk scores that may better match a cautious approach to capital protection.
- Hunt for fresher ideas by scanning a 615 high quality undiscovered gems that many investors might not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com