


EchoStar (ECHO) drew fresh attention on 21 October 2026 after a JPMorgan rating change to Overweight coincided with a roughly 4.8% move higher in pre market trading.
The recent JPMorgan upgrade comes after a tougher few months for EchoStar, with the share price down 7.39% over the last day and 10.13% over the past month. However, a 1-year total shareholder return of 17.47% and a very large 3-year total shareholder return suggest longer-term momentum has been strong even as shorter-term sentiment has cooled.
Scan how EchoStar compares to other media and telecom plays bouncing on fresh catalysts with our hand picked 29 high quality undervalued stocks screener.
After a sharp pre market jump, a recent pullback, and a long run of strong multi year returns, the central question is whether EchoStar still offers more upside than downside at this price.
Most Popular Narrative: 33.3% Undervalued
Against the last close at $85.79, the most followed EchoStar narrative points to a fair value of $128.67, which implies a wide gap that this thesis tries to explain through spectrum, satellites and indirect SpaceX exposure.
EchoStar's investment in a unique wideband LEO direct-to-device satellite constellation, leveraging its global S-band and AWS-4 spectrum rights, positions it to address rapidly increasing global demand for ubiquitous connectivity across consumer, enterprise, government, and IoT applications, which may create new, high-margin wholesale revenue streams and influence long-term revenue trends.
See why 25 investors see EchoStar as 33% undervalued.
Result: Fair Value of $128.67 (UNDERVALUED)
Still, the EchoStar story depends heavily on resolving FCC spectrum questions and managing large, near-term debt and funding needs related to its LEO constellation plans.
Find out about the key risks to this EchoStar narrative.
Another View: EchoStar Looks Expensive On Sales
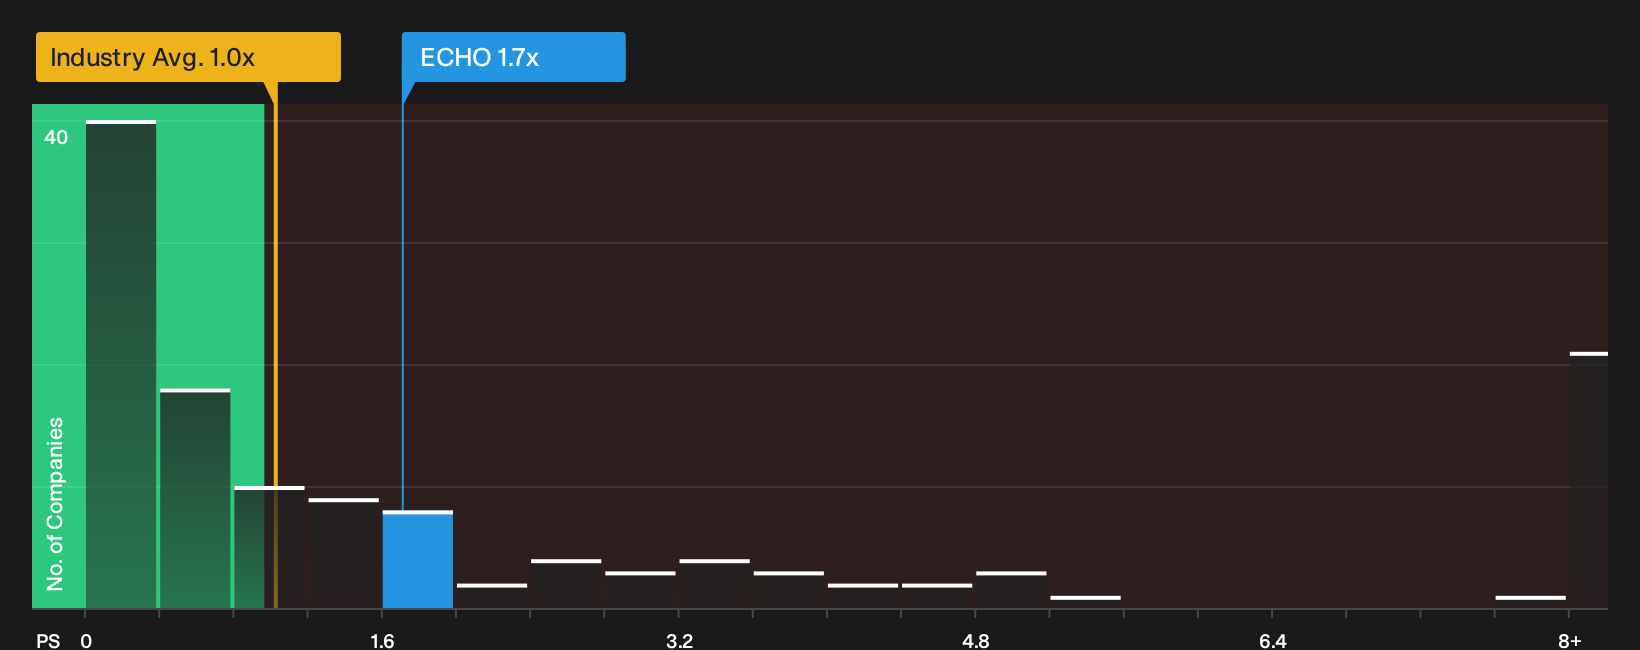
EchoStar may look appealing on a fair value of $128.67, yet the simple sales multiple tells a tougher story. The stock trades on a P/S of 1.7x, compared with 1.0x for the US Media industry and a fair ratio of 1.2x that the market could eventually move toward. That gap points to less room for error if growth or margins disappoint, so which signal do you put more weight on right now?
Investors who want to stress test this angle against hard numbers can review the valuation breakdown in detail with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
EchoStar clearly splits opinion, with strong long term returns on one side and valuation and balance sheet questions on the other. Move quickly, review the underlying data for yourself, and weigh both the upside and the risks through 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond EchoStar?
If EchoStar has you thinking about risk, reward, and timing, use that momentum and broaden your watchlist with a few targeted screeners right now.
- Target potential value upside by scanning a curated 29 high quality undervalued stocks that filters for quality businesses trading at what may be discounted prices.
- Rebalance toward resilience by reviewing a 30 resilient stocks with low risk scores that focuses on companies with steadier risk profiles and fewer financial red flags.
- Strengthen portfolio foundations by checking a list of solid balance sheet and fundamentals (26 results) that highlights businesses with healthier leverage and more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com