


PHP2Shell protection rollout puts Check Point Software Technologies in focus
Check Point Software Technologies (NasdaqGS:CHKP) introduced new security tools to the market after releasing Intrusion Prevention System and Web Application Firewall protections for the critical PHP2Shell remote code execution vulnerabilities.
Recent trading has been lively for Check Point Software Technologies, with a 7 day share price return of 15.35% and a 90 day move of 21.80% to US$159.03. However, the year to date share price return is down 12.15%; total shareholder return over 1 year is down 17.17%, while the 5 year total shareholder return of 32.97% points to a stronger longer run record and suggests current momentum is rebuilding after a softer patch.
Scan beyond Check Point Software Technologies and consider other cybersecurity players that respond quickly to zero day threats with our curated list of 30 resilient stocks with low risk scores.
After a 15% jump in a week yet a weaker run over the year, Check Point Software Technologies now raises a practical question. Do you lean into the rebound today, or wait for a cleaner entry on the numbers ahead?
Most Popular Narrative: 9% Overvalued
Against the last close at $159.03, the most followed narrative pegs fair value for Check Point Software Technologies at $145.83, so the recent rebound now sits above that line and puts more weight on whether the current security cycle delivers.
The main thing that has to go right is that the expanded sales force and new enterprise focused structure convert the stronger pipeline in AI centric, multi pillar security into sustained subscription and product demand as firewall appliances stabilise.
The broad go to market investment that includes hundreds of new sales hires, new enterprise focused coverage and more channel leverage is still underway. Management expects most of the impact to show in 2027, which could influence revenue scale and earnings power once the model beds down.
See why 37 investors see Check Point Software Technologies as 9% overvalued.
Result: Fair Value of $145.83 (OVERVALUED)
Still, if firewall demand stays weak and the revamped sales model continues to disrupt large deals, the narrative around Check Point Software Technologies could quickly look stretched.
Find out about the key risks to this Check Point Software Technologies narrative.
Another View: Check Point Software Technologies on earnings multiples
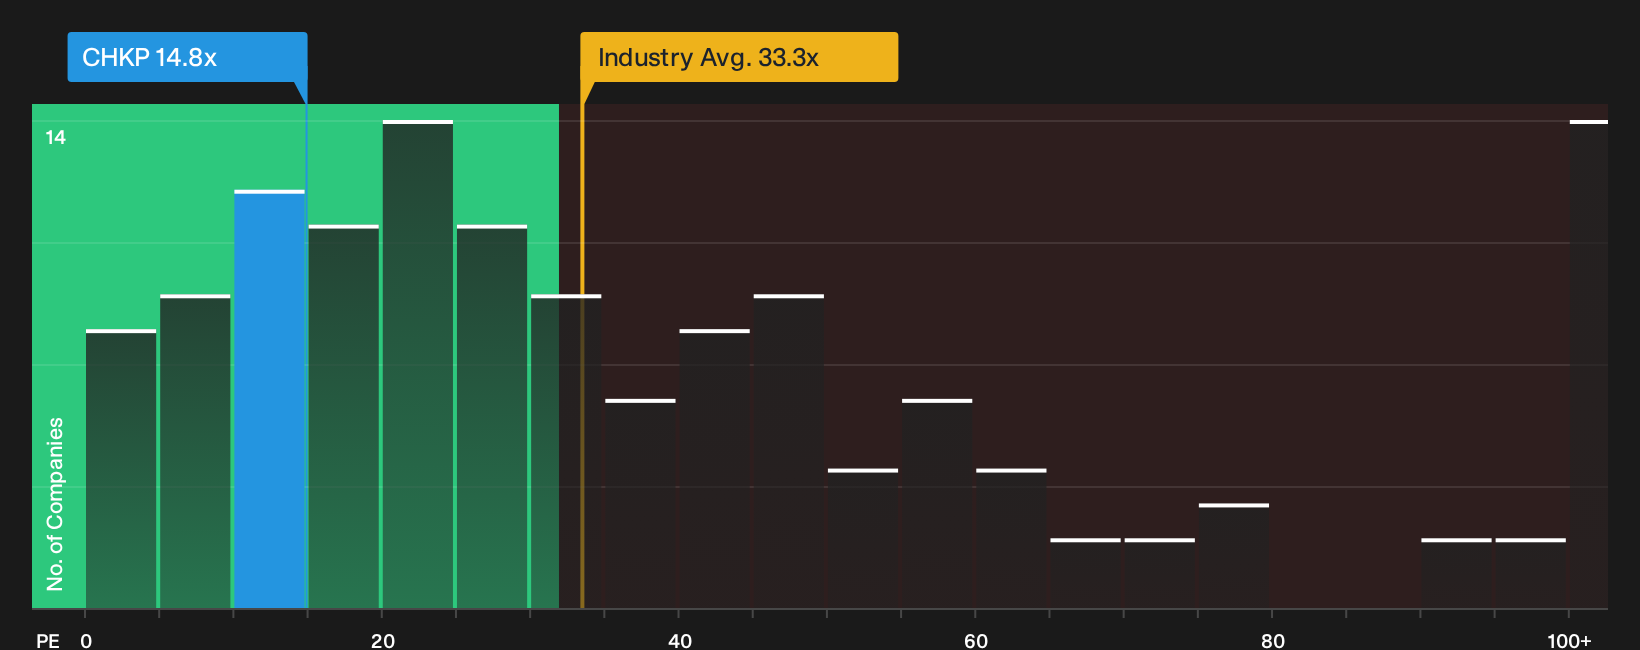
Analysts may see Check Point Software Technologies as 9% overvalued on a fair value of $145.83, yet the plain P/E math tells a different story. At 14.8x earnings versus 33.3x for the US Software group and 26x for peers, the gap is wide. The fair ratio of 21.9x points to a level the market could drift toward over time, which would change the risk and reward balance if sentiment shifts again. Where do you think that spread closes from here?
For a closer look at how this earnings based view stacks up across the sector, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Check Point Software Technologies is mixed, with clear risks on the table and some bright spots that still attract optimists. Act while the data is fresh and form your own stance by weighing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Check Point Software Technologies?
If Check Point Software Technologies has your attention, do not stop here. Consider broadening your watchlist now so you are prepared before the next move.
- Explore opportunities that aim to balance resilience and risk by reviewing the 30 resilient stocks with low risk scores.
- Look for potentially mispriced quality where fundamentals support the story by scanning the 29 high quality undervalued stocks.
- Build a portfolio with a focus on income potential by concentrating on companies in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com