


- Compañía de Minas Buenaventura updated its 2026 production guidance and reported Q3 and nine month output across gold, silver, lead, zinc and copper, outlining expected ranges such as 142,300 to 164,500 ounces of gold and 48,000 to 53,000 metric tons of copper.
- The detailed split between quarterly results and full year production targets gives investors a clearer read on how current output levels compare with Buenaventura’s 2026 volume ambitions across key metals.
- This article examines how Compañía de Minas Buenaventura's investment narrative is shaped by the new 2026 multi metal production guidance.
Compañía de Minas BuenaventuraA Investment Narrative Recap
To own Compañía de Minas BuenaventuraA, you need to believe the multi metal portfolio can turn planned volumes into consistent cash generation as San Gabriel, Yumpag and El Brocal ramp up. The updated 2026 guidance gives a clearer ceiling and floor for that story. On its own, the new ranges do not radically change the near term setup, but they sharpen expectations.
The biggest short term swing factor remains execution at key mines against that guidance while holding the cost line that has been pressured by inflation and contract escalators. The main risk is that high capex and rising unit costs absorb much of the operating cash flow, leaving less room to benefit from the planned throughput gains.
The fresh 2026 production guidance is the most relevant update for thinking about catalysts. Management now outlines gold of 142,300 to 164,500 ounces, silver of 13.9 to 15.3 million ounces and copper of 48,000 to 53,000 metric tons, with defined ranges for lead and zinc as well. Those figures frame what successful ramp up at San Gabriel and the other assets needs to look like.
With Q3 and nine month production now disclosed, you can track how Compañía de Minas BuenaventuraA is pacing against those 2026 targets mine by mine. Any sustained gap between actual volumes and these ranges, or signs that higher operating costs are eroding the benefit of reaching them, would cut directly into the core catalyst of turning higher throughput into durable margins and free cash flow.
Compañía de Minas BuenaventuraA's analyst narrative points to forecast revenue of US$2.3b and projected earnings of US$993.2 million by 2029, based on an assumed 1.7% yearly revenue growth rate and an earnings decline of about US$100 million from current earnings of US$1.1b.
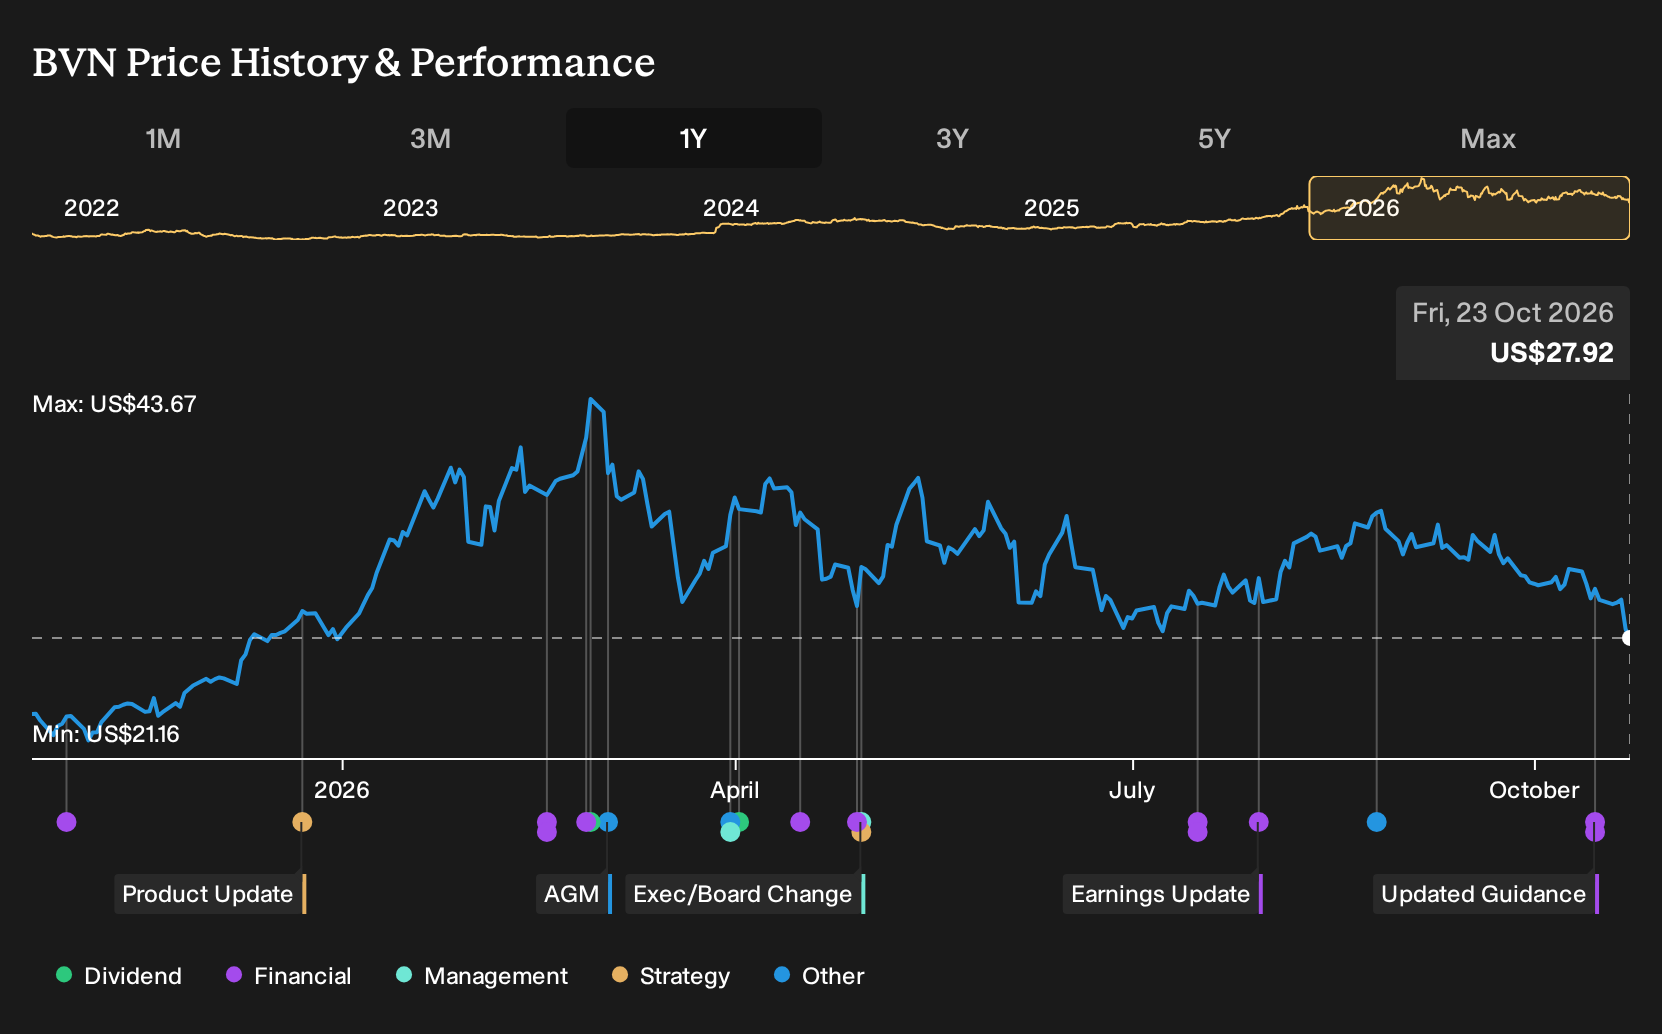
Uncover how Compañía de Minas BuenaventuraA's fair value indicates a 34% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are seeing one clear fork in the story for Compañía de Minas BuenaventuraA around San Gabriel ramp up risk. The most cautious analysts were already treating commissioning as a drag, even while still penciling in about US$2.2b of revenue and roughly US$1.0b of earnings by 2029. Those estimates came before this guidance update, so treat them as moving pieces. Use them as a reference point rather than a script, and compare several narratives before you decide how this new production plan fits your own view.
Explore 2 other Compañía de Minas BuenaventuraA fair value estimates, including one that suggests as much as 40% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Compañía de Minas BuenaventuraA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Compañía de Minas BuenaventuraA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Compañía de Minas BuenaventuraA's overall financial health at a glance.
Looking For More Ideas Beyond Compañía de Minas BuenaventuraA?
Once you have formed a view on Compañía de Minas BuenaventuraA, it can help to set it beside a few alternatives that fit different risk and return profiles. The Simply Wall St Screener lets you scan for other opportunities that match the type of balance sheet strength, income profile or valuation setup you want to focus on next.
- If capital preservation is a priority, start with companies that screen as more resilient and lower risk by reviewing the 30 resilient stocks with low risk scores in the tool.
- For investors who care most about financial strength, look for businesses with robust balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (26 results).
- Income focused readers can zero in on higher yielding opportunities by filtering for 6 dividend fortresses that might complement a metals exposure like Compañía de Minas BuenaventuraA.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com