


- NBT Bancorp is approaching its September 2026 earnings report with consensus EPS of $1.09, supported by revised estimates and a positive Earnings ESP. Fee-based activities in wealth, retirement, and insurance now represent a larger share of overall revenue.
- The growing role of these noninterest revenue streams suggests NBT Bancorp is becoming less dependent on lending income alone, which may influence how investors judge its earnings resilience through future rate and credit cycles.
- We will now look at how NBT Bancorp's rising fee income could reshape the investment narrative built around its regional lending.
NBT Bancorp Investment Narrative Recap
For an investor in NBT Bancorp, the core belief is that a more diversified fee engine in wealth, retirement, and insurance can support earnings through different rate and credit conditions. The key short term swing factor is execution on that fee mix and cost control around technology and integration work. The upcoming earnings print, with expectations around US$1.09 EPS, mainly tests whether that earnings quality story is intact.
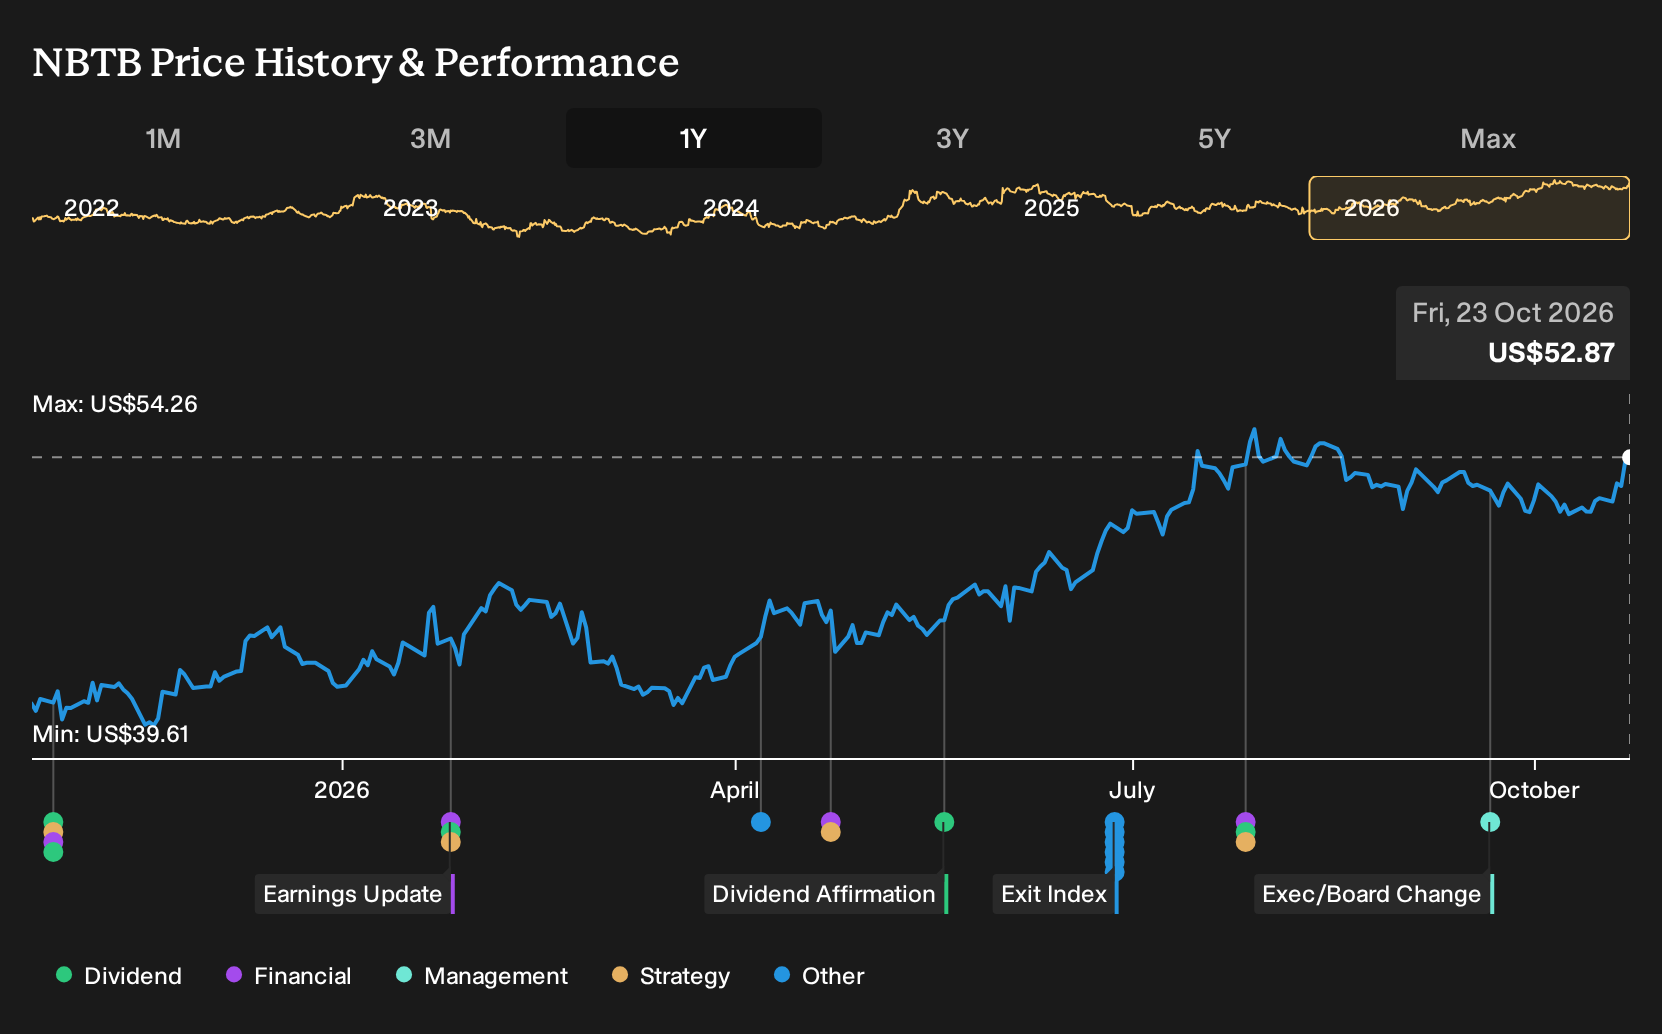
The biggest risk still sits in concentration. NBT Bancorp leans on upstate New York and surrounding regions, along with project linked activity such as Micron related demand. Any softer local economy or slower project ramp would likely feed through to both loan demand and service fees, which carries more weight now that the stock reflects stronger recent returns.
The earnings preview for September 2026 is the most relevant update. Consensus EPS of US$1.09, a recent 0.4% upward revision, and an Earnings ESP of +1.01% focus attention on whether fee income and loan demand are holding up at the same time that noninterest expenses are being watched closely.
If NBT Bancorp reports an earnings beat, the operational question is how that result is built. A print driven by retirement, wealth, and insurance fees alongside steady credit quality would generally support the narrative that the bank is less reliant on spread income alone. A result skewed toward higher operating costs or slower regional growth would highlight the existing risk list rather than introducing a new one.
NBT Bancorp Earnings Assumptions Through 2029
NBT Bancorp's narrative projects US$891.4 million revenue and US$269.0 million earnings by 2029. This implies 7.2% yearly revenue growth and an earnings increase of about US$54.8 million from US$214.2 million today.
Uncover why NBT Bancorp's fair value indicates a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$56.83 to US$86.32, which already shows how far opinions on NBT Bancorp can spread. When you set that against risks around regional concentration and digital execution, you have a clear reason to compare several independent viewpoints before committing fresh capital.
Explore another NBT Bancorp fair value estimate, including one that suggests as much as 63% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NBT Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NBT Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NBT Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond NBT Bancorp?
If the NBT Bancorp story has sharpened your thinking about earnings quality and risk, you can use that same lens across the wider market with the Simply Wall St Screener. Start from what matters most to you, whether that is balance sheet strength, income potential, or finding underappreciated opportunities, then filter for stocks that fit those priorities.
- For investors who want staying power over short term excitement, focus on companies with robust financial footing through the list of solid balance sheet and fundamentals (26 results).
- If your goal is to generate income while still keeping an eye on fundamentals, scan for reliable payers using the 6 dividend fortresses.
- When you are hunting for mispriced quality rather than chasing headlines, start with the 20 high quality undiscovered gems and see which underfollowed stocks meet your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com