


JBT Marel (JBTM) has set its next catalyst, with third quarter 2026 results scheduled for November 3 before the U.S. market opens, followed by an earnings call later that morning.
Recent trading has been choppy for JBT Marel, with the share price down 4.14% over the past month and 20.82% over 90 days, and year to date it has fallen 27.89%, while the 3 year total shareholder return of 9.59% contrasts with a 16.34% decline over 12 months, which points to fading momentum in the near term after earlier gains.
Scan how other industrials are setting up into earnings season by reviewing our hand picked list of solid balance sheet and fundamentals (26 results) alongside JBT Marel before November 3.
JBT Marel has dropped sharply while analyst targets and intrinsic value estimates sit much higher. Is the recent slide a warning about those models, or does it indicate a potential gap in the current price?
Most Popular Narrative: 35% Undervalued
JBT Marel’s most followed narrative pegs fair value at $167.06 per share, well above the recent $108.59 close. This puts a spotlight on whether the earnings story can eventually close that gap.
The JBT Marel merger is already realizing synergy benefits, and management’s plan for about US$150m of run rate cost synergies by the end of 2027 plus footprint optimization savings of US$25m to US$30m a year by 2028 directly targets higher net margins and supports the path toward the 20% adjusted EBITDA margin objective.
Expansion in aftermarket, service and refurbishment revenue from a large installed base of roughly 200,000 key machines, together with a plan to lift aftermarket wallet share from about 40% toward 50% to 60%, is expected to grow higher margin recurring revenue faster than equipment sales and support free cash flow relative to EBITDA.
See why 3 investors see JBT Marel as 35% undervalued.
Result: Fair Value of $167.06 (UNDERVALUED)
Still, JBT Marel’s narrative can crack if execution stumbles again on guidance, or if tariff related costs continue to squeeze margins and cash generation.
Find out about the key risks to this JBT Marel narrative.
Another View: What JBT Marel’s P/E Is Really Telling You
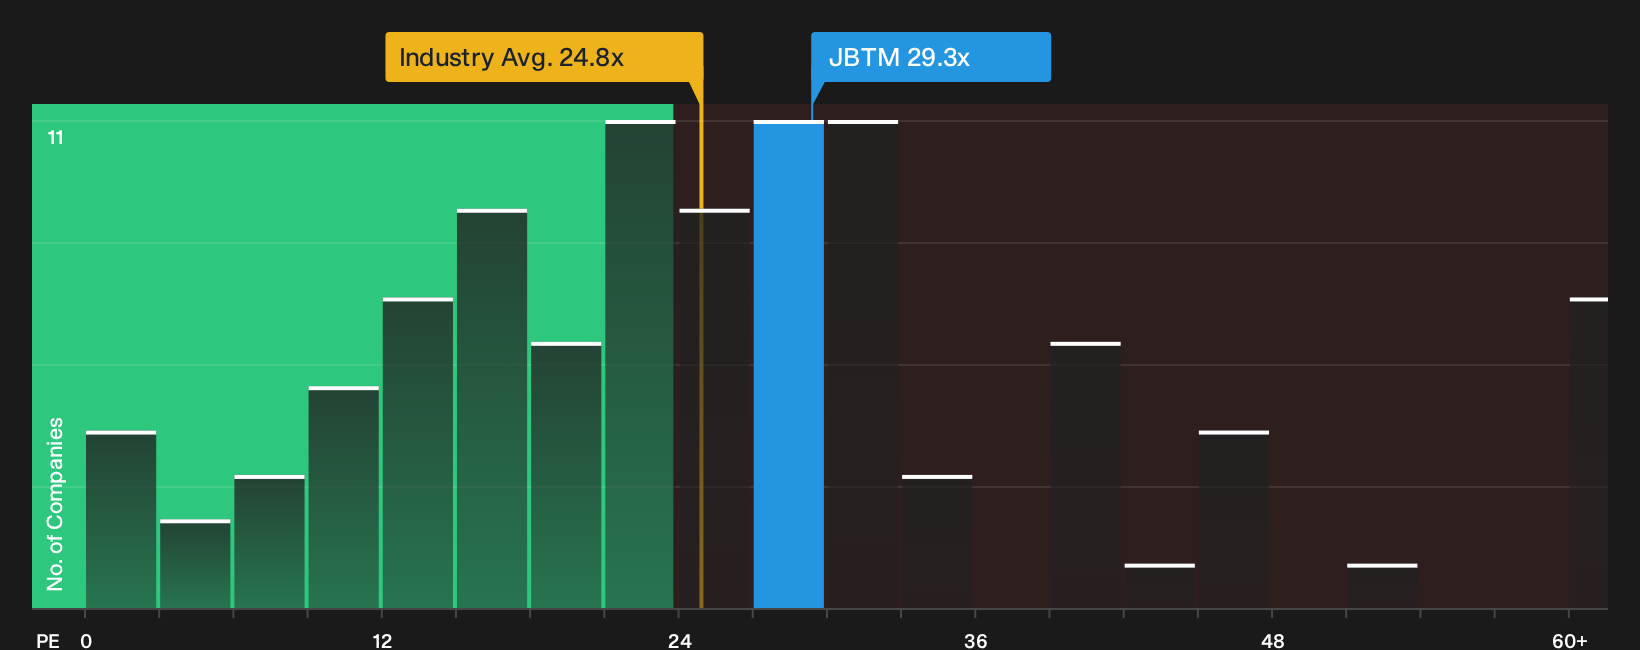
On simple P/E, JBT Marel looks expensive at 29.3x compared with the US Machinery sector at 24.8x. Against close peers on 56.7x and a fair ratio of 43.8x though, that premium shrinks and even flips into a relative discount. Is this a warning sign or a pricing gap worth tracking?
To stress test this second lens against your own expectations for earnings and risk, take a closer look at our valuation breakdown and where the fair ratio could move over time See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around JBT Marel can feel confusing, so move quickly, look through the numbers yourself, and weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond JBT Marel?
If you only focus on JBT Marel, you risk missing other setups that fit your style, so put a few more high quality ideas on your radar using the Simply Wall St screener.
- Target stronger downside protection by reviewing a curated 30 resilient stocks with low risk scores that can help you balance out more volatile positions.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks that match rigorous fundamentals filters instead of relying on broad market buzz.
- Build a steadier income stream by checking out 6 dividend fortresses that combine higher yields with financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com