


ATOSS Software came into Q3 2026 earnings with a rich P/E tag and a stock that had eased roughly 4% over the past month, trading at €87.3 into the release. Expectations were set for premium execution. The print did not flinch. Quarterly revenue reached €52.569m and basic earnings per share came in at €0.91, both aligned with a software business that leans heavily on recurring income.
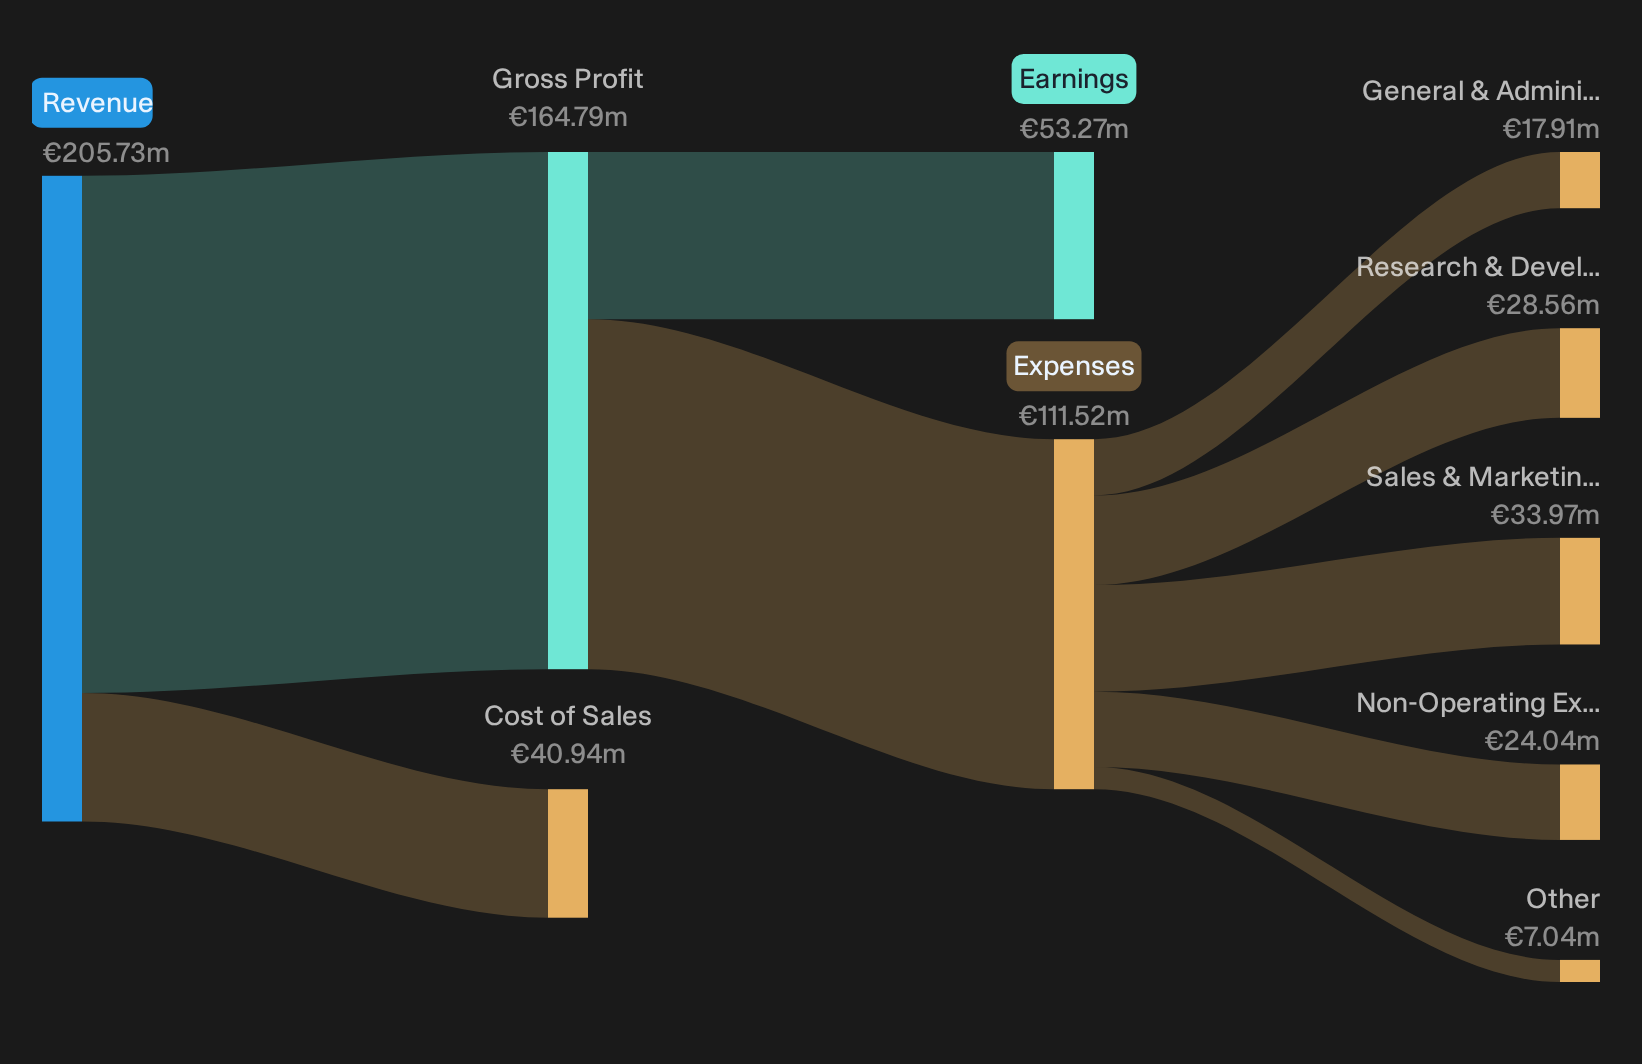
The market’s longer drift contrasts with the latest numbers. Earnings from continuing operations over the trailing twelve months stand at €53.274m, and investors now need to decide if that justifies paying up for ATOSS Software after this quarter.
Love the recurring earnings profile at ATOSS Software but unsure whether the rich P/E still leaves enough upside on the table? Compare it with a curated group of resilient premium businesses in our 195 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €52.569m vs. €47.24m (up about 11%)
- Net Income from Continuing Operations (Q3 2026 vs. Q3 2025): €14.404m vs. €12.336m (up about 17%)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.91 vs. €0.77 (up about 18%)
- Trailing 12-Month Revenue (Q3 2026 vs. Q3 2025): €205.733m vs. €184.063m (up about 12%)
Earnings only tell part of the story, and investors who care about what they are paying often pay closer attention to cash generated than reported profit lines.
When you look at ATOSS Software's cash flows and how they support the current share price, the stock could be a whopping 30% undervalued.
ATOSS cloud and AI thesis meets key milestones
Bulls argue that ATOSS Software’s growth engine is a bigger recurring base powered by cloud and AI heavy products.
"Rapid adoption of ATOSS Software cloud and subscription offerings, which accounted for 53% of total revenue in Q1 2026 and grew by 27% year-on-year, supports a larger recurring base that can increase revenue visibility and earnings quality."
Q3 results largely back that claim. Cloud and subscription now contribute 55% of turnover, while total ARR reached €157.1m with 17% growth and cloud ARR at €119.4m with 25% growth. EBIT margin at 40% in Q3 and upgraded full year guidance around 37% show the higher subscription mix already supporting profitability.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Bear case on ATOSS AI timing hits mixed reality
Bears worry that uneven AI appetite and slow cloud migrations will keep ATOSS Software’s growth engine stuck in a lower gear.
"While ATOSS Software is seeing growing interest in AI features, the fact that demand still differs by industry and is at an earlier stage in several sectors can slow the broad based adoption of new AI products. This may limit incremental cloud revenue growth versus current expectations."
Q3 shows that concern partly on display. Management still guides 2026 revenue to the low end of the range and flags weaker perpetual and consulting demand. At the same time, 25% cloud ARR growth, 17% total ARR expansion and a raised EBIT margin target to about 37% indicate that staggered AI and cloud take up is not yet denting the recurring model or profitability.
Hunt For Quiet Mispricings
ATOSS Software just showed how a strong recurring model can focus attention on valuation. The real opportunity could be spotting stocks that look mispriced before expectations reset.
- Company 1 - 35% below our estimate - expands dealer reach and folds in a large bedding acquisition to deepen retail coverage.
- Company 2 - 49% below our estimate - adds a major stake in a Latin American metals producer to scale zinc output and diversify mining cash flows.
- Company 3 - 36% below our estimate - grows fee pools as a broader advisory platform converts a record mandate pipeline into higher value transactions.
That is three of the list. See all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com