


Antofagasta (LSE:ANTO) just put fresh numbers and guidance on the table, pairing its third quarter copper sales and production update with reaffirmed 2026 targets and a new 2027 output range that investors can measure.
Despite reaffirmed guidance, Antofagasta’s share price has been under pressure, with a 30-day share price return down 18.63% and a 7-day return down 10.35%. At the same time, the 1-year total shareholder return of 15.62% and multi-year gains suggest longer term momentum that short term traders are reassessing as fresh production data and Chilean regulatory headlines reset expectations for risk and growth.
Surface other copper‑linked opportunities by scanning our hand picked 16 top copper producer stocks, which could benefit differently as production guidance, regulation and pricing pressures play out.Antofagasta looks like a solid copper producer on the numbers, yet the share price has just taken a sharp hit. Is that quality now on offer at a fair valuation, or is it already fully reflected?
Most Popular Narrative: 20% Undervalued
Antofagasta closed at £30.48 while the most widely followed narrative pins fair value nearer £38.06. That gap frames the current share price slide as a valuation query rather than a simple reaction to short term headlines.
Antofagasta's ongoing brownfield expansions at Centinela and Los Pelambres (including new concentrator, water system upgrades, and pipeline replacements) are on track to increase copper production by approximately 30% upon completion. This is expected to support higher future revenues and operating leverage.
See why 20 investors see Antofagasta as 20% undervalued.
Result: Fair Value of £38.06 (UNDERVALUED)
Still, that narrative can crack if Chilean water scarcity or tougher environmental rules drive higher costs and delay key Antofagasta projects just as labor disputes resurface.
Find out about the key risks to this Antofagasta narrative.
Another View On Antofagasta’s Valuation
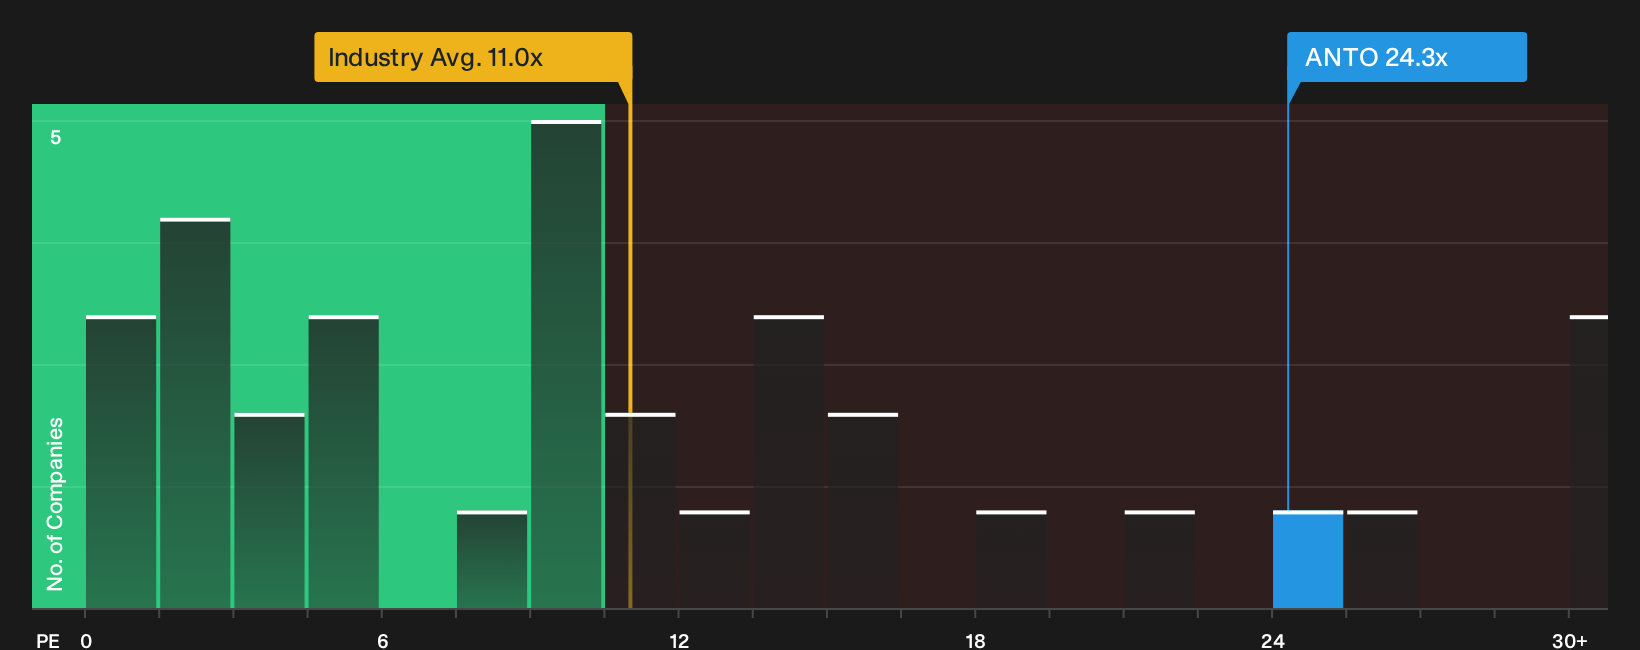
The narrative fair value points to Antofagasta being undervalued, yet the simple P/E story looks very different. The stock trades on 24.3x earnings compared with a fair ratio of 20x, the peer average of 12.5x and a UK Metals and Mining average of 11x.
That kind of valuation gap can compress quickly if sentiment or earnings expectations cool. The real question is whether this premium is a justified quality mark or a source of downside risk if the copper cycle or project delivery disappoints.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious tone here matches your own read on Antofagasta’s rewards and risks as the story evolves? Act quickly, pull up the underlying numbers and pressure test every assumption for yourself, starting with the 3 key rewards.
Looking for more investment ideas beyond Antofagasta?
If Antofagasta has sharpened your focus on copper and valuation, do not stop here. Cast a wider net and pressure test fresh opportunities before the crowd moves.
- Target potential mispricing by scanning companies flagged as 8 high quality undervalued stocks that pair quality fundamentals with prices that currently look compressed.
- Lock in income ideas by reviewing a hand picked set of 5 dividend fortresses that offer higher yields with an emphasis on durability.
- Reduce portfolio stress by filtering for 4 resilient stocks with low risk scores where balance sheets and risk scores help tilt the odds toward resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com