


Coverage of NeoGenomics (NEO) has picked up after a new Argus report highlighted the cancer testing specialist’s role in oncology diagnostics, prompting investors to reassess the stock’s recent share performance and business profile.
NeoGenomics has seen mixed momentum, with the share price at US$16.59 and a 90 day share price return of 19.44% alongside a softer 30 day move that is down 9.64% as investors digest earlier gains and fresh coverage such as the Argus report.
Scan how NeoGenomics compares with other cancer and healthcare testing players by reviewing the hand picked 34 healthcare AI stocks that harness data and diagnostics in different ways.
The question now is simple. After NeoGenomics’ sharp 1 year climb and recent pullback, does the current valuation leave meaningful upside ahead, or has most of the easy money already been made?
Most Popular Narrative: 22% Undervalued
At a last close of $16.59 versus a narrative fair value of $21.15, the current reading on NeoGenomics suggests the share price trails the scenario analysts are using to justify that higher figure, with the gap hinging on how new products and efficiency efforts play out.
The commercial launch of PanTracer, a comprehensive liquid biopsy panel for therapy selection, is set to enhance NeoGenomics' competitiveness and capture greater share in the rapidly growing NGS and liquid biopsy segment, supporting revenue acceleration and higher average unit prices (AUP) through 2025 and beyond. Ongoing demographic shifts, including an aging population and higher cancer incidence, continue to expand the overall addressable market for NeoGenomics' oncology diagnostics, translating into sustained test volume growth and providing a visible multi-year tailwind for top-line revenue.
See why 6 investors see NeoGenomics as 22% undervalued.
Result: Fair Value of $21.15 (UNDERVALUED)
Still, the bullish NeoGenomics narrative depends on pharma demand stabilising and competitors not squeezing pricing. Setbacks on either front could quickly weaken that thesis.
Find out about the key risks to this NeoGenomics narrative.
Another View: NeoGenomics Looks Expensive On Sales
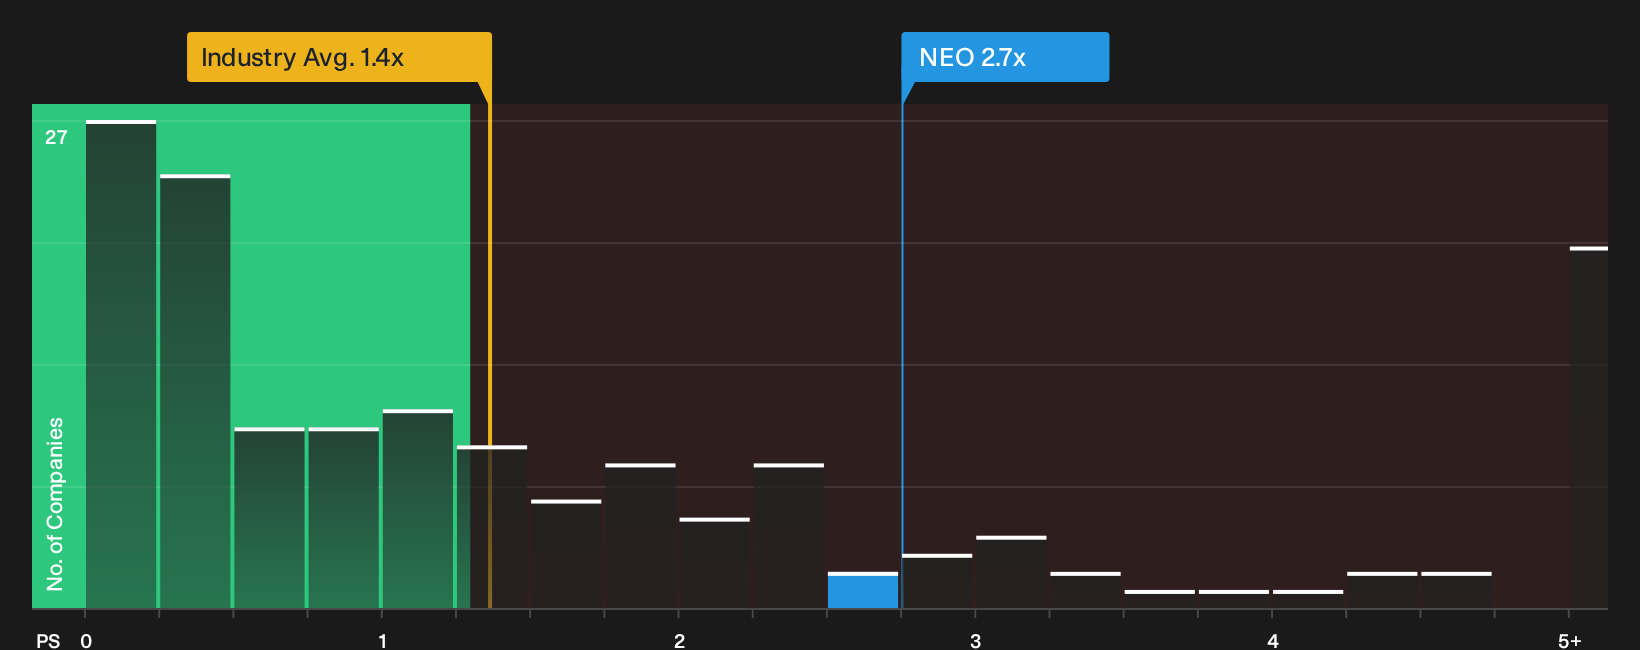
There is a different message when you shift away from the NeoGenomics fair value narrative and look at simple sales multiples. The stock trades on a P/S of 2.8x, roughly double both the US Healthcare sector average of 1.4x and the peer average of 1.4x. By comparison, the fair ratio sits closer to 1.5x.
That gap suggests investors are already paying a premium for future execution, even as NeoGenomics remains loss making. The key question is whether you are comfortable underwriting that richer multiple while the path to sustained profitability is still uncertain.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around NeoGenomics can be exciting on paper, but the real edge comes from stress testing the numbers yourself and deciding quickly what you think the risk reward trade off looks like, starting with the 2 important warning signs.
Looking for more investment ideas beyond NeoGenomics?
If NeoGenomics has sharpened your thinking, do not stop there. Broaden your watchlist and pressure test your thesis against fresh ideas surfaced by the Simply Wall St Screener.
- Target resilience first by checking companies with sturdy finances and low leverage in the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by scanning the 27 high quality undervalued stocks that combine quality fundamentals with more modest market expectations.
- Stack potential income on top of price return ideas by reviewing the 5 dividend fortresses that currently offer higher yield profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com