


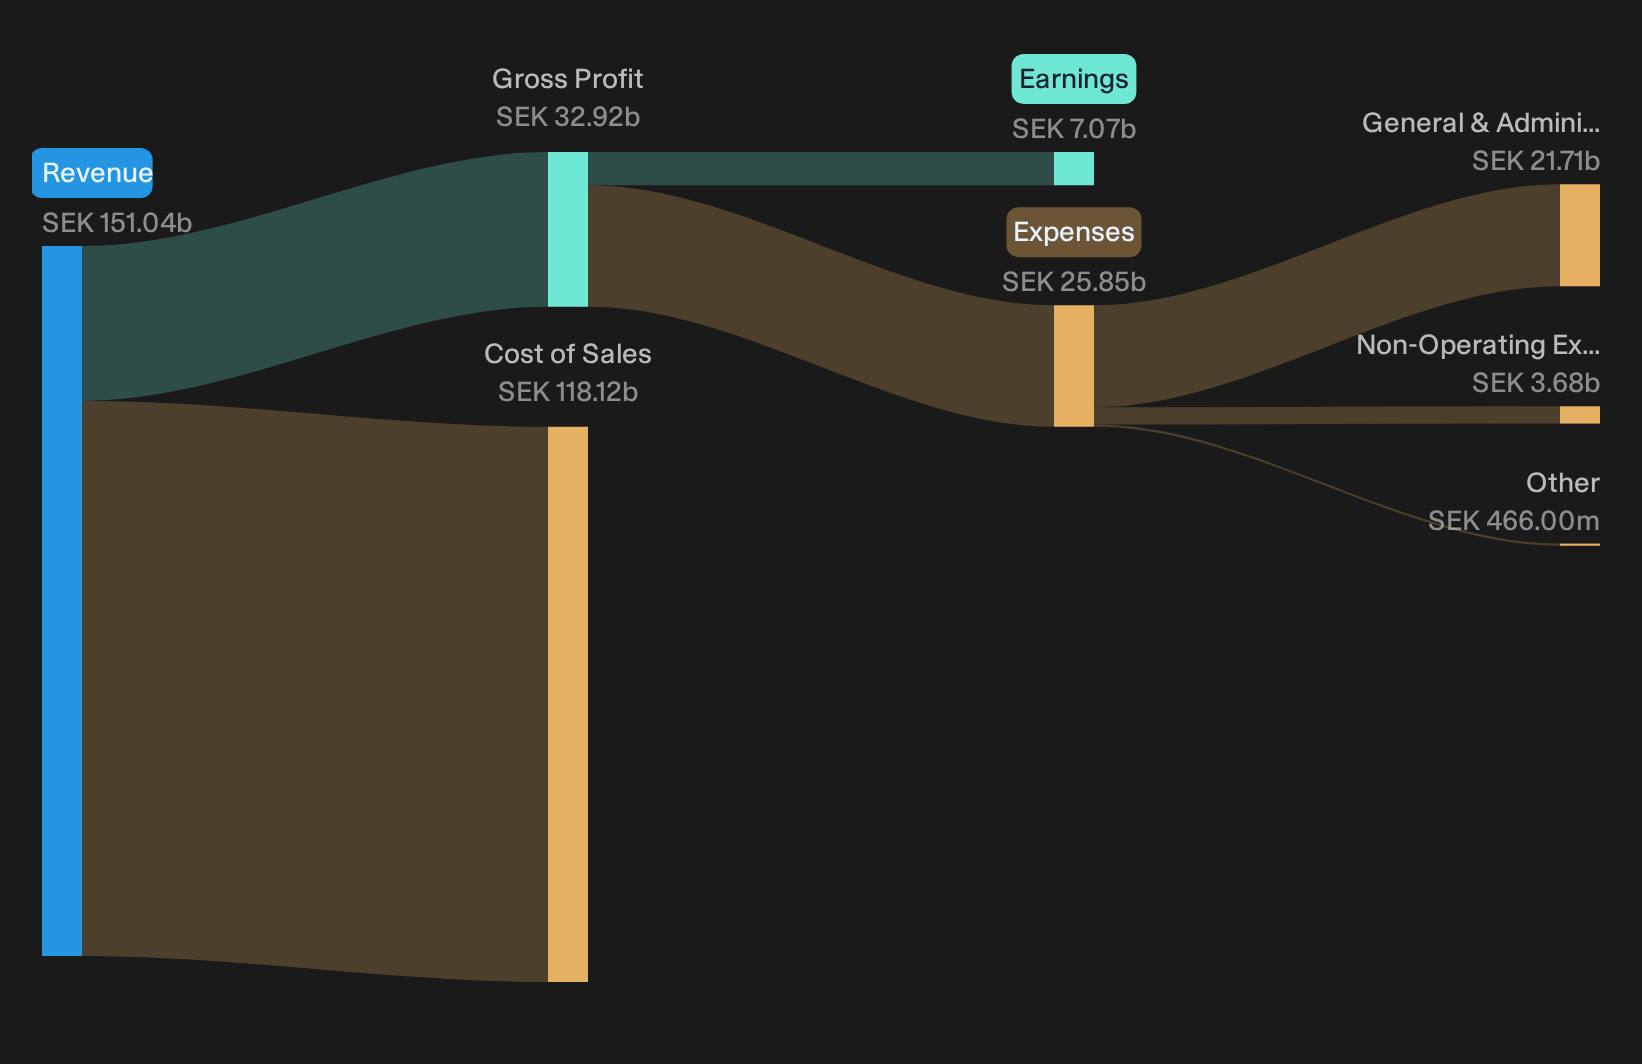
Securitas reported a solid Q3 2026, yet the share closed at SEK 156.50 after a weak week for the stock. The headline result is straightforward: earnings per share reached SEK 3.68 and net income was SEK 2,109m, both consistent with a business that continues to grind higher in a slow growth security market.
The key issue is sentiment. Investors have been wary despite a P/E of 12.7x and a reported net profit margin of 4.7%. Today’s muted reaction appears more like fatigue than a clear verdict on the underlying profitability trend.
Love that Securitas is still printing earnings but concerned that a 12.7x P/E and a 4.7% net margin may not be enough compensation for the sentiment risk right now? Line this result up against 221 resilient stocks with low risk scores to see how more resilient profiles compare.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): 38,566m SEK vs 38,521m SEK (broadly flat, slight uptick)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): 2,109m SEK vs 625m SEK (very large improvement)
- Basic EPS (Q3 2026 vs Q3 2025): 3.68 SEK vs 1.09 SEK (very large improvement)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 4.7% vs 3.2% (higher profitability ratio)
Securitas kept guidance but quietly raised its EPS ambition. Ask Charlie what’s behind Securitas’ new 10% EPS growth target.
Securitas Bull Case Hangs On Tech Mix Milestones
The bullish script argues that Securitas can lean on higher margin, tech heavy contracts to lift earnings quality over time.
"The rapid expansion of Securitas Global Clients business, now around 20% of group sales with a growing contribution from data centers approaching a high single digit to double digit share of group revenue, gives the company room to reweight toward complex global contracts that can support higher blended margins and more resilient earnings."
Q3 results give that view some hard backing. Technology & Solutions reached 35% of sales, real sales in that unit grew 6%, and North America plus Ibero America reported record installation orders and backlog. Aviation and contract pruning still weigh on parts of Europe, yet the mix shift pillar of the bullish story is clearly progressing.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Securitas Bear Case: Contract Fragility Still Bites
The bearish worry centers on whether Securitas can really lean on higher value contracts when parts of that book look fragile.
"Although Securitas is repositioning toward intelligence led, AI enabled services through units such as the risk management businesses and digital portals, the loss of a very large temporary contract in this area at the end of 2025 exposes how concentrated and fragile parts of this franchise can be."
Q3 shows that concern has not fully cleared. North America growth was held back by a terminated temporary contract and some Solutions terminations in Europe. At the same time, record T&S orders and a 35% sales share indicate the technology pivot is still drawing demand despite these setbacks.
Spot Hidden Earnings Stories
Securitas recently posted a steady report that did not fully reassure investors. The real opportunity is finding businesses that could be undervalued before sentiment aligns with their fundamentals.
- Company 1 - 33% below our estimate - converts a sizeable committed contract book and inquiry pipeline into higher value project work.
- Company 2 - 31% below our estimate - builds an annuity style services platform where long term infrastructure contracts and cash generation support disciplined acquisitions.
- Company 3 - 39% below our estimate - shifts its portfolio toward recurring, higher margin consumables and infection control tools for critical care and bioprocessing workflows.
Those are three of them. See every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com