


Dorchester Minerals distribution cut puts income focus front and center
Dorchester Minerals (DMLP) has put income front in investors’ minds after announcing a third quarter 2026 cash distribution of $0.882297 per common unit, identified by the partnership as a lower quarterly payout.
The distribution decision lands after a strong run in Dorchester Minerals’ units, with a 30 day share price return of 5.26% and a 90 day gain of 10.26% into the latest close at $30.64.
Over a longer stretch, the partnership has delivered a 31.78% year to date share price return, while total shareholder return over the past year is 36.8% and 5 year total shareholder return is 174.62%. This points to momentum that has been building rather than fading as income expectations reset around the lower payout.
Contrast Dorchester Minerals’ reset payout with a curated group of income-focused opportunities by checking the 5 dividend fortresses, which may offer alternative ways to target distribution strength.
Dorchester Minerals has already put up strong total returns into this distribution cut, so the real question now is whether most of the upside is already banked or if valuation still leaves meaningful room ahead.
Preferred P/E of 17.8x for Dorchester Minerals: Is it justified?
Dorchester Minerals is carrying a P/E multiple of 17.8x while trading at $30.64, which screens as expensive against both its direct peers and the wider US Oil and Gas group.
The P/E ratio compares what investors are paying for each dollar of current earnings. For a royalty focused partnership like Dorchester Minerals, that figure often reflects how stable the profit pool looks, how resilient the payout appears, and how investors weigh commodity exposure without the heavy capital spending that producers face.
Earnings contracted by 1.5% per year over the past 5 years, even though profit growth over the last 12 months of 8.6% outpaced that longer trend. That mix of a modest recent improvement and a weaker multi year record sits alongside high quality earnings, a 45.3% net margin, and a strong 28.8% Return on Equity. This may help explain why the market is willing to pay a richer multiple even as the distribution is being reset.
Compared to the peer average P/E of 14.6x and the broader US Oil and Gas industry at 12.3x, Dorchester Minerals is priced at a clear premium. The market is paying more per dollar of earnings than it does for many sector alternatives, which points to expectations around the partnership’s royalty model and cash flow profile that go beyond the industry norm.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 17.8x (OVERVALUED)
Still, the investment case for Dorchester Minerals can be knocked off course by weaker commodity pricing or by any sustained hit to US royalty production volumes.
Find out about the key risks to this Dorchester Minerals narrative.
Another view on Dorchester Minerals valuation
The rich 17.8x P/E paints Dorchester Minerals as expensive, yet the SWS DCF model points the other way. At a unit price of $30.64 against an estimated future cash flow value of $105.76, the units screen as heavily undervalued. That raises a simple question: Which lens do you trust more, near term earnings or long term cash generation?
For a closer look at how those long term cash flows are modeled, and what would need to change for that gap to close, Look into how the SWS DCF model arrives at its fair value.
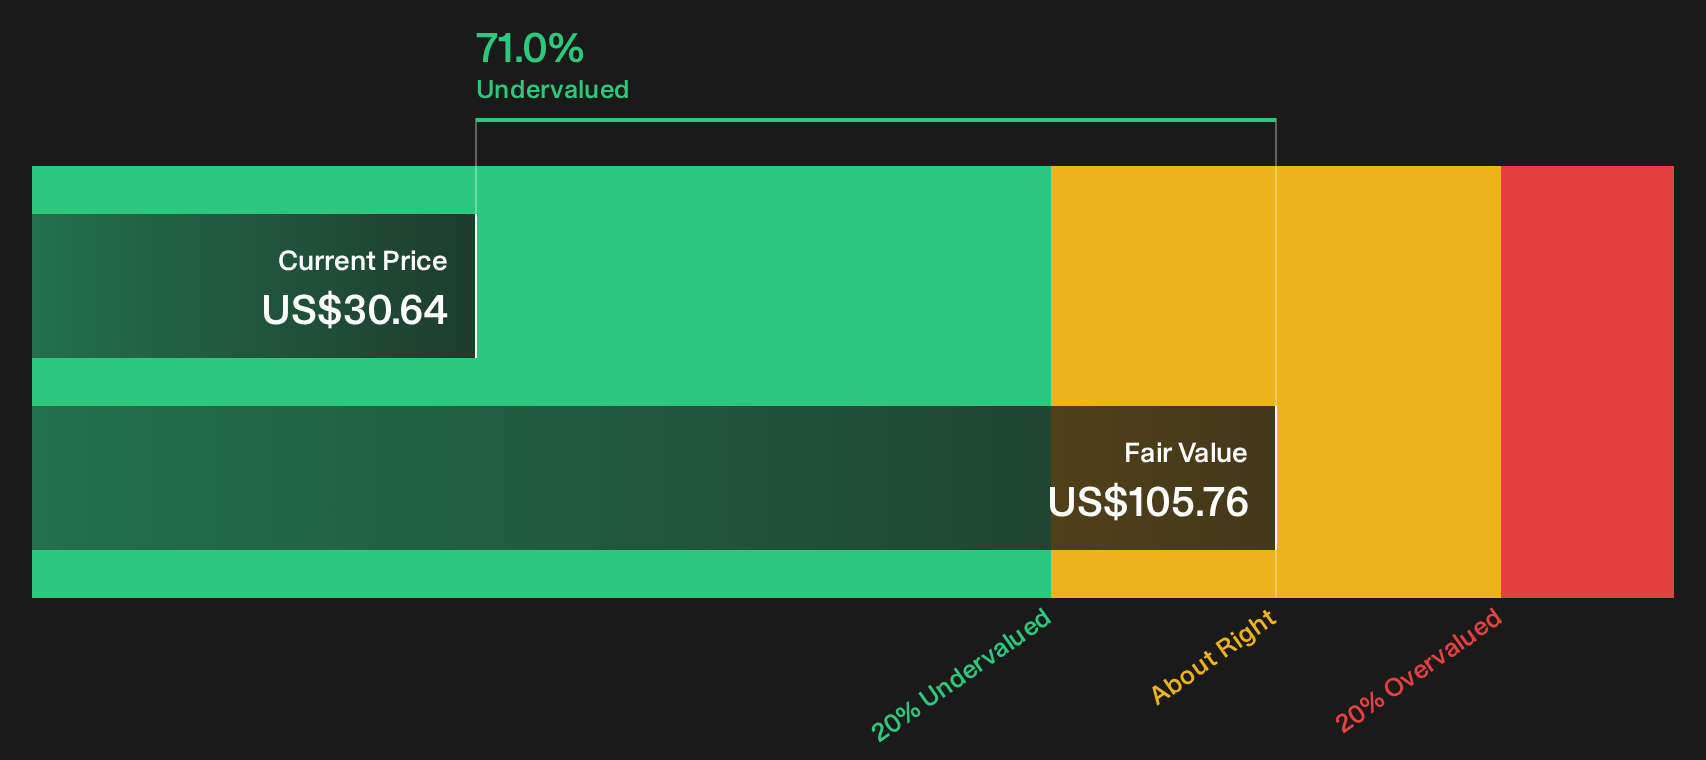
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dorchester Minerals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Dorchester Minerals so far. If the distribution cut and valuation gap raise as many questions as they answer, move quickly to pressure test the bullish and cautious arguments against the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Dorchester Minerals?
If Dorchester Minerals has sharpened your focus on income and valuation, now is the moment to widen your search before the next opportunity slips by.
- Target potential bargains that pair quality with price by scanning the 27 high quality undervalued stocks curated from fundamental data.
- Protect your downside first and hunt for stability by filtering for companies in the 30 resilient stocks with low risk scores that score well on resilience.
- Get ahead of the crowd by reviewing the 21 high quality undiscovered gems before attention and liquidity catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com