


AB Volvo came into Q3 2026 earnings under pressure, with the share price down about 13% over the past three months and 6% over the past month. The stock closed at SEK307.70 today, so the market had already marked expectations lower before the release.
The numbers told a different story. Basic earnings per share for the quarter landed at 5.29 SEK and net income reached SEK10,767m, supported by an adjusted operating margin of 12.3%. That profitability beat the mood implied by the recent slide and put the margin picture, rather than the share price move, at the center of this earnings season update.
Impressed by AB Volvo's earnings resilience but wary of recent share price pressure and margin risk. Compare those results with list of solid balance sheet and fundamentals stocks (204 results)
Q3 2026 Earnings Summary
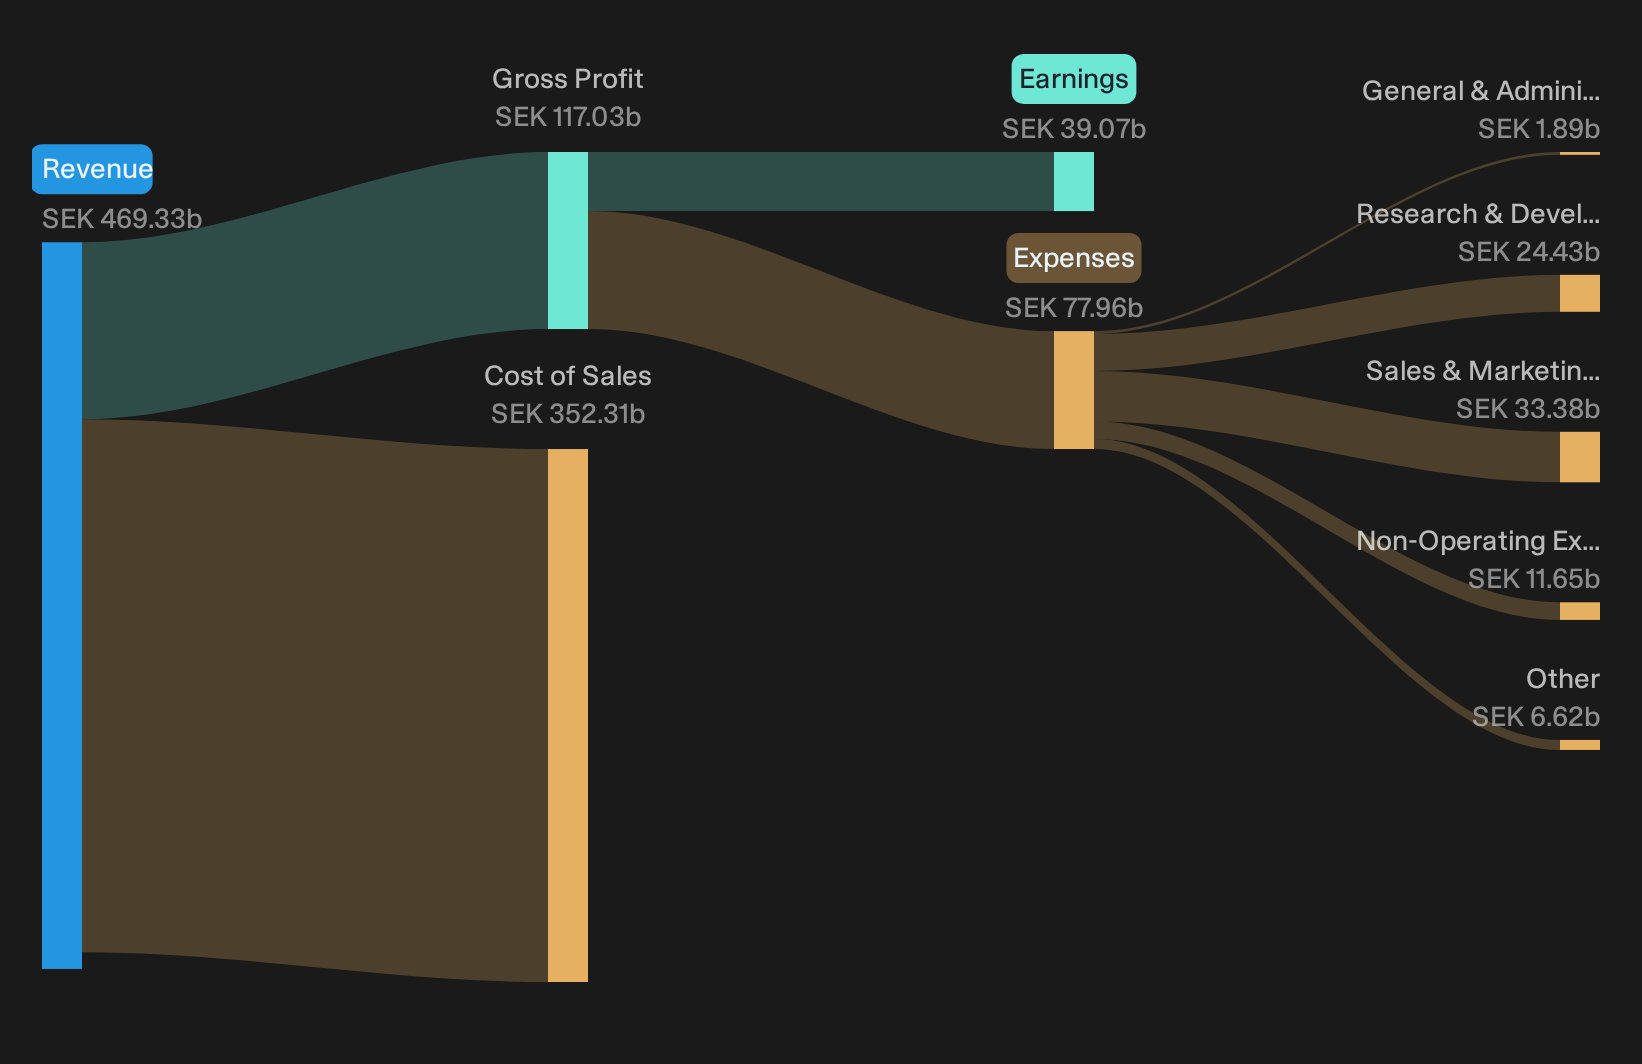
- Revenue (Q3 2026 vs Q3 2025): 119,525 million SEK vs. 110,692 million SEK (up about 8%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): 10,767 million SEK vs. 7,540 million SEK (up about 43%)
- Basic EPS (Q3 2026 vs Q3 2025): 5.29 SEK vs. 3.71 SEK (up about 43%)
- Adjusted Operating Margin (Q3 2026 vs Q3 2025): 12.3% vs. 7.6% reported net margin on a trailing 12 month basis (indicating higher quarterly profitability than the trailing margin benchmark)
Volvo Penta just tied a third of its order book to data centers. Ask Charlie what Volvo’s big AI data‑center bet really means.
AB Volvo’s Services And Autonomy Story Meets Hard Numbers
The bullish view hinges on AB Volvo turning connected fleets and autonomy into a richer stream of recurring income rather than just selling more metal.
"AB Volvo is shifting more of its truck and equipment base onto contracts that bundle uptime, over the air software and predictive maintenance."
Q3 shows that ambition translating into actual milestones. Services grew 5% organically and 12 month rolling service sales reached SEK128b. Management linked this to deeper contract penetration and higher fleet utilization. Volvo Penta’s data center related orders now represent 32% of its book with a 21.1% margin. Early autonomous trucking in Texas adds further proof that fee based transport is moving from slideware to live operations.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
AB Volvo: Strong Quarter, Electrification Strain Still Lurking
The bearish worry is that AB Volvo’s push into electrification and automation risks underused assets and future writedowns.
"The company is increasingly exposed to intensifying global regulation and carbon taxation on internal combustion engines, while progress in the societal shift towards zero-emission fleets has been slower than expected, resulting in significant one-off impairments and underutilized battery-electric assets; over the long term, this mismatch risks both asset writedowns and unanticipated capital expenditure, eroding net margins and return on invested capital."
Q3 margins at 12.3% and industrial net cash of SEK43.8b do not show fresh impairments or obvious asset strain. Heavy R&D capitalization and guided noncash margin drag in Q4 still point to the capital intensity the bear case worries about, even if the financial hit has not surfaced this quarter.
Find Fresh Disconnects Before They Close
AB Volvo just showed how earnings strength and share price pressure can move apart. The real opportunity is spotting stocks that could be undervalued before expectations reset.
- Company 1 - 18% below our estimate - builds a premium teahouse network as healthier drink preferences and a large membership base shape repeat purchases.
- Company 2 - 28% below our estimate - supplies liquid cooling and power systems that data centers need as AI hardware increases power density beyond air-based limits.
- Company 3 - 24% below our estimate - ties cloud infrastructure, workplace software and AI assistants into one ecosystem that enterprises use for expanding everyday AI workloads.
That is three of the list. See the full list of 194 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com