


British households face some of Europe’s highest energy costs this winter, which puts reliable cash payouts from solid dividend payers firmly back in focus. Regular income suddenly matters more when utility bills absorb a bigger slice of your budget. This article walks through three higher yielding UK dividend stocks from a quality screen that looks for yields above 3% that appear well covered, growing and relatively stable.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers where the income stream aims to be well covered, growing and relatively steady. However, if you want the standouts, these 5 dividend aristocrats stocks are the most outstanding.
Rathbones Group (LSE:RAT)
Overview: Rathbones Group is a long-established UK wealth and asset manager, using fee-based investment and planning services to support regular dividends.
Operations: Most revenue comes from Wealth Management at £875.5 million, with Asset Management contributing £86.2 million, largely generated in the United Kingdom.
Market Cap: £1.7b
For income-focused investors, Rathbones Group matters because its fee-based Wealth Management arm helps underpin a higher dividend yield that aims to be both repeatable and resilient through cycles.
"The completion of the Investec Wealth & Investment (IW&I) integration unlocks significant scale advantages and operational synergies, providing a tangible opportunity to improve operating margins. Management expects these efficiencies to result in a 28% margin by Q4 2026 (from 25.4%), with full synergy benefit (~£60m annualized) set to be realized by the end of 2025."
What really decides how reliable that dividend stream feels over time is one unresolved pressure on the cost base and fee mix.
That pressure point is exactly what makes the full narrative for Rathbones Group worth reading, as it unpacks where Rathbones Group could be accelerating and where costs may still be masking progress.

Man Group (LSE:EMG)
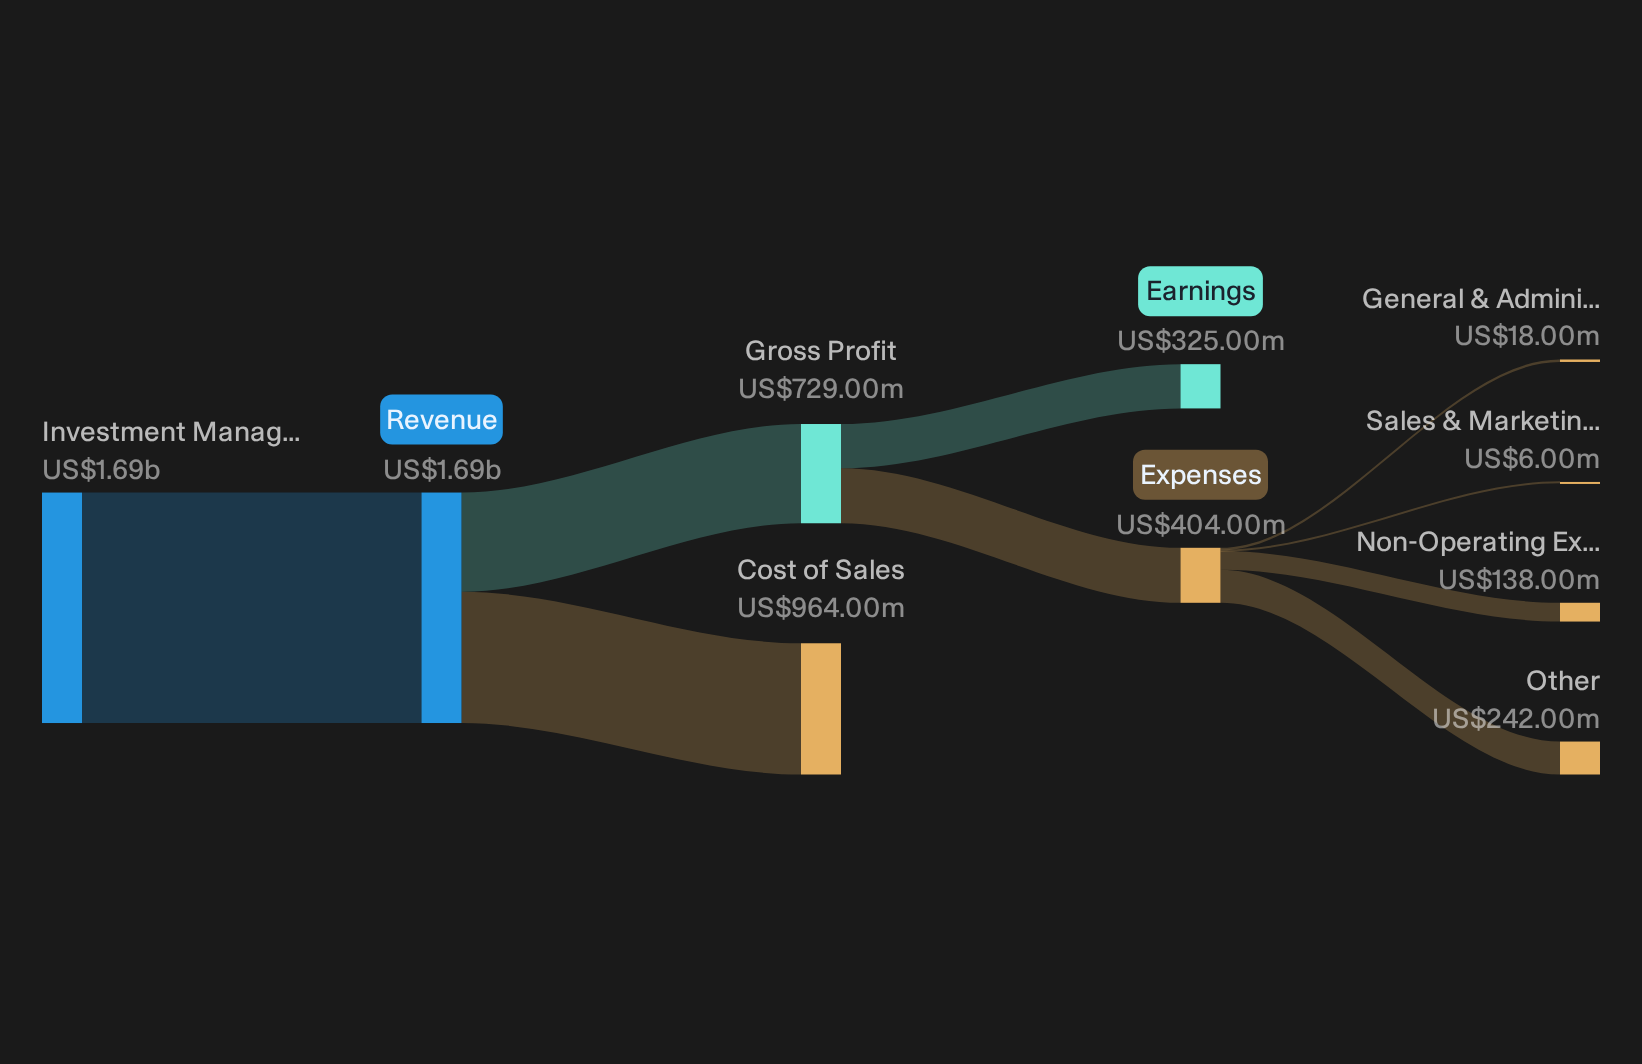
Overview: Man Group is a global investment manager that runs quantitative, alternative and long-only funds, using fee income to support regular and special dividends above 3%.
Operations: The business generates its revenue primarily from its Investment Management segment, which produced about $1.7b in fees and related income.
Market Cap: £3.5b
Man Group matters for this Dividend Powerhouses screen because its cash-generative fee model is directly linked to a policy of sharing surplus capital with investors through regular and special payouts.
"Robust global institutional demand for alternative and customized investment solutions continues to drive strong net inflows (e.g., record $17.6bn in H1 2025, well ahead of industry), positioning Man Group for sustained AUM and recurring fee income growth as institutions seek diversification in a low-yield and volatile market environment, positively impacting long-term revenue and earnings."
The real test for that income story is what happens if a single unseen pressure on fee margins and product mix shifts direction.
If that risk starts to bite, the full narrative for Man Group shows whether Man Group’s capital return engine is accelerating, stalling, or quietly being masked by headline fee growth.
Grafton Group (LSE:GFTU)
Overview: Grafton Group is a building-materials distributor and DIY retailer whose recurring trade and home-improvement sales help fund a covered, growing dividend.
Operations: Grafton Group generates about £1.13b from Ireland and £745.5 million from Great Britain, with additional revenue from Iberia and Northern Europe.
Market Cap: £1.9b
Grafton Group slots into the Dividend Powerhouses screen because its everyday building and DIY distribution activity throws off relatively steady cash flows that can support a 3%+ payout even when trading conditions are mixed.
"The company's entry into the fragmented Spanish HVAC market through the acquisition of Salvador Escoda provides significant organic growth opportunities, supported by plans to open 50-plus new branches over time, driving future revenue growth."
What matters next is how one unresolved squeeze on profitability shapes the balance between that dependable dividend stream and future expansion potential.
That trade off is exactly what the full narrative for Grafton Group unpacks, revealing how Grafton Group’s branch rollout, cash generation and risks are interacting rather than just headline revenue growth.

Seeking Alternatives Before The Crowd?
Fresh ideas tend to move first. Slow ideas can get caught. Consider using these screeners while the data is still relatively under the radar, before momentum potentially increases.
- Target companies with resilient payments and reliable cash flows by running a quick pass through the 5 dividend fortresses while yields still look appealing.
- Look for overlooked quality with strong balance sheets using the curated list of solid balance sheet and fundamentals (9 results) before others focus more closely on the underlying fundamentals.
- Explore the build-out of next-generation energy infrastructure by scanning the hand-picked 16 nuclear energy infrastructure stocks while sentiment around the theme is still taking shape.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com