


Hemlo Mining stock reacts to fresh production and sales update
Hemlo Mining (TSX:HMMC) has put fresh numbers on the table, releasing unaudited third quarter and nine month 2026 figures for gold production, gold sales, and ore processed that now anchor the latest share move.
The fresh production and sales update has arrived after a choppy few months for Hemlo Mining, with the 1 day share price return of 3.74% to CA$4.99 coming against a 30 day share price return that declined 28.51% and a year to date move that is only slightly lower. Momentum near term has been fading on those shorter term declines, although the very large 3 year total shareholder return of more than 12x still points to a stock where sentiment has shifted dramatically over a longer horizon as investors reassess both growth potential and risk around the Hemlo gold operation.
Scan how Hemlo Mining stacks up against other producers under pressure by reviewing a curated set of 35 elite gold producer stocks in similar parts of the cycle.
After a sharp pullback and a fresh set of production and sales figures, Hemlo Mining now presents a simple question: Does the current valuation still skew the risk reward in favour of new buyers?
Price-to-earnings of 64.9x for Hemlo Mining: Is it justified?
On simple headline metrics, Hemlo Mining looks expensive, with the stock trading on a P/E of 64.9x at a last close of CA$4.99, even as some other indicators point to value and a different story under the surface.
The P/E ratio compares what investors pay for each dollar of forecast earnings, and for a gold producer like Hemlo Mining it effectively reflects how much the market is willing to pay today for the future cash flows that mine can deliver.
HMMC is described as expensive against several anchors, with its 64.9x P/E above the estimated fair P/E of 36.6x, above the peer average P/E of 20.8x, and above the broader Canadian Metals and Mining industry average P/E of 14.1x. The current market price therefore implies a far richer earnings multiple than both sector peers and the level that regression work suggests the valuation could move toward.
Explore the SWS fair ratio for Hemlo Mining.
Result: Price-to-earnings of 64.9x (OVERVALUED)
Still, the story around Hemlo Mining can change quickly if production stumbles at the Hemlo gold mine or if cost pressures squeeze that CA$16.281 million net income base.
Find out about the key risks to this Hemlo Mining narrative.
Another view on Hemlo Mining’s value
That rich 64.9x P/E points one way, yet our DCF model points in the opposite direction, with a fair value estimate of CA$44.07 per share compared with the current CA$4.99. On that lens Hemlo Mining looks deeply undervalued, so which yardstick should carry more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
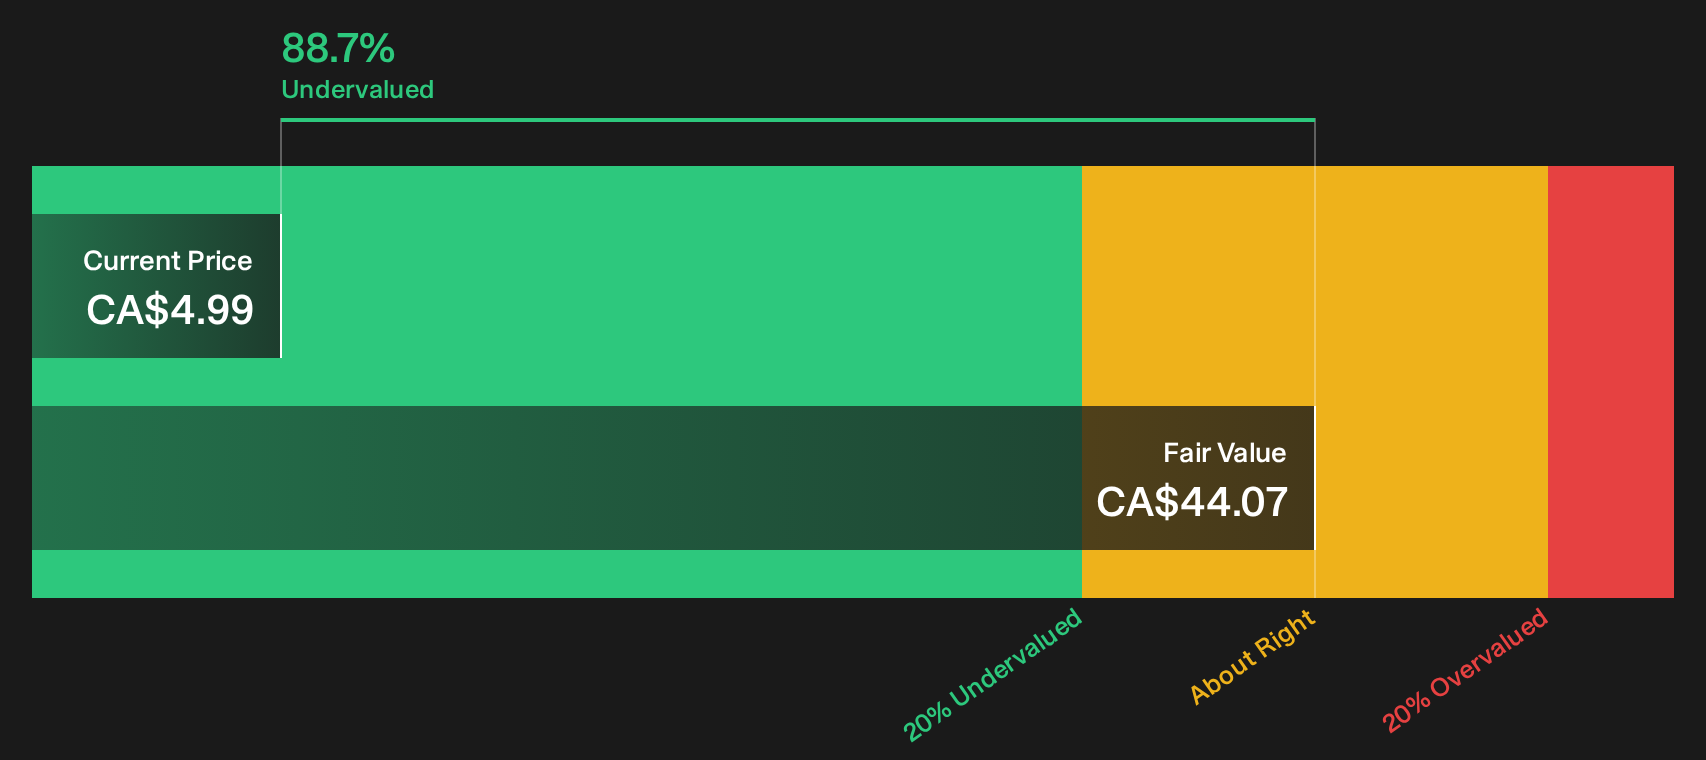
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hemlo Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Hemlo Mining is split, which means your edge comes from actually checking the numbers yourself and deciding where you land in that debate. To balance the concerns against the potential, go straight to the full breakdown of 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Hemlo Mining?
If Hemlo Mining has sharpened your focus on valuation and risk, consider broadening your watchlist with other ideas that match different goals and comfort levels.
- Target potential mispricings by scanning a curated pool of companies that screen as attractively priced using our 2 high quality undervalued stocks.
- Anchor your portfolio around stability and consistent payouts by reviewing a focused set of high yielding income opportunities in the 3 dividend fortresses.
- Reduce portfolio stress by concentrating on businesses that combine resilient finances with lower overall risk using the 8 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com