


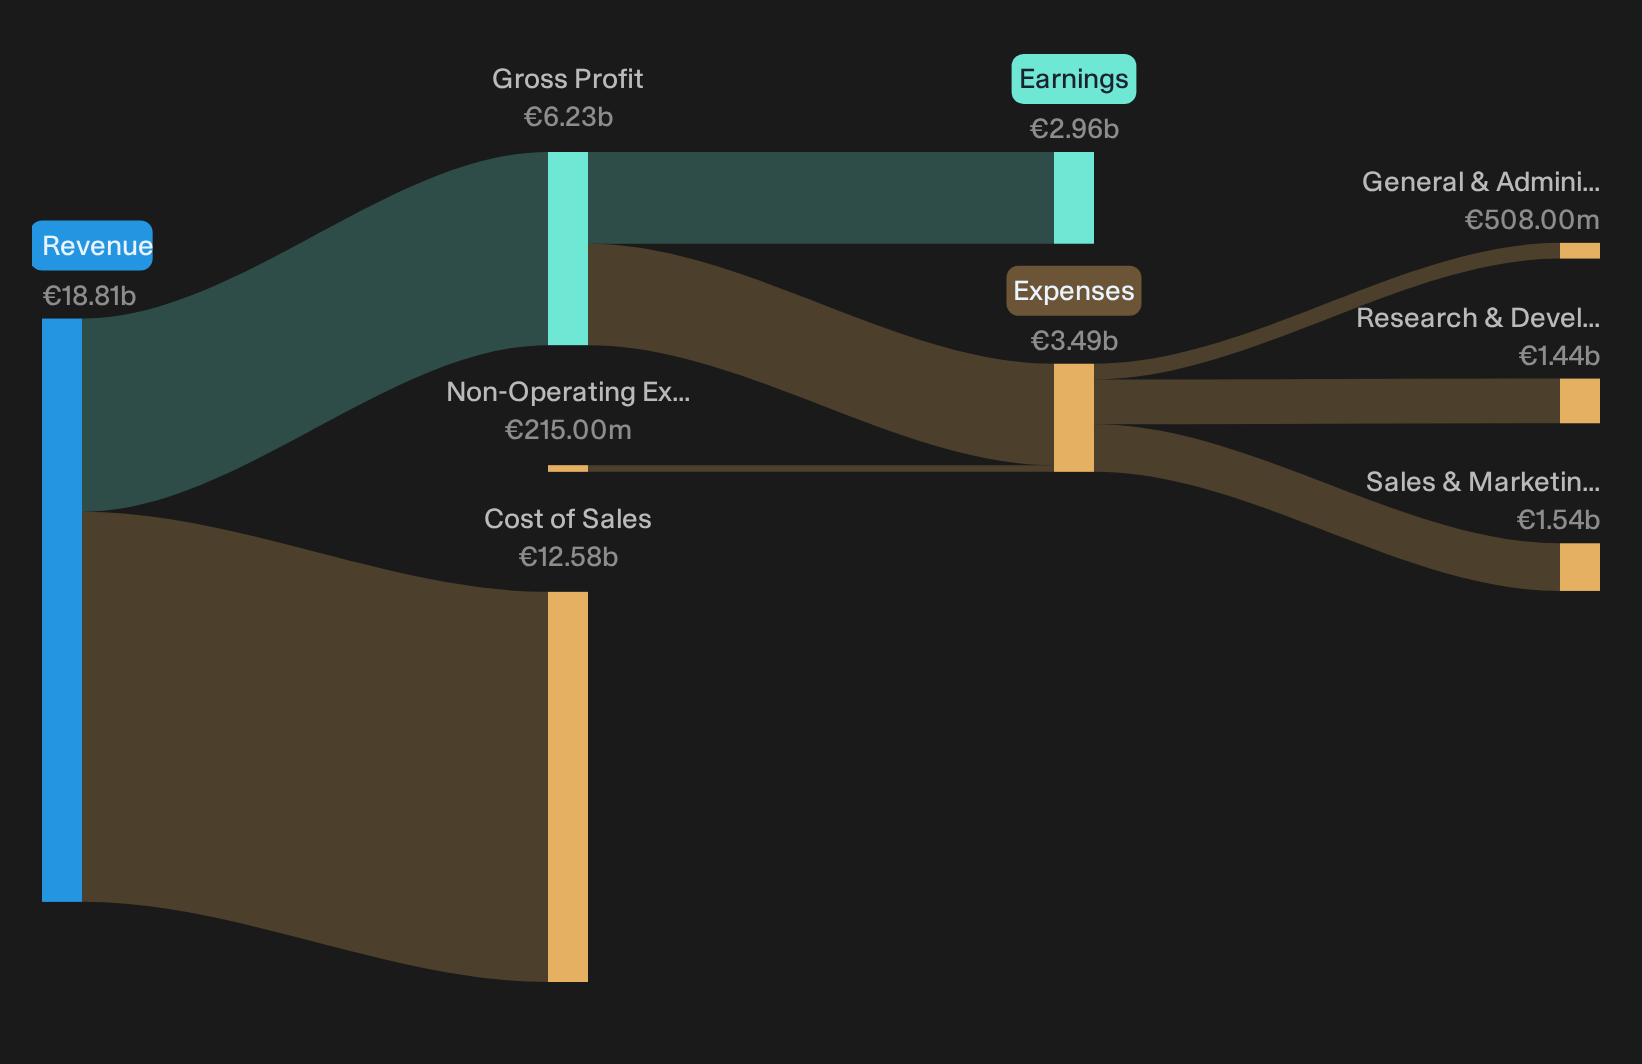
Spotify stock barely moved after its Q3 2026 report, edging up about 0.1% to roughly $584, yet the earnings story was anything but flat. The platform delivered around €5.0b in revenue and pushed operating income to roughly €672m, powered by a 33% gross margin that matters far more than today’s modest share price flicker.
In the short term, the reaction looks muted. Over a multi-year view, that expanding profitability, backed by €9.9b of cash and no financial debt, is likely to play a central role in how investors evaluate Spotify’s business model and its valuation from here.
Like the mix of rising profitability and a cash heavy balance sheet at Spotify but want a broader set of strong operators to compare it against? Check out our curated screener of companies with robust margins and net cash positions through the list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €4,969m vs €4,272m (up about 16%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): €518m vs €899m (down about 42%)
- Basic EPS (Q3 2026 vs Q3 2025): €2.52 vs €4.36 (down about 42%)
- Gross Margin (Q3 2026 vs Q3 2025): 33% vs about 31.6% (expanded by roughly 140 basis points year over year)
Spotify’s AI Monetisation Ambitions Meet First Real Tests
Spotify’s bullish story leans heavily on next level monetisation from AI and power users actually showing up in the numbers.
"The main thing that has to go right is that Spotify turns its growing multi vertical platform and AI products into sustained high margin monetization while maintaining healthy relationships with labels, artists and users, despite ongoing concerns about royalties, competition and generative content."
Q3 hits some of that milestone. Gross margin sits at 33% and operating income reaches about €672m, both supported by higher premium ARPU and Audiobooks+ now over US$100m in annual recurring revenue. AI remix tools are run on licensed deals with major rights holders, which supports the relationship side of the thesis.
One Narrative disagrees with today's price. → See where this Narrative says Spotify Technology should trade.
Spotify Bear Case: Costs Behaving, Conversion Still On Trial
Critics worry Spotify’s push into AI and richer products simply fattens the cost base more quickly than it lifts earnings.
"the roughly €200 million of extra AI related operating expenses concentrated in 2026 risk becoming embedded rather than temporary. This could slow the trajectory of operating margin and earnings improvement if future revenue does not keep pace."
Q3 margins undercut that fear in the near term. Gross margin reached 33% and operating income was about €672m alongside €735m of free cash flow and €9.9b of cash. Management also called Q3 the peak operating expense quarter. The stress point is elsewhere. Net income excluding extra items fell about 42%, so earnings progression is not yet matching the operating line.
Hunt Quiet Fundamental Shifts
Spotify Technology recently showed that a stronger income statement may not create a significant share price reaction. The focus here is on stocks that could be undervalued ahead of any market revaluation.
- Company 1 - 36% below our estimate - convert record wins in regulated manufacturing programs into sustained volume production and disciplined cash generation.
- Company 2 - 28% below our estimate - supply diagnostic systems and components that support utility and aerospace testing as grid modernization advances.
- Company 3 - 25% below our estimate - fill expanded photonics capacity with AI oriented data center optics and sophisticated packaging projects.
Those are three of them. See the full list of 27 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com