


Energy Transfer has delivered a powerful multi‑year run, and the question many unitholders are now circling is whether the current price still lines up with what its earnings can support. After that kind of climb, the issue is less about past performance and more about what the partnership’s income stream really justifies today.
- Over the past 5 years the stock has returned 210.6%, which puts a lot of weight on whether the underlying profits are strong enough to back that move.
- The twentieth consecutive increase in the quarterly cash distribution may support the case that Energy Transfer’s earnings base and cash generation can sustain higher payouts, which matters for how much investors are willing to pay for each dollar of income.
- There is a second opinion on Energy Transfer worth weighing. See what analysts think Energy Transfer's shares could be worth.
The stock's next move may depend on whether Energy Transfer's current earnings profile is enough to justify the price investors are paying today.
If you want a benchmark for this kind of income focused story, compare Energy Transfer with other 5 dividend fortresses.
Is Energy Transfer Still Cheap on Earnings?
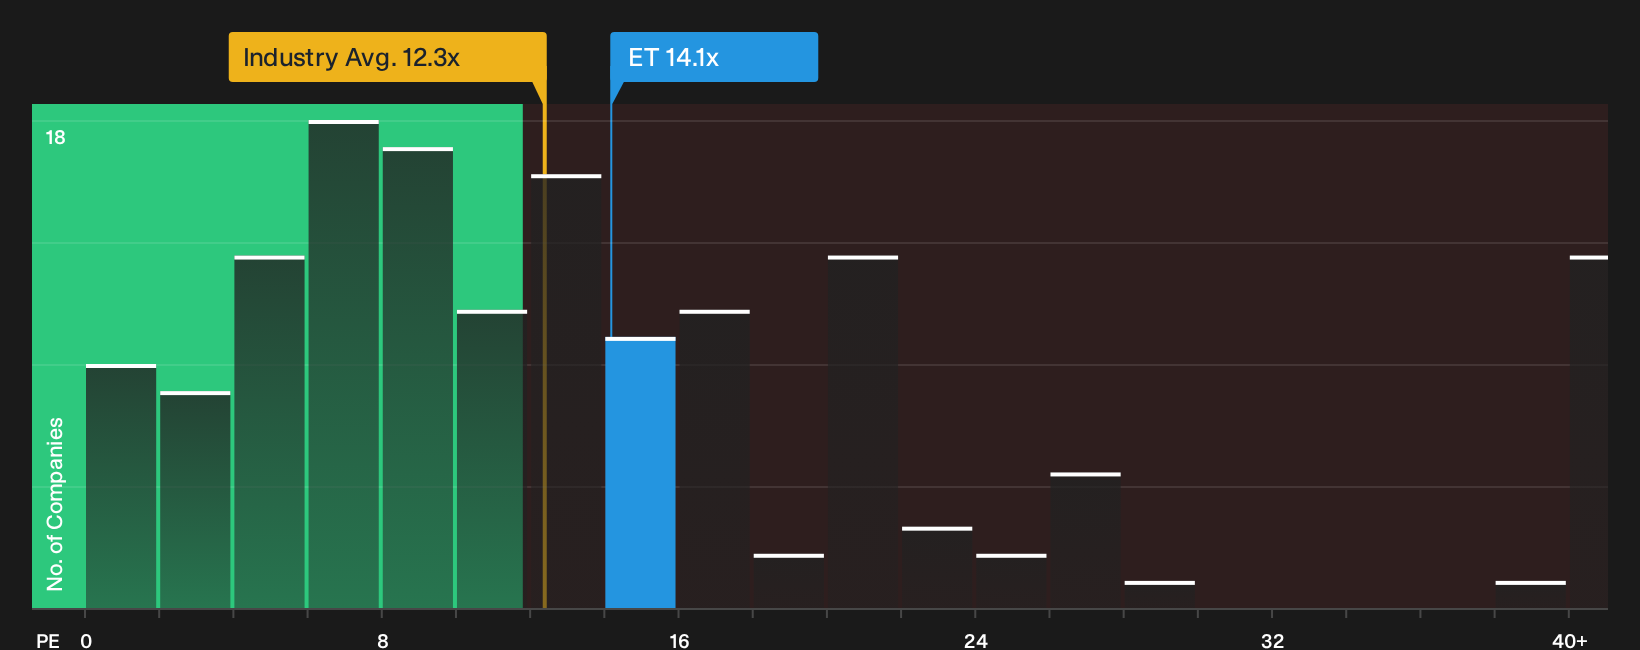
The P/E ratio fits Energy Transfer because investors focus closely on what each dollar of partnership earnings costs them. On this yardstick, the units trade at about 14.1x earnings, which is below both the peer group on roughly 18.4x and the broader oil and gas industry near 12.3x.
That gap to peers suggests the market is still applying a more cautious tag to Energy Transfer even though the partnership just marked its twentieth consecutive quarterly cash distribution increase. Because the current multiple also sits below the level implied by its own fundamentals based fair P/E yardstick, the units currently screen as undervalued on earnings compared with what the model suggests could be justified. Explore the numbers behind Energy Transfer's P/E valuation.
The Energy Transfer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question leaves off for Energy Transfer by spelling out what kind of future for growth, margins and earnings would need to hold for the units to trade meaningfully above or below today’s level, and they sit on the platform’s Community page. Each one treats fair value as a thesis about Energy Transfer's business that you can watch over time, rather than a single frozen snapshot.
One of the top community narratives on Energy Transfer: 16% undervalued
"Recent long term customer commitments on multi billion dollar projects are now supported by more than 6 Bcf/d of contracted pipeline capacity..."
Discover why this Narrative puts Energy Transfer at 16% undervalued.
One more thing to weigh on Energy Transfer before you act
Everything so far has focused on what Energy Transfer looks like today, but professional forecasts sketch out where earnings and cash flows might be a few years from now and give you another yardstick to compare with the current multiple. Explore where analysts expect Energy Transfer to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com