


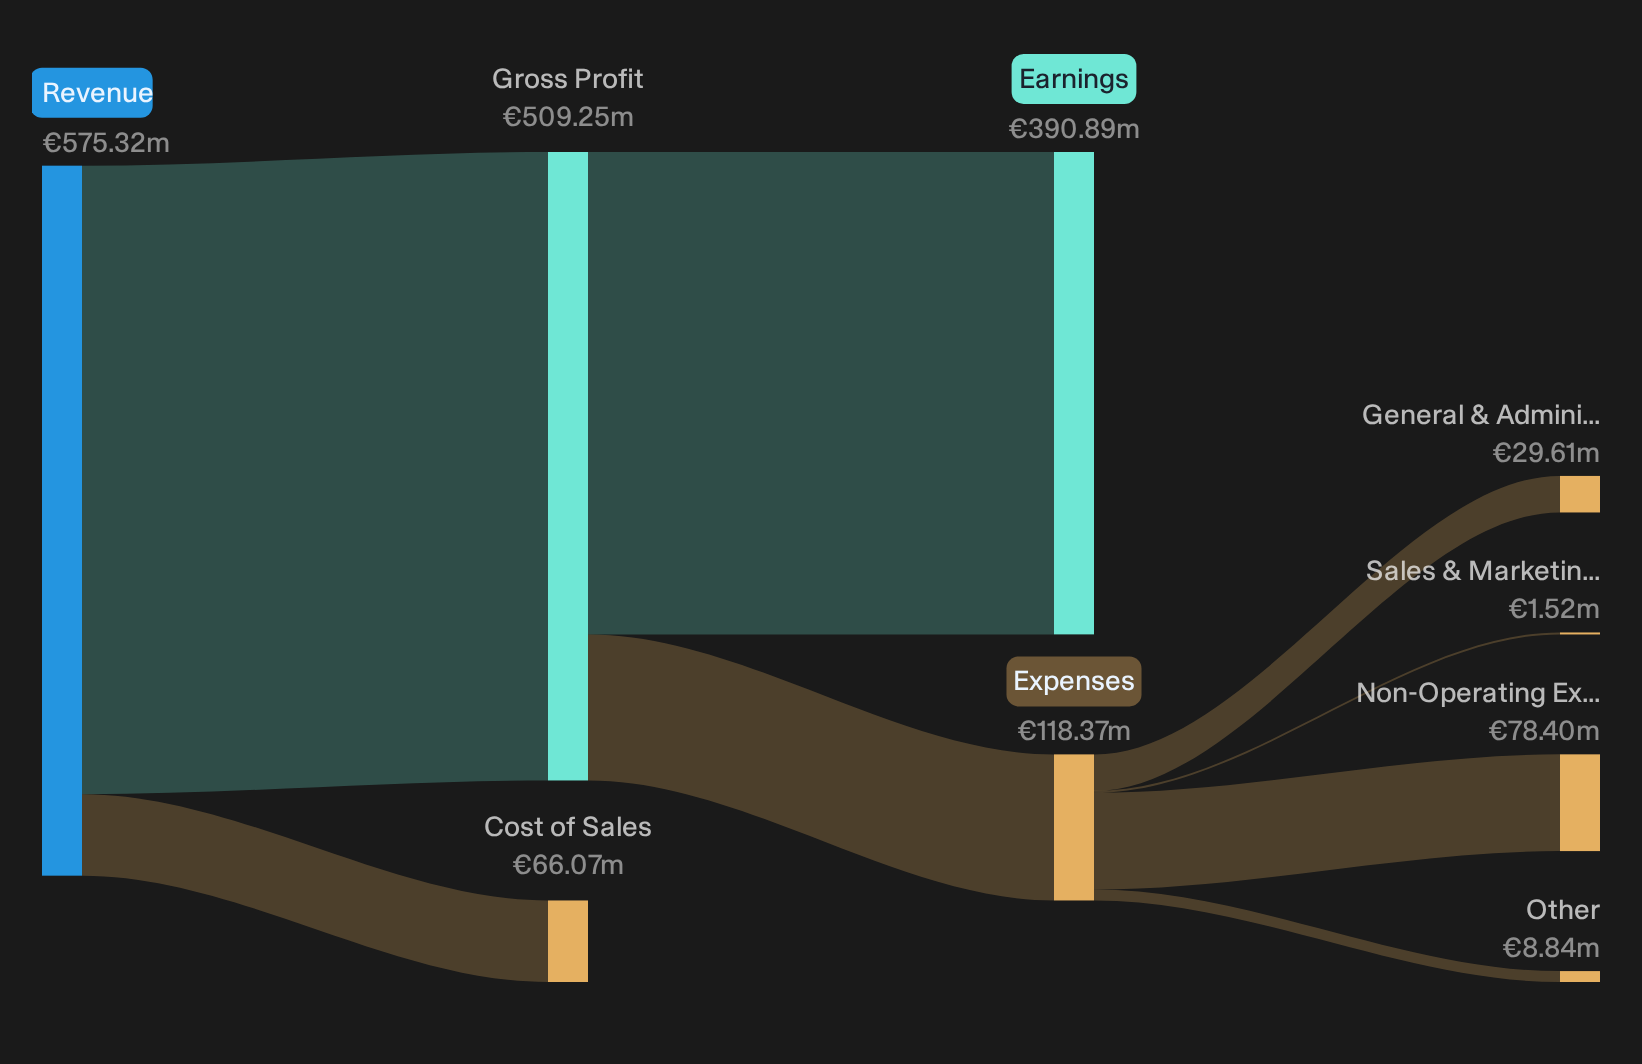
Warehouses De Pauw walked into its Q3 2026 earnings with the stock already under pressure, down over 13% across the past three months and closing at €19.25. The fresh numbers show quarterly net income of €97.016 million on revenue of €128.149 million, keeping profitability firmly intact even as sentiment has cooled. That clash is the story. Investors are reacting to balance sheet concerns and a higher cost of capital, while the income statement still points to a profitable logistics real estate platform rather than a business in distress.
Love that Warehouses De Pauw is still printing solid profits but worried about balance sheet pressure and a pricier funding backdrop? Take a look at our screener of companies that pair durable earnings with sturdier finances through the list of solid balance sheet and fundamentals stocks (204 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €128.149 million vs. €136.828 million (down 6.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): €97.016 million vs. €107.497 million (down 9.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.402 vs. €0.461 (down 12.8%)
- Trailing 12 Month Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): €390.886 million vs. €375.860 million (up 4.0%)
Earnings tell you what Warehouses De Pauw reported this quarter, but investors who care about what they are paying for ENXTBR:WDP usually focus on the cash coming in and out of the business. Looking purely at Warehouses De Pauw's cash generation and discounting those streams back, the stock could be a striking 33% undervalued.
Profits And Occupancy Keep The Bull Case Alive
For anyone arguing that Warehouses De Pauw is still a solid logistics platform, this quarter gives some backing. Revenue and quarterly net income eased, yet trailing 12 month earnings excluding extra items edged higher and year to date EPS is up about 5%. Occupancy at 97.2% and a largely pre let €800m pipeline with a 7% target net operating income yield support the idea of a still productive asset base, not one struggling to fill sheds.
Funding Costs And Merger Optionality Feed The Bears
Concerns around balance sheet pressure and a pricier funding climate find some echo in the numbers and plans. Quarterly revenue and profit both declined year on year, and management repeatedly acknowledged a higher euro cost of capital. Even with EPRA loan to value around 37%, a €400m equity raise and potential cash outflow from ARGAN exit rights keep leverage and dilution in focus. The planned cross border merger and expanding development pipeline also increase execution risk at a time when the share price has fallen double digits over 90 days.
After Warehouses De Pauw flagged higher funding costs, potential dilution and ARGAN exit risks, it is worth asking if these are isolated issues or hints of deeper balance sheet fragility. Review the independent risk analysis for Warehouses De Pauw which shows 1 important warning sign to see how many other structural vulnerabilities our risk model has already surfaced for you.Hunt For Quiet Dislocations
Warehouses De Pauw just showed how a solid profit story can still trade under a cloud of funding questions. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 36% below our estimate - targets high complexity manufacturing programs in regulated sectors and seeks longer production revenue streams.
- Company 2 - 46% below our estimate - supplies power and connectivity systems for AI data centers using copper and optical capabilities for higher margin contracts.
- Company 3 - 35% below our estimate - expands a mattress platform by integrating an acquired rival and scaling dealer reach and direct ecommerce channels.
That is three of the list. See every one of the 192 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com