


- Burckhardt Compression subsidiary Shenyang Yuanda Compressor Co., Ltd. has secured multiple diaphragm compressor orders for ultra high purity hydrogen use in semiconductor manufacturing, extending the group’s hydrogen compression offering into a new end market.
- The move gives Burckhardt Compression a direct entry into hydrogen infrastructure for chip production, where uptime, purity standards, and long qualification cycles can translate into long term equipment and service relationships.
- We will now explore how Burckhardt Compression's investment narrative could be influenced by its hydrogen diaphragm wins in semiconductors.
Scan Burckhardt Compression's hydrogen and semiconductor angle against a hand picked field of infrastructure and energy enablers in our 55 AI infrastructure stocks.
Burckhardt Compression Holding Investment Narrative Recap
To own Burckhardt Compression Holding, you need to be on board with a compressor specialist tied closely to long cycle energy and industrial projects, where order intake and execution quality matter more than quarter to quarter headlines. The hydrogen and semiconductor wins help diversify away from more cyclical petrochemical and marine exposure, although at this stage the financial impact looks modest against a CHF 1.1b revenue base.
Right now, the key near term swing factor is how resilient Systems Division orders remain if petrochemical and hydrogen project activity cools or gets deferred, especially given limited overall revenue growth forecasts and earnings expected to edge lower. The biggest risk is still lumpiness in large projects and rising credit exposure in markets like China, not these specific hydrogen diaphragm contracts.
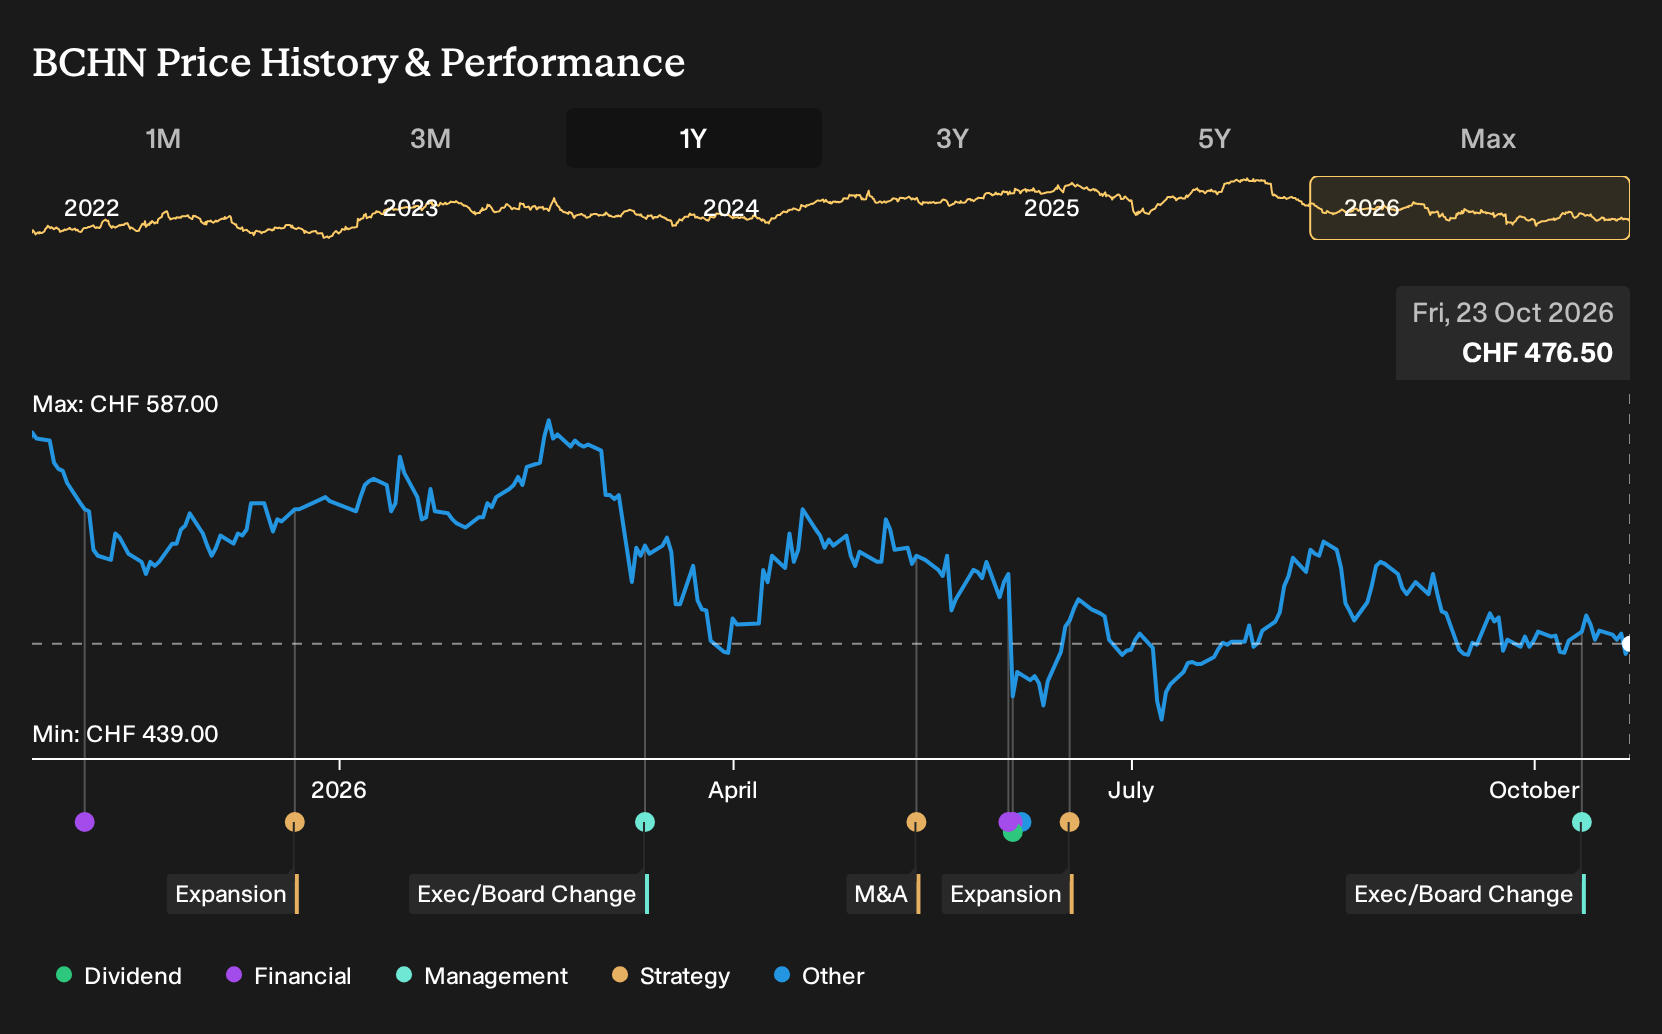
The management change in the Systems Division is the announcement that really links back to this semiconductor hydrogen story. From 1 November 2026, Daniel Meier will run Systems, stepping up from Vice President EMEA with 19 years inside Burckhardt Compression. That puts someone with deep engineering and supply chain experience directly over the diaphragm and hydrogen portfolio.
For you as a shareholder, the question is whether this transition keeps execution tight on complex projects while the firm pushes into hydrogen infrastructure for sectors like semiconductors. Smooth handover and stable leadership are important, because any slip in delivery, receivables collection, or pricing on large compressor packages would hit the same earnings and cash flow that drive the stock’s current P/E and analyst expectations.
Burckhardt Compression Holding's narrative projects CHF 1.1b revenue and CHF 118.6 million earnings by 2029. This projection reflects broadly flat yearly revenue trends and an earnings increase of CHF 8.5 million from CHF 110.1 million today.
Uncover why Burckhardt Compression Holding's fair value points to a 28% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts already penciled in CHF 1.1b revenue and CHF 126.2 million earnings by 2029 for Burckhardt Compression before this semiconductor hydrogen news. You now see a different angle. Those forecasts lean heavily on a Services catch up cycle, while the new diaphragm wins hint at a potentially broader Systems story that could shift future narratives.
Explore 3 other Burckhardt Compression Holding fair value estimates, including one that suggests as much as 28% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Burckhardt Compression Holding research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Burckhardt Compression Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Burckhardt Compression Holding's overall financial health at a glance.
Looking for more investment ideas beyond Burckhardt Compression Holding?
Once you have a view on Burckhardt Compression Holding, it can help to compare that thesis with other opportunities that share similar qualities in terms of balance sheet strength, value, or income potential. The Simply Wall St Screener can surface those candidates quickly so you spend more time weighing the story and less time trawling through tickers.
If you want to broaden your watchlist with focused sets of companies, these curated filters are a useful place to start:
- For investors who like potential upside but still care about quality, scan a 192 high quality undervalued stocks that blend solid fundamentals with prices that may not fully reflect them.
- If capital preservation and a smoother ride matter to you, work through a 221 resilient stocks with low risk scores that screen well on resilience and balance sheet strength.
- When you are hunting for underfollowed stories with room for the narrative to evolve, use a 615 high quality undiscovered gems that score well on fundamentals yet are not widely followed by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com