


Seadrill (SDRL) just secured a series of fresh drilling contracts and extensions spanning Indonesia, Malaysia, Angola, and the U.S. Gulf, which may reshape how investors view its future workload and revenue visibility.
The contract wins arrive as Seadrill’s share price return has gained 49.79% year to date and 16.51% over 90 days, with the stock now at $52.35. The 1 year total shareholder return of 64.21% signals strong momentum rather than fading interest.
Scan how Seadrill’s contract momentum compares with other offshore drilling and energy contractors by running through our hand picked list of solid balance sheet and fundamentals (25 results) in a few minutes.
Bulls see Seadrill’s fresh contracts and 64.21% one-year return as proof the rally still has room, while bears point to legal overhang and recent gains. Which story do the current valuation markers support next?
Most Popular Narrative: 3% Undervalued
At a last close of $52.35 against a narrative fair value of $54.00, Seadrill is framed as modestly undervalued, with the thesis leaning heavily on contract backlog and cash generation rather than multiple expansion alone.
The shift from heavy project spending on reactivations and reacceptances toward lower capital expenditure guidance of US$200 to US$240m, alongside refinancing at lower coupons and an extended share repurchase authorization, points to an inflection toward stronger free cash flow and potential improvement in net margins and per share earnings.
See why 10 investors see Seadrill as 3% undervalued.
Result: Fair Value of $54.00 (UNDERVALUED)
Still, the Seadrill story can break if oil price swings hit customer drilling plans, or if weaker margins and negative free cash flow persist longer than analysts expect.
Find out about the key risks to this Seadrill narrative.
Another View: What Seadrill’s P/S Says
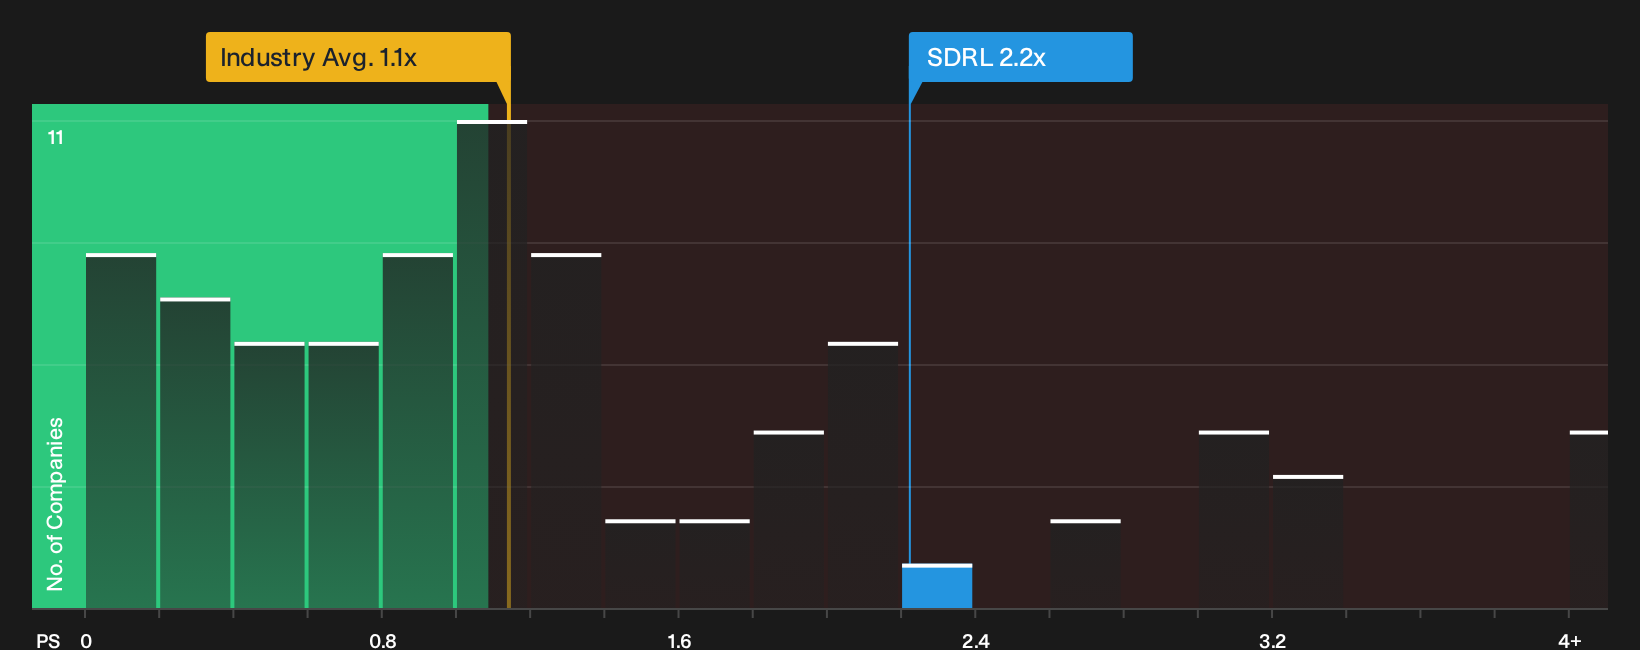
The first fair value story paints Seadrill as modestly undervalued. The P/S picture is harsher. At about 2.2x sales, the stock trades at roughly double the US Energy Services average of 1.1x and above peer levels around 1.4x, while the fair ratio estimate also sits at 1.1x. That gap points to real rerating risk if execution or the offshore cycle disappoints, so how much valuation stretch are you comfortable carrying?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Seadrill's valuation and risk reward profile can feel messy, so move quickly to interpret the data and stress test it yourself using 2 key rewards and 2 important warning signs.
Looking for more Seadrill sized investment ideas?
Do not stop your research at Seadrill. Broaden your watchlist using focused idea lists that surface different types of opportunities other investors may be slow to notice.
- Target potential bargains that pair robust financials with compressed expectations using a curated set of 27 high quality undervalued stocks.
- Find income focused ideas by reviewing companies that feature stronger yields and sturdier payouts through our hand selected 5 dividend fortresses.
- Reduce the risk of unpleasant surprises by scanning companies that clear tougher balance sheet and fundamentals checks in our focused list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com