


Boot Barn Holdings (BOOT) is back in focus as fresh commentary points to upcoming quarterly earnings that are expected to land close to consensus and include a reiteration of longer term guidance.
Recent trading tells a different story to the upbeat commentary. Boot Barn Holdings’ share price is down 23.2% over the past 90 days and 38.3% year to date, and the 1-year total shareholder return has declined 41.5%, even though the 3-year total shareholder return is still up 65.8%. This suggests long-term holders have seen gains, while near-term momentum has faded as investors reassess growth potential and risks ahead of the next earnings update.
Scan beyond Boot Barn Holdings and see how it compares with other retailers under pressure and potential breakouts in our hand picked 27 high quality undervalued stocks.
After a drop this sharp in Boot Barn Holdings, investors are left weighing one simple thing. Is most of the opportunity now ahead of the stock, or did the big gains already happen?
Most Popular Narrative: 45% Undervalued
On the most followed valuation narrative, Boot Barn Holdings screens as materially cheaper than its implied fair value of about $207.87 compared with the recent $115.18 close. This puts the focus on what needs to go right rather than on whether the stock has already run too far.
Continued capital-efficient store expansion, with 70 planned openings in fiscal 2027 after 17% unit growth in the prior year and a long-term path from 566 stores toward roughly 1,200 locations, gives Boot Barn Holdings a multiyear opportunity to add revenue and scale earnings as new units reach projected first year sales of about US$3.2 million with sub two year paybacks.
See why 11 investors see Boot Barn Holdings as 45% undervalued.
Result: Fair Value of $207.87 (UNDERVALUED)
Still, the Boot Barn Holdings story can break if aggressive store openings start to dilute returns, or if softer Western demand lingers longer than analysts currently factor in.
Find out about the key risks to this Boot Barn Holdings narrative.
Another View on Boot Barn Holdings Valuation
The popular narrative leans on analyst targets that put Boot Barn Holdings well below an implied fair value of $207.87. A second lens tells a very different story. Our DCF model estimates the value of future cash flows at $52.37 per share, which sits far under the recent $115.18 price and frames the stock as overvalued on this measure.
The gap between a 45% upside case and a DCF that points in the opposite direction leaves you with a simple question: Which set of assumptions about growth, margins, and required returns feels more realistic for Boot Barn Holdings over the next decade, not just the next quarter?
Look into how the SWS DCF model arrives at its fair value.
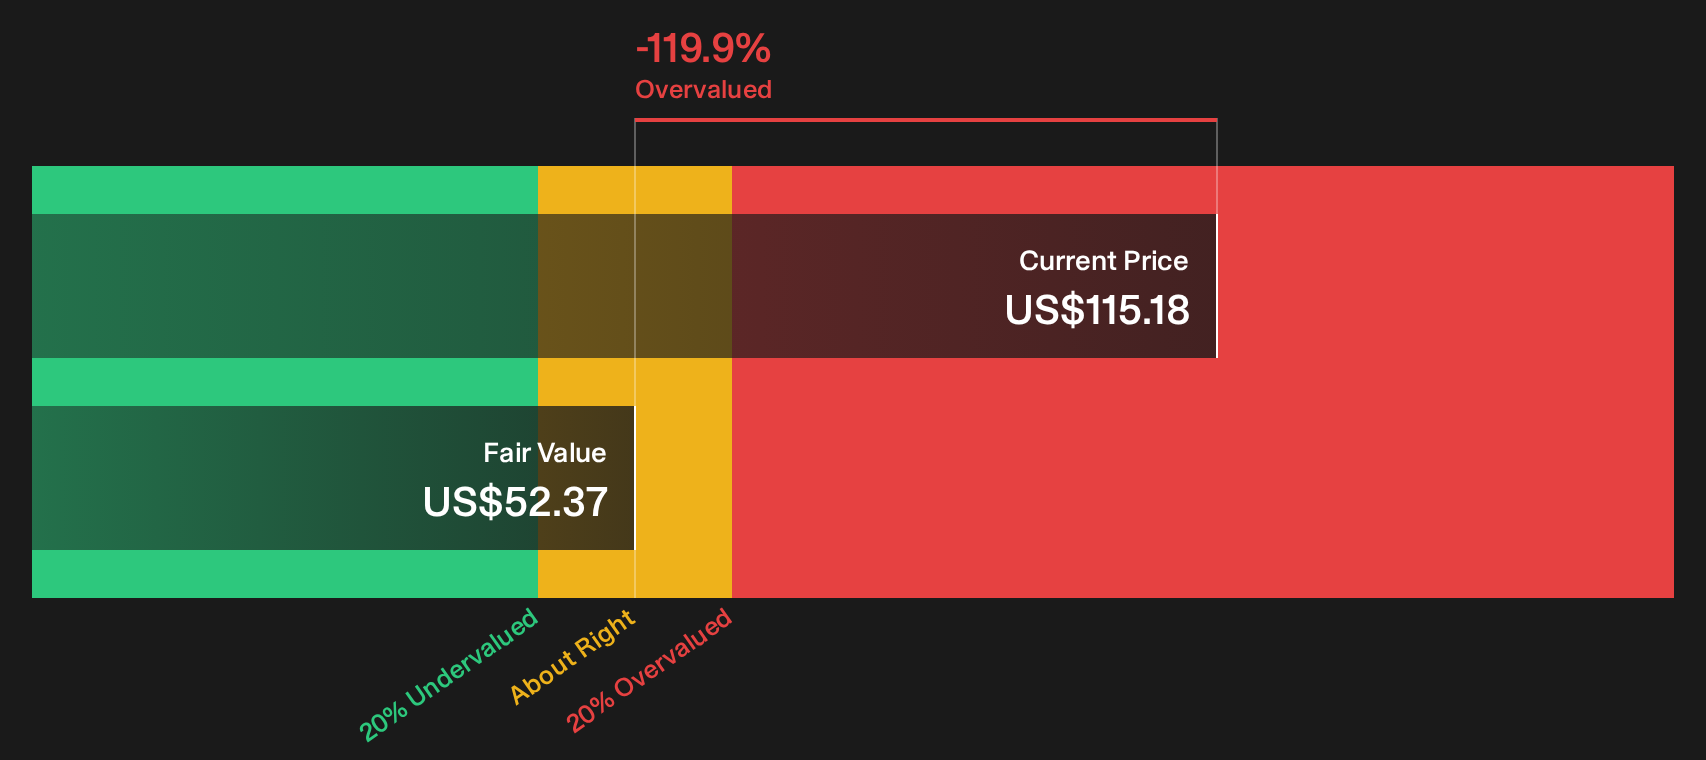
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boot Barn Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Boot Barn Holdings feels familiar, let it motivate you to check the numbers directly, decide quickly where you stand, and then review the 3 key rewards.
Looking for more investment ideas beyond Boot Barn Holdings?
Do not stop with Boot Barn Holdings. Use the Simply Wall Street Screener to line up your next watchlist additions while this earnings story is front of mind.
- Target long-term compounding potential by scanning a 30 resilient stocks with low risk scores that aims to pair resilience with measured upside.
- Hunt for quality at a sensible entry point by working through a curated 21 high quality undiscovered gems that may not yet be widely followed.
- Prioritise financial strength first and filter for durability using a list of solid balance sheet and fundamentals (25 results) that helps you focus on sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com