


Navigator Company closed at €2.94 on Friday, down over the week and over the past month, as traders reacted quickly to its Q3 2026 figures. The headline looked simple at first glance. Revenue reached €525.6m while basic earnings per share landed at €0.02. The share price move told a different story from the income statement. In the short term, the market focused on softer earnings and a thinner net margin profile over the last 12 months. Over a longer horizon, investors are weighing that margin squeeze against multi year forecasts and a valuation that still prices the pulp and paper group on a 22.8x P/E.
You might appreciate the strong revenue performance at Navigator Company but feel cautious about its narrower net margin and 22.8x P/E ratio. Compare this trade off with our list of solid balance sheet and fundamentals stocks (204 results) to see how it stacks up.
Q3 2026 Earnings Summary
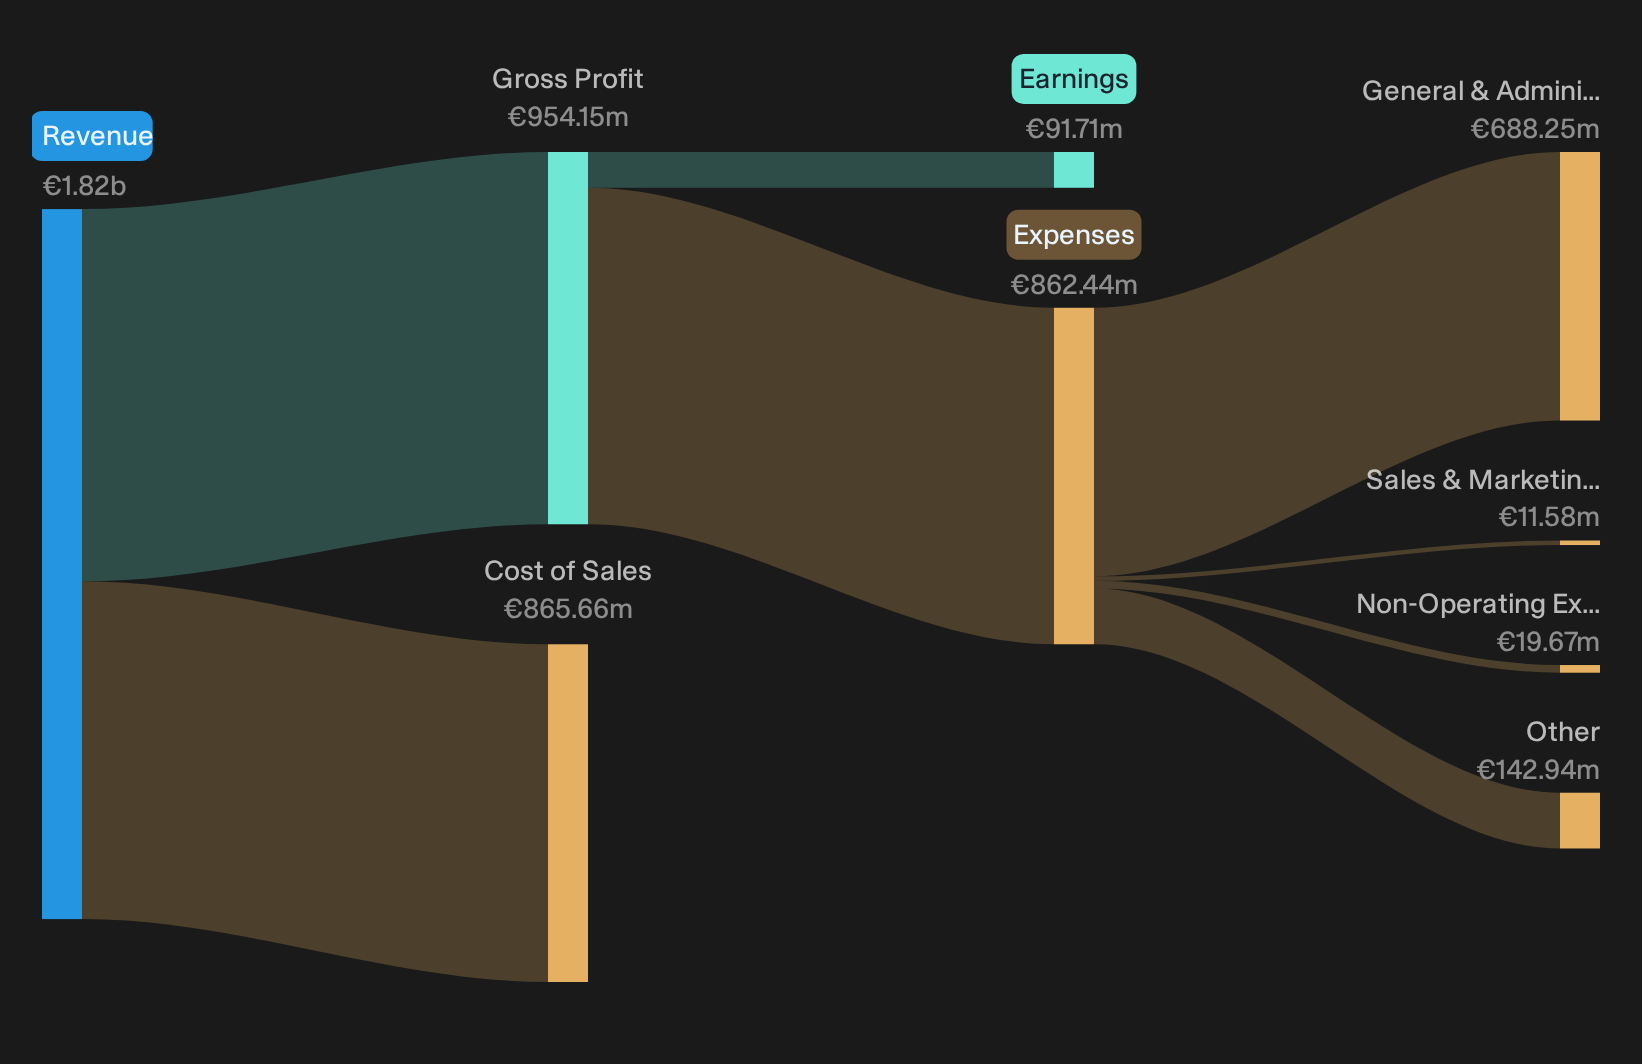
- Revenue (Q3 2026 vs Q3 2025): €525.6m vs. €470.6m (higher quarterly revenue compared with the prior year period)
- Net Income (Q3 2026 vs Q3 2025): €16.2m vs. €33.1m (net profit roughly halved year on year)
- Basic EPS (Q3 2026 vs Q3 2025): €0.0228 vs. €0.0466 (earnings per share declined compared with the prior quarter year)
- Net Margin (TTM 2026 vs TTM prior year): 5% vs. 8.1% (profitability compressed over the last 12 months)
Ask Charlie what Navigator Company’s valuation gap really reflects.
Revenue Resilience Backs Parts Of Bullish Story
Navigating Navigator Company’s mixed print, the top line still does some heavy lifting for the optimistic view. Revenue reached €525.6m in Q3 2026 compared with €470.6m a year earlier, which broadly supports the idea that a diversified pulp, paper, tissue, packaging and energy platform can keep sales ticking even as product mixes evolve. For investors who like the everyday demand angle in tissue and packaging, this kind of turnover performance supports the view that the wider group can still draw in business while the sector works through structural change in printing and writing paper.
Margin Squeeze Highlights Bearish Profit Concerns
Profit tells a tougher story than revenue. Net income of €16.2m in Q3 2026 versus €33.1m a year earlier and a trailing net margin that moved from 8.1% to 5% show clear pressure on earnings quality. That compression reflects concerns about a mature core in printing and writing paper and cost sensitivity across forestry and pulp. With the share price down over the past week, month and quarter, the direction of both profitability and recent returns aligns with investors who see more immediate risk than reward in Navigator Company’s current earnings mix.
After a margin reset like this, the real question is whether debt and dividend pressure hint at deeper structural issues. Review the risk analysis for Navigator Company which shows 3 important warning signsHunt For Earnings Disconnects
Navigator Company reports a weaker margin profile alongside a solid revenue outcome. The real opportunity sits in identifying shares that could be undervalued before the wider market recognizes the gap.
- Company 1 - 45% below our estimate - builds a larger Pacific banking footprint by integrating a deposit rich acquisition into an asset sensitive balance sheet.
- Company 2 - 29% below our estimate - captures rising engine aftermarket work as airlines extend fleets and seek more fuel efficient, lower emission propulsion technology.
- Company 3 - 25% below our estimate - scales complex generics and ex U.S. businesses while using stronger cash flow to fund product filings and trim net debt.
Those are three of them. See all 192 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com