


Energean (LSE:ENOG) has drawn fresh attention after announcing $4b in new gas contracts, taking total contracted revenue above $20b over the next 20 years, centred on long-term supply deals in Israel.
The fresh contracts arrive at a time when Energean’s share price has come under pressure, with the stock down 18.96% on a year-to-date share price basis and the 1-year total shareholder return declining 17.30%, even though the 3- and 5-year total shareholder returns of 14.57% and 17.57% point to a stronger longer-term record.
Scan how Energean compares to a curated 8 high quality undervalued stocks that pair long-term contract visibility with solid balance sheets and cash generation potential.
Energean has secured decades of contracted gas sales while the share price has moved the opposite way this year. Is most of the rerating already spent, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 19% Undervalued
Energean’s most followed valuation thesis pegs fair value at £9.10 per share, above the last close of £7.35. This frames today’s discount through the lens of long term gas contracts and project timing.
The main thing that has to go right is delivering Katlan on time and on budget while managing leverage around the 2.5x to 3x target and then reducing it toward 2x once the project is on stream.
The company’s plan to hold leverage around 2.5x to 3x through Katlan construction with peak net debt of about $3.3b in 2026, then reduce leverage toward 2x as Katlan comes on stream from early 2027, points to lower interest expense over time and greater flexibility to direct free cash flow toward net income and shareholder distributions.
See why 19 investors see Energean as 19% undervalued.
Result: Fair Value of £9.10 (UNDERVALUED)
Still, Energean’s reliance on Israeli production and the potential for further impairments at assets like Cassiopea could quickly challenge this undervaluation story.
Find out about the key risks to this Energean narrative.
Another View: What Multiples Say About Energean
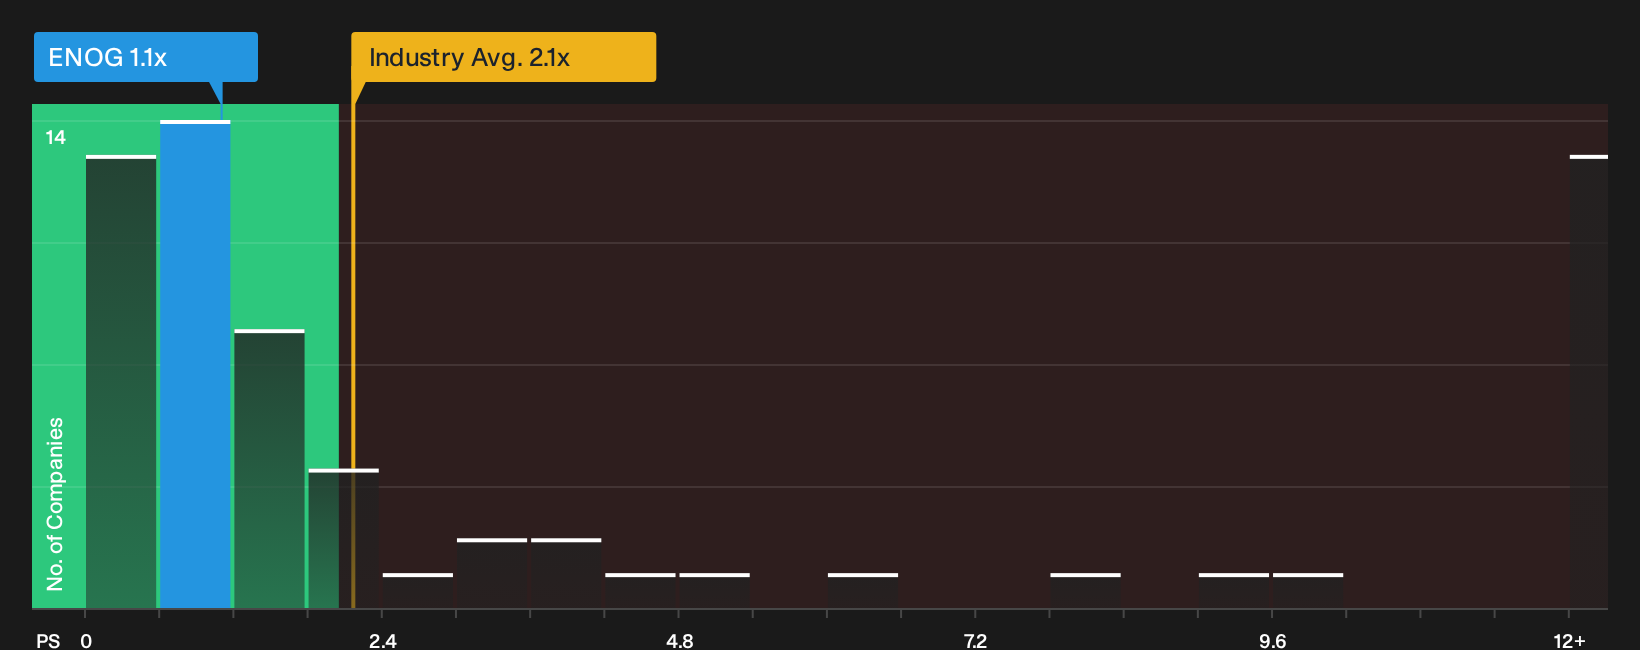
Energean might look undervalued on long term cash flow estimates, but its current P/S of 1.1x is slightly above a fair ratio of 0.9x, even though it sits below both the UK Oil and Gas industry at 2.1x and peer average at 1.9x. That mix hints at both opportunity and mispricing risk, so which side do you think dominates?
To pressure test whether this higher P/S versus the fair ratio points to limited upside or simply reflects current earnings pressure, it helps to see how the numbers stack up in a fuller valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Energean’s valuation and risk profile make this a moment to move quickly, review the numbers yourself, and weigh both sides of the argument by digging into the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Energean?
If Energean has sharpened your focus on valuation and risk, broaden your opportunity set and stress test your thinking with other well filtered opportunities on Simply Wall Street.
- Expand your hunt for quality by scanning a list of solid balance sheet and fundamentals (9 results) that can help you spot businesses with the financial strength to endure tougher periods.
- Target income potential by reviewing a 5 dividend fortresses that may appeal if you want cash returns alongside capital growth ambitions.
- Unearth fresh angles by checking a 5 high quality undiscovered gems before others start paying attention to the same set of stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com