


Ormat Technologies (ORA) is back in focus as fresh analysis highlights its record of topping earnings estimates and flags a positive Earnings ESP ahead of the company’s next quarterly report on November 4, 2026.
Despite rising optimism ahead of earnings, Ormat Technologies’ recent share price form has been weak, with the stock down 9.12% over the past month and 23.42% year to date, even as its 3 year total shareholder return of 44.27% and 5 year total shareholder return of 23.94% point to much stronger longer term momentum.
Scan beyond Ormat Technologies and compare its setup against a hand picked list of 30 resilient stocks with low risk scores that may offer a steadier path through the next earnings season.
The share price slide jars with Ormat Technologies’ earnings record and analyst optimism, which raises a simple question. Are you seeing a business problem here, or just a reset in sentiment that has moved the valuation?
Most Popular Narrative: 31% Undervalued
Ormat Technologies’ most followed narrative pegs fair value at $126.33, which sits well above the last close of $87.09 and characterizes the recent share price weakness as a valuation gap rather than a verdict on the underlying business.
The main thing that has to go right is successful execution of Ormat Technologies' large geothermal, energy storage and Enhanced Geothermal Systems build-out, including delivery of its identified project and interconnection pipeline within planned capital and margin frameworks.
The current valuation implies the market is not fully pricing in this narrative. This view is that Ormat Technologies is undervalued and that its capacity growth, margin targets and EGS opportunity could support a higher share price than today.
See why 11 investors see Ormat Technologies as 31% undervalued.
Result: Fair Value of $126.33 (UNDERVALUED)
Still, tax credit rules for China sourced storage hardware and Ormat Technologies’ roughly US$2.7b net debt load could quickly challenge this positive valuation story.
Find out about the key risks to this Ormat Technologies narrative.
Another View: Ormat Technologies Looks Expensive On Earnings
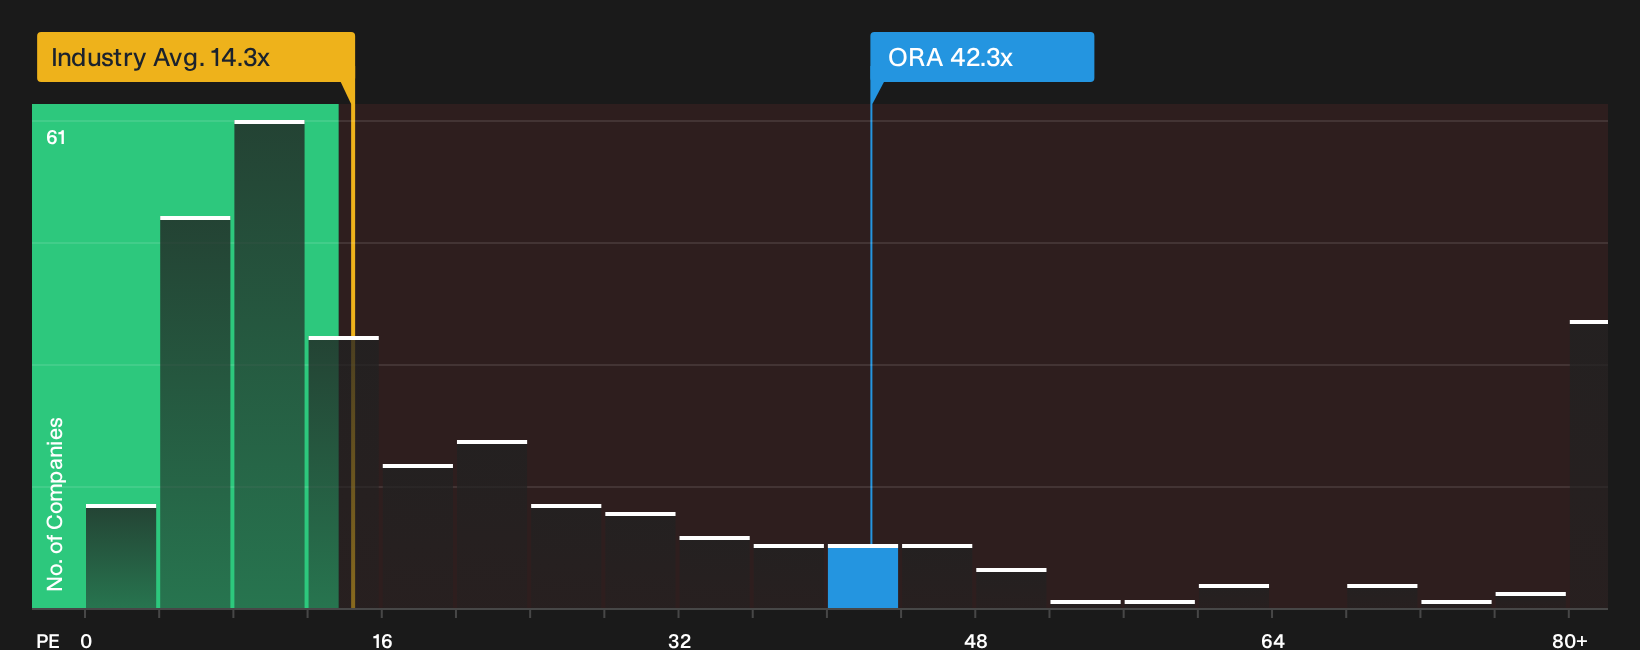
On the flip side of that $126.33 fair value, Ormat Technologies screens as expensive on current earnings. The stock trades on a P/E of 42.3x compared with a fair ratio of 23.9x, a US Renewable Energy industry average of 25.5x and a peer group around 27.9x. That gap points to real valuation risk if sentiment shifts. Which signal do you put more weight on?
For a closer look at how this earnings based view stacks up, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ormat Technologies so far. If you want to move quickly and decide for yourself, weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ormat Technologies?
Do not stop with Ormat Technologies alone. Use the time before the next earnings season to line up a watchlist of fresh ideas tailored to your own risk comfort.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying on perfect market sentiment.
- Hunt for mispriced quality by running through a 27 high quality undervalued stocks that filters for fundamentals that still look strong relative to current prices.
- Build a cash focused watchlist by checking a 5 dividend fortresses that concentrates on higher yielding payout streams supported by underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com