


Hexagon came into today with its share price at SEK106.05 after a strong 90 day run, and expectations were high for another clean quarter of precision growth. The Q3 2026 release delivered exactly where it hurts and helps most, a powerful 13% organic sales lift coupled with a 25.3% EBIT after cost margin in the core business. Yet the muted immediate move in the stock masks the real story. The gap between a low 9.8x P/E and this level of underlying profitability is now the key tension investors need to judge.
Love Hexagon’s 13% organic lift and 25.3% EBIT margin but unsure what to do with a stock on just 9.8x P/E? Benchmark it against our 192 high quality undervalued stocks to see how other high quality operators with strong earnings profiles line up.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €1,049.1m vs. €1,303.1m (reported top line lower year on year despite strong organic growth commentary)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): €446.0m vs. €33.9m loss (swing into profit from a prior period loss)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.1661 vs. €0.0126 loss (earnings per share moved from loss making to clearly positive)
- EBITAC Margin Excluding Robotics (Q3 2026 vs. Q3 2025): 25.3%, with the prior year lower by 450 bps on a like-for-like basis (profitability in the core Hexagon business stepped up meaningfully)
Tired of scrolling through dense earnings tables and walls of figures to make sense of Hexagon? See the full visual picture of the business, with valuation front and center, in the interactive company report for Hexagon.
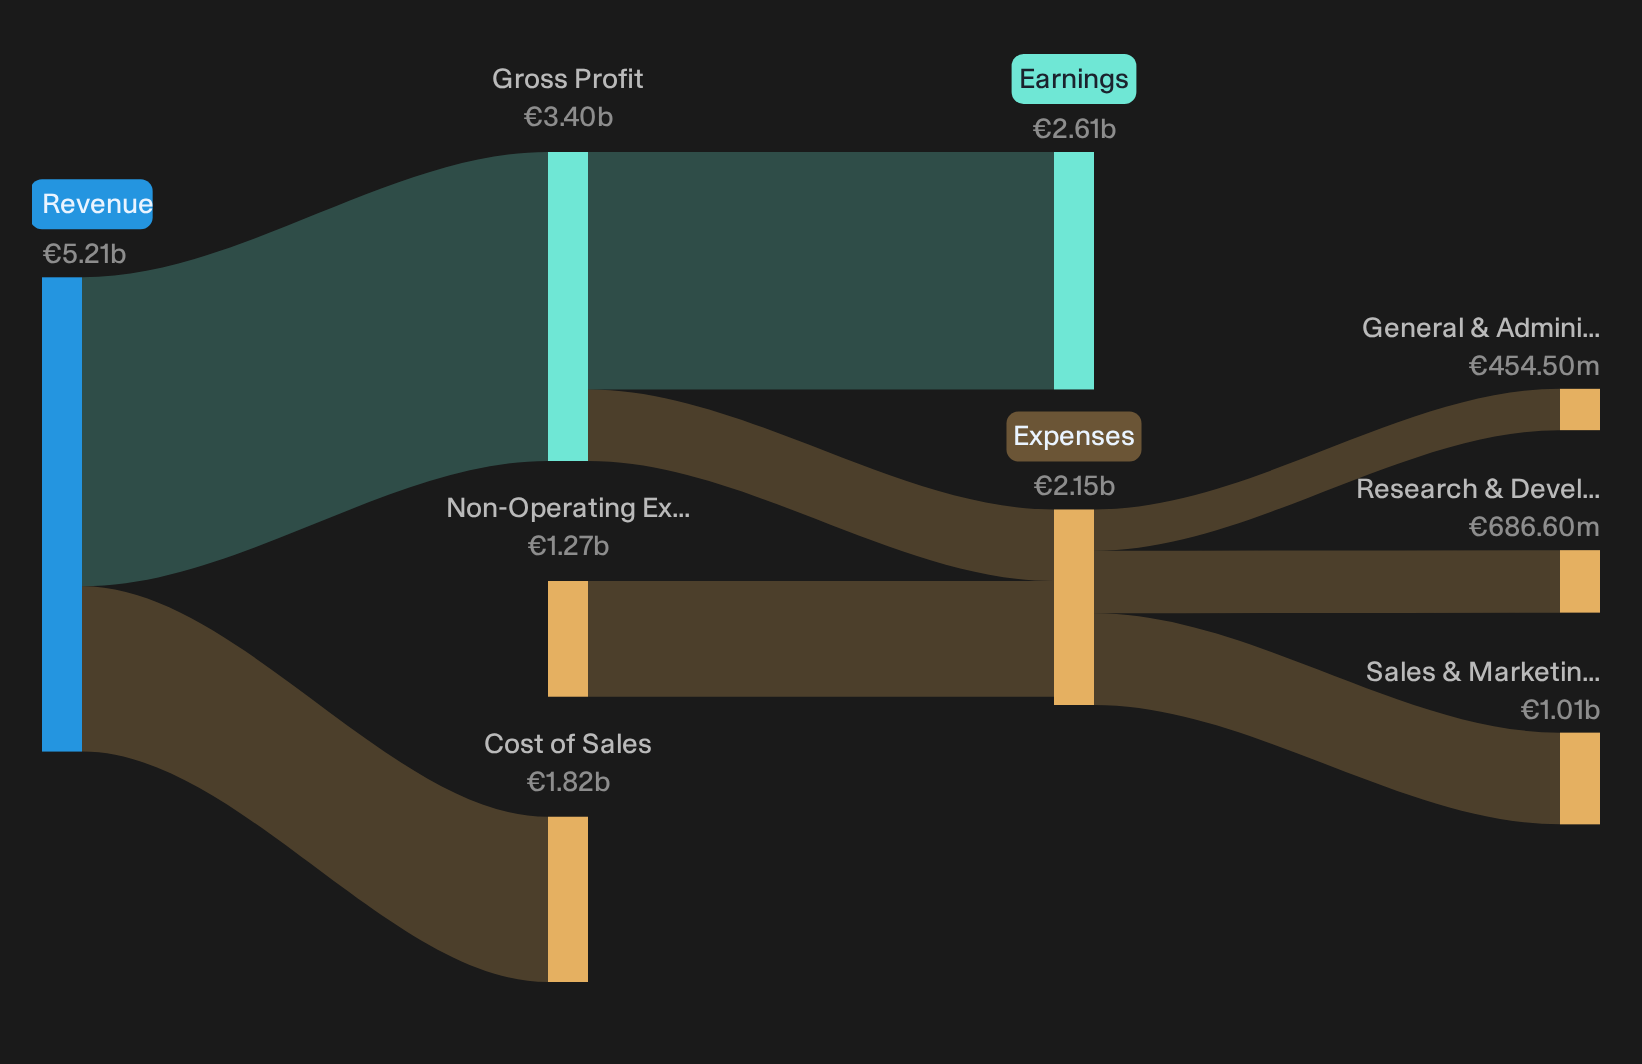
Hexagon’s Bull Case Meets The Numbers
Hexagon’s digital infrastructure story lines up cleanly with this quarter. Organic growth at 13% with the strongest contribution from Autonomous Solutions at 23% reinforces the idea that positioning and automation tools are gaining traction across end markets. Manufacturing Intelligence at 16% supports the industrial metrology narrative highlighted in recent sector research. EBITAC margin excluding robotics at 25.3% with gross margin around 62% shows the software and services layer is doing its job, turning sensor demand into high quality earnings.
Pressure Points For Hexagon’s Cautious View
Bears worried about cyclicality and balance sheet strain get a more mixed picture. Infrastructure & Geospatial at 4% organic growth and ongoing weakness in agriculture, parts of automotive and some construction show that not every exposed sector is firing. Yet cash conversion at 82%, net debt down to €489m and pro forma leverage around 1.4x indicate the financial base still looks solid even with rising robotics spend and incoming dilution from Waygate.
After a quarter shaped by one off items and earnings forecasts that point to a 35.9% yearly decline, it is worth asking whether Hexagon’s current profitability is masking deeper fragilities. Review the independent risk analysis for Hexagon which shows 2 important warning signs to see which structural warning signs the data is already flagging and how they compare with peers.Hunt For Mispriced Earnings Power
Hexagon illustrates how strong reported profitability can sit alongside a muted immediate share price reaction. The real opportunity is identifying stocks that may be undervalued before the market adjusts.
- Company 1 - 41% below our estimate - converts a rebuilt mortgage and insurance platform into higher transaction throughput on largely fixed infrastructure.
- Company 2 - 36% below our estimate - channels record program wins in tightly regulated hardware into a thicker backlog supported by disciplined working capital control.
- Company 3 - 42% below our estimate - builds new film production and logistics capacity so repeat installation customers face fewer product constraints during upgrade cycles.
Three companies from the same screener. Open every one of the 192 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com