


Old Republic International (ORI) just reported its third quarter 2026 results, showing higher revenue but softer quarterly profit, as investors weigh stronger auto warranty and title insurance performance against heavier technology and specialty expansion costs.
Old Republic International shares closed at US$38.91 after the results, with the 1-day share price return declining 2.92% and the 7-day move down 1.89% as investors reacted to the earnings miss and higher technology spending.
Over a longer stretch, momentum has cooled in the short term. The 90-day share price return is down 7.99% and the year-to-date move is lower by 10.08%, even though total shareholder return over five years is 108.82%, which reflects the impact of reinvested dividends alongside price gains.
Spot opportunities beyond Old Republic International by scanning a curated 27 high quality undervalued stocks that combines resilient cash flows with balance sheet strength when profitability trends come under pressure.Bulls point to Old Republic International’s higher revenue and efficient underwriting, while bears focus on softer profit and heavier tech spend. The valuation section now needs to clarify which of these perspectives the current price more closely reflects.
Most Popular Narrative: 11% Undervalued
Old Republic International’s most followed valuation storyline pegs fair value at $43.50 a share, above the latest $38.91 close. This puts recent price weakness in contrast with a more optimistic long term earnings and capital return view.
The current valuation implies the market is treating Old Republic International’s slower net premium growth, higher expenses and recent margin pressure as more important than the improvement in Title Insurance profitability, continued book value growth and consistent capital returns. This aligns with this narrative’s view that the stock is undervalued and the set up is bullish.
See why 20 investors see Old Republic International as 11% undervalued.
Result: Fair Value of $43.50 (UNDERVALUED)
Still, the Old Republic International story can lose momentum if Specialty Insurance margins remain weak and higher technology and expansion costs continue to weigh on earnings longer than expected.
Find out about the key risks to this Old Republic International narrative.
Another View: Old Republic International Through The P/E Lens
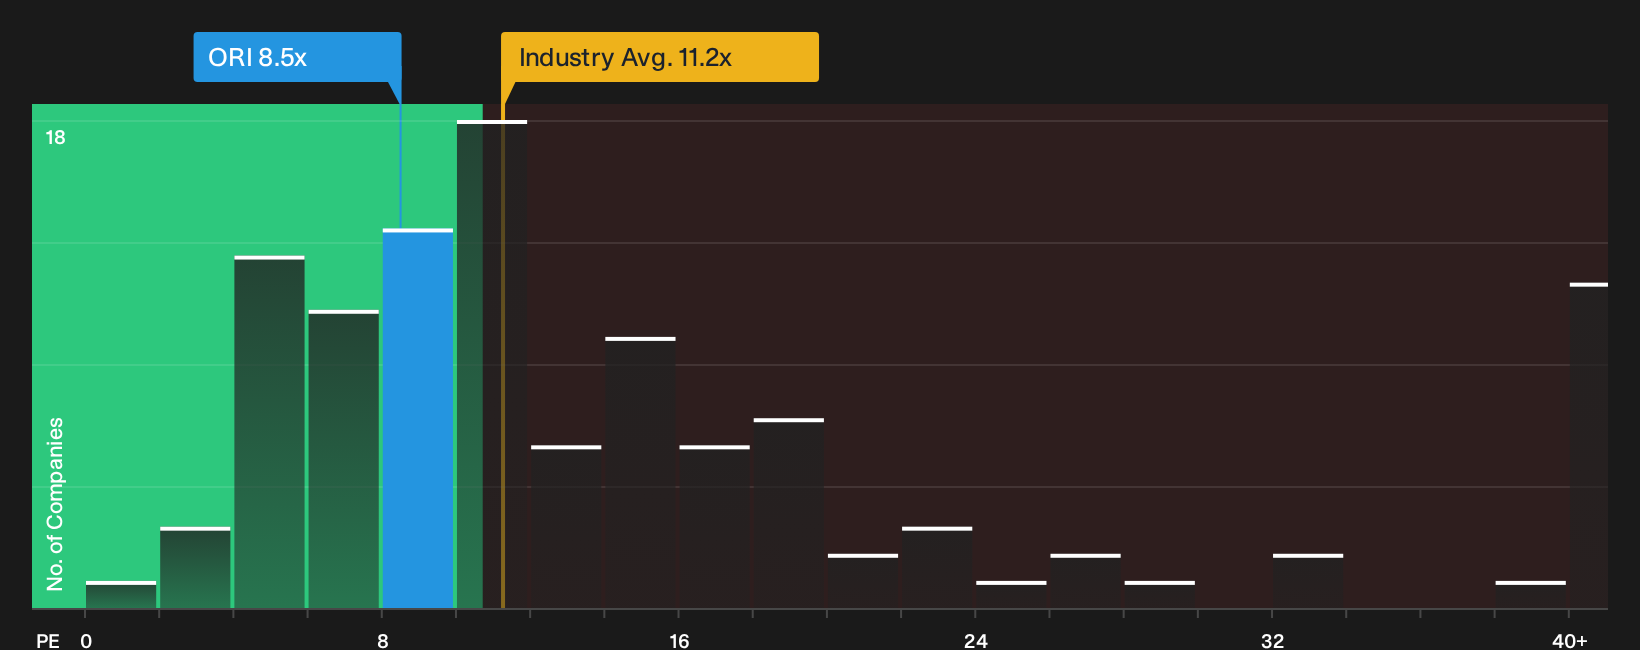
A second take on Old Republic International comes from its P/E ratio of 8.5x. That is lower than the US Insurance industry at 11.2x and below the 13.7x peer average, yet slightly higher than its own 7.8x fair ratio. This points to a mix of potential upside and valuation risk if the share price drifts toward that fair ratio.
For investors weighing this against the earlier fair value estimate, it can help to see how the numbers stack up side by side in a valuation breakdown. This includes where the current P/E sits relative to that fair ratio and sector averages, before deciding which interpretation feels more reasonable for their own expectations. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by Old Republic International’s mix of upside and risk signals? Act quickly, review the underlying data, then weigh 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Old Republic International?
Do not stop your research with Old Republic International. Fresh ideas often show up where pricing, balance sheet quality, and cash generation look most misaligned.
- Tap into potential value gaps by scanning a curated list of 27 high quality undervalued stocks before prices better reflect underlying fundamentals.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help steady returns when weaker companies hit turbulence.
- Hunt for under-the-radar opportunities through 21 high quality undiscovered gems that most investors have not scrutinized yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com