


Credo Technology Group Holding has seen its share price swing sharply in recent years, which puts fresh attention on a simple question for investors. Is the current valuation of Credo stock supported by the cash flows its business can realistically generate and sustain?
- Over the past 3 years, the stock has delivered a very large gain of about 9.6x, so any assessment now hinges on whether the future cash flow stream can live up to that kind of rerating.
- Recent news around Credo's role in AI data center connectivity and its work on standards like Short-Reach Micro-Emitter Optics may support expectations for future cash generation, but it also concentrates the story on how durable that demand will be and when it translates into steady cash flows.
- What if you looked at Credo Technology Group Holding through its earnings instead? See why Credo Technology Group Holding's 51.4x P/E tells a different valuation story.
The issue now is whether the current price of Credo is justified by the intrinsic value suggested by its cash flows under a Discounted Cash Flow (DCF) lens.
If you want a broader watchlist of companies tied to AI infrastructure, a focused screen of 55 AI infrastructure stocks is available.
Is Credo Technology Group Holding Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Credo Technology Group Holding can return to shareholders over time. Latest twelve month free cash flow sits at about $427 million in reporting currency terms. Analyst projections then step that up to higher annual free cash flows over the next decade, with 2031 expected at about $2.7b, which implies a growing profile rather than a shrinking one.
Those rising cash flow forecasts mean the DCF output points to an intrinsic value meaningfully above the current share price of $147.29. The recent AI data center pullback, highlighted by the broader sell off in suppliers tied to the build out, helps explain why the market price has not fully reflected those projected cash flows. Investors comparing Credo Technology Group Holding's role in AI connectivity with this cash flow curve may see a gap between the stock price and what the DCF suggests the business could be worth over time. Find out what Credo Technology Group Holding could be worth using our Discounted Cash Flow (DCF) estimate.
The Credo Technology Group Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Credo Technology Group Holding pick up where the cash flow puzzle leaves off and spell out which combinations of growth, margins and earnings paths would need to hold for the stock to be worth materially more or materially less than today's price on the DCF view. Instead of a single ratio or model output, Narratives turn that one figure into a concrete future that you can watch over time on the Community page and compare with how Credo Technology Group Holding's actual business progress evolves.
The community is broadly constructive on Credo Technology Group Holding, although one camp sees clear upside while the other argues the stock already reflects a lot of good news.
Bull case: 20% undervalued
"Post-DustPhotonics, Credo spans SerDes IP, DSP chips, AEC hardware, ZeroFlap optics transceivers, OmniConnect gearboxes, and silicon photonics PICs..."
Discover why this Narrative puts Credo Technology Group Holding at 20% undervalued.
Bear case: 13% overvalued
"CRDO has maintained a strong rating profile over a sustained period, and its recent price correction has brought the valuation to a level that could offer meaningful near-term returns..."
Explore why this Narrative puts Credo Technology Group Holding at 13% overvalued.
One more Credo Technology Group Holding signal investors are starting to watch
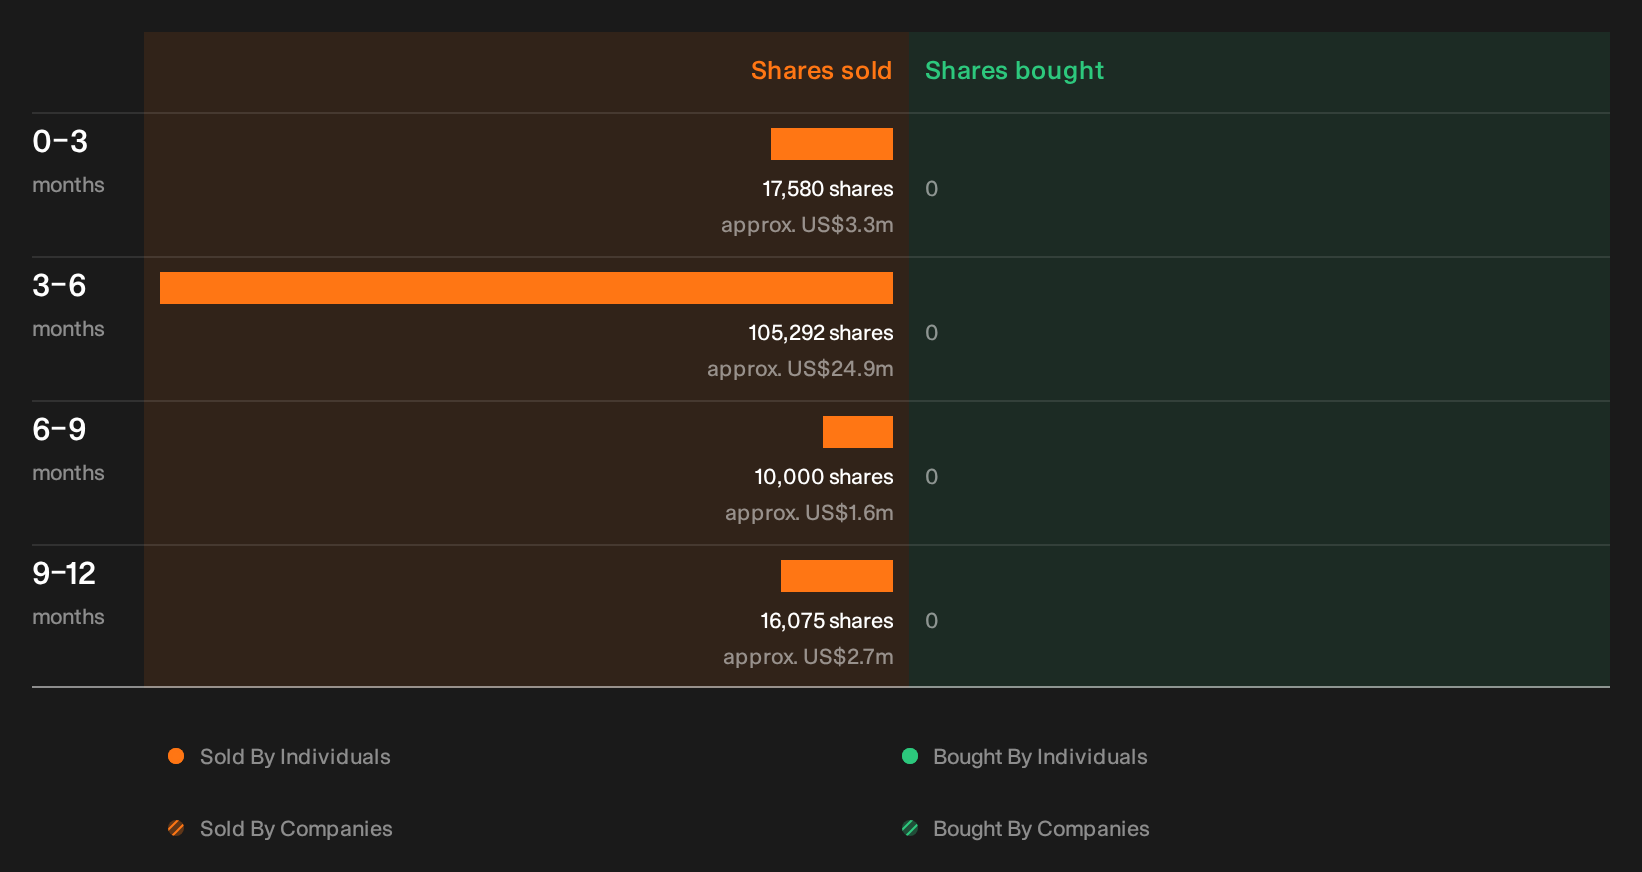
Valuation tells only part of the Credo Technology Group Holding story, because recent company insider transactions have been flagged by our checks and the individuals involved, the scale and what it might suggest are still for you to review. See the recent insider selling flagged for Credo Technology Group Holding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com