


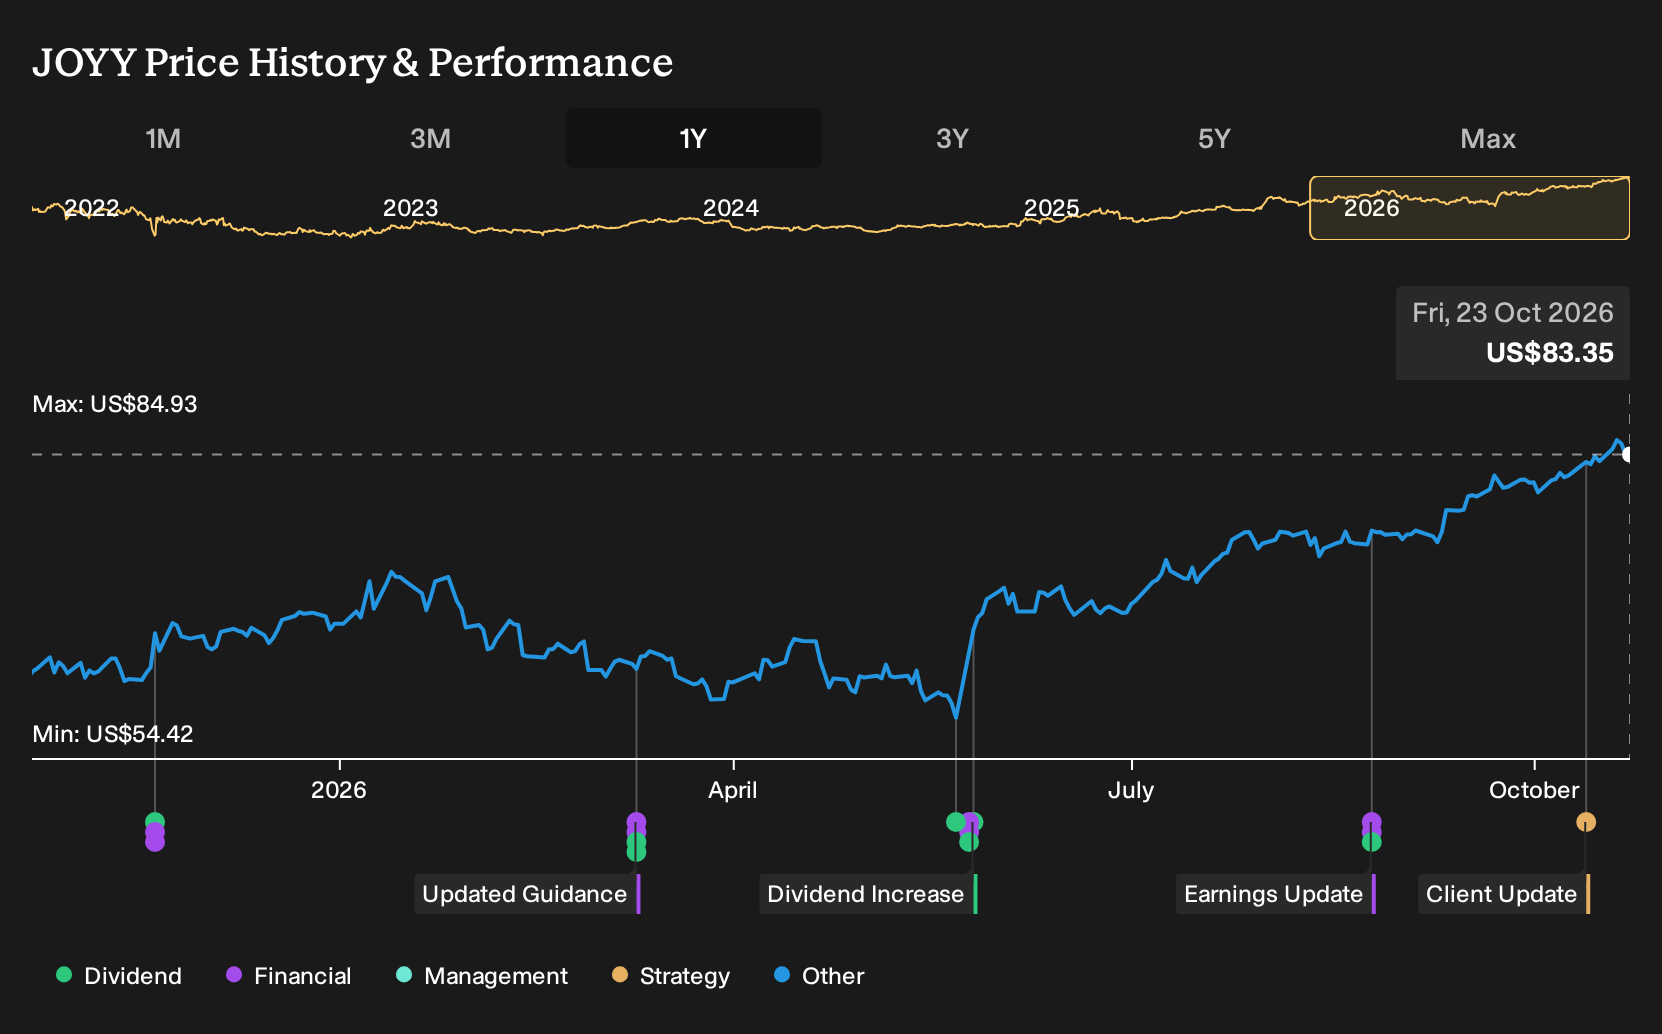
If JOYY was on your watchlist rather than in your portfolio, the result may sting. For JOYY shareholders, the return over the past year was 51.0%, including dividends. That kind of move raises a blunt question. What clues were hiding in plain sight in late 2025 that could have helped you judge whether JOYY’s push into AI driven advertising and broader social entertainment was more than a hopeful story, and instead a business shift worth backing?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
JOYY has already moved. Pinpoint other ways to investigate the theme among 39 AI small caps.
The Two JOYY Stories Investors Had To Judge
The shares cost US$59.51 at the start of the period, and anyone eyeing JOYY had to decide which of two stories felt more reasonable.
The bullish narrative put Fair Value at US$71.9, tied to an assumption that revenue could grow 6.1% a year while the business eventually traded on a future P/E of 40.0x.
The bearish view pinned Fair Value at US$37.18, with a softer 3.6% revenue growth assumption and concern that tighter data privacy rules might raise compliance costs and pressure margins.
What The Results Changed For The JOYY Thesis
The clearest development was JOYY’s Q2 2026 update. Total revenue reached US$590.8 million, up from US$507.76 million in Q2 2025, which backed the bulls’ focus on AI supported advertising and non livestreaming expansion. Profit told a different story. Net income slipped from US$60.48 million to US$51.45 million and net margin narrowed from 11.9% to 8.7%, so the profitability leg of the optimistic case stayed unproven. Overall, the evidence cut both ways.
The lesson is simple. When a growth story hinges on richer margins as much as higher sales, treat revenue and net margin as separate tests. For any other stock pitched on AI or advertising efficiency, track whether rising turnover is matched by stable or improving profitability in the reported numbers before treating the thesis as intact.
What JOYY’s Price Now Asks You To Believe
JOYY now trades at US$83.35. The selected Narrative sees Fair Value below that level, suggesting the current quote already builds in meaningful confidence around cash returns, AI driven advertising and the social entertainment ecosystem.
The key question is what must keep going right. A buyer today would be assuming JOYY sustains strong BIGO Ads momentum despite rising regulation and heavier competition.
"Key Takeaways: Increasing regulatory scrutiny and data privacy laws could limit user growth, constrain monetization, and raise compliance costs, compressing margins and eroding competitive advantages. Rising competition and market saturation threaten user engagement, drive up acquisition costs, and challenge the sustainability of JOYY's revenue and profit models."
One Narrative disagrees with today's price. → See where this Narrative says JOYY should trade
Looking One Step Beyond JOYY
JOYY is chasing AI powered engagement and monetisation. You can also look sideways at the tools helping other platforms run similar ideas at scale.
One heavyweight in that space builds the search, video and app systems that already shape how users discover content and how advertisers reach them.
It also runs a rapidly expanding cloud platform that lets enterprises train models, store data and plug AI directly into their workflows.
The same themes you are weighing with JOYY, from attention to monetisation to AI infrastructure, appear there inside a broader, deeply established ecosystem.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 35% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com