


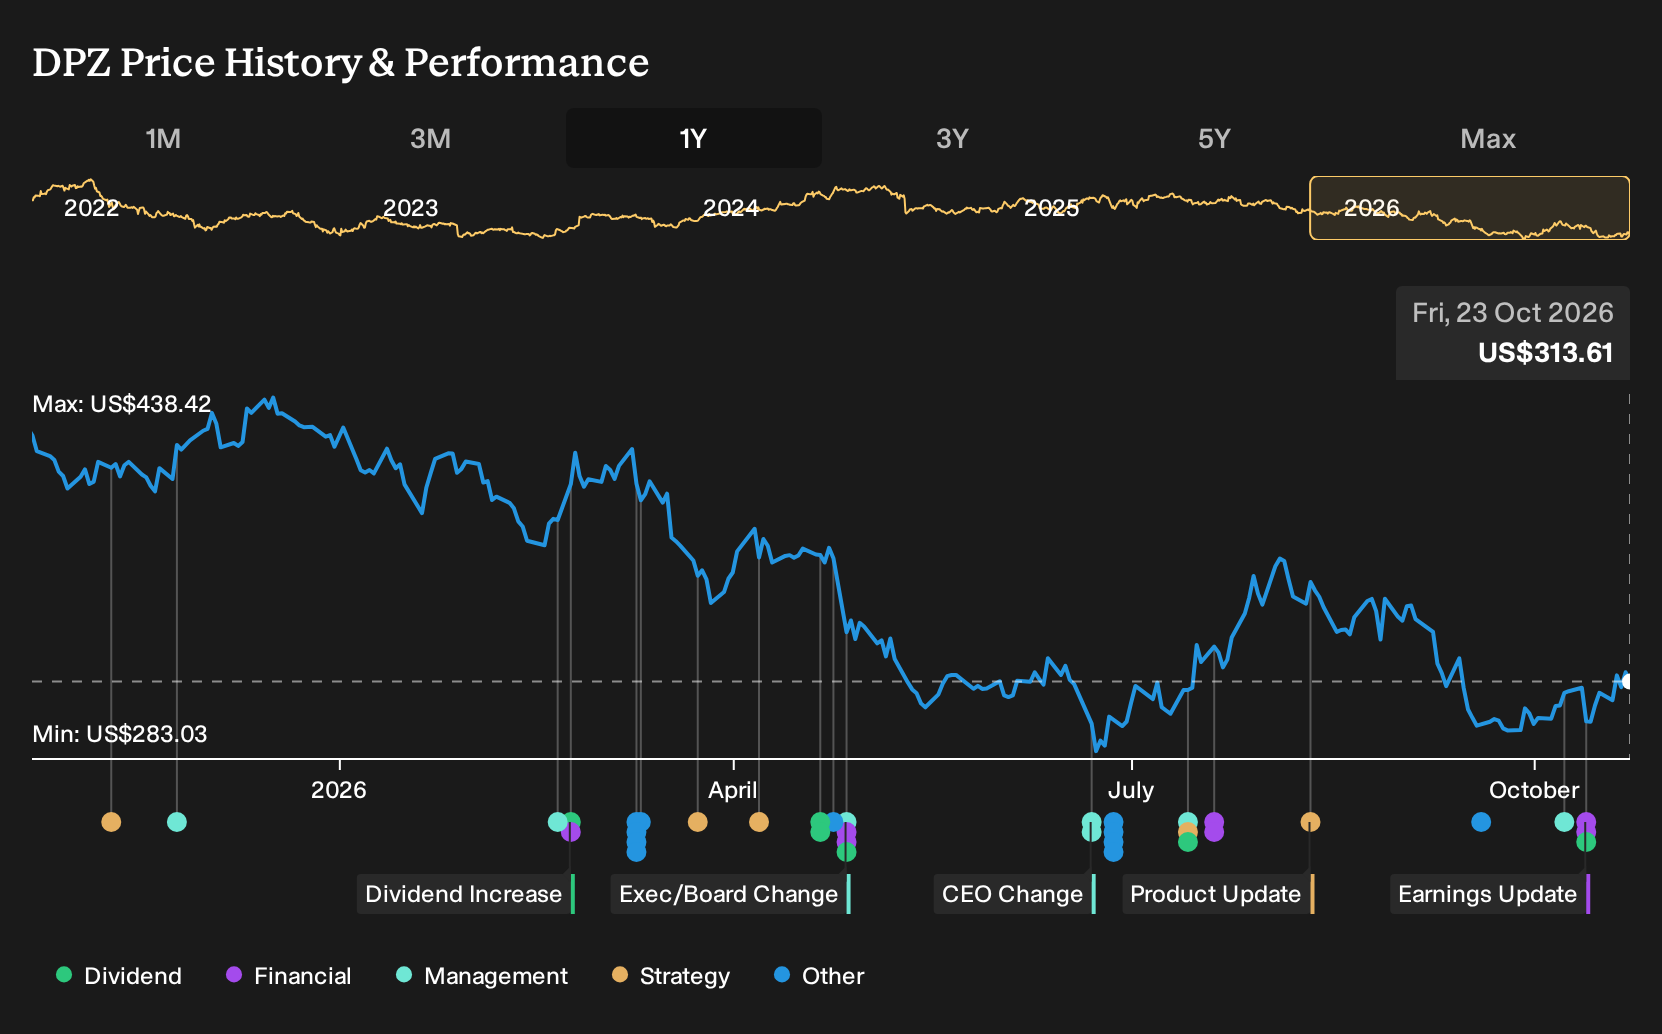
- Domino's Pizza reported third quarter 2026 results with revenue of US$1,185.6 million and net income of US$152.18 million, alongside a quarterly dividend of US$1.99 per share declared in October 2026.
- The nine month figures show revenue of US$3,530.62 million and net income of US$427.74 million, which gives investors more visibility into Domino's Pizza's current earnings power and cash returns via dividends and ongoing share repurchases.
- We will now look at how Domino's Pizza's investment narrative aligns with this earnings performance, with particular attention to the higher quarterly earnings.
Scan how Domino's Pizza's latest earnings, dividend, and buyback context compares with other consumer-focused stocks by reviewing our curated list of 27 high quality undervalued stocks.
Domino's Pizza Investment Narrative Recap
To own Domino's Pizza, you really need to believe its delivery focused, digitally heavy model can keep pulling in orders even as the broader pizza category looks sluggish. The latest quarter shows revenue of US$1,185.6 million and net income of US$152.18 million, which signals the model is still producing steady earnings. The short term catalyst remains execution on delivery partnerships and loyalty, with the key risk being that category wide traffic softness limits how much those tools can move the needle.
In the near term, the earnings trend matters less than whether Domino's Pizza can avoid heavy discounting in a price sensitive market. Flat or weaker demand would make it harder to grow ticket size without hurting value perception. Procurement gains also look less of a lever now, so investors need to watch whether future margin progress comes more from mix, digital efficiency, or store level cost control.
The most relevant announcement here is the detailed earnings release for the third quarter and nine month period to mid September 2026. It confirms revenue of US$3,530.62 million and net income of US$427.74 million for the nine months, with basic EPS from continuing operations at US$12.85. That provides a clearer picture of current earnings power as Domino's Pizza leans on delivery apps, loyalty and fortressing as key levers.
These figures matter for catalysts because they show how much room management has to keep funding technology, supply chain upgrades and international expansion while still returning cash through dividends and buybacks. The risk side is that global pizza quick service restaurant volumes look flat, and procurement productivity gains may ease, so execution on store economics and digital engagement needs to stay tight to support any future earnings progress.
Domino's Pizza's current analyst narrative points to revenue of US$5.6b and earnings of US$726.8 million by 2029, based on assumed annual top line growth of 3.4% and an earnings increase of about US$130 million from US$596.5 million today.
Discover why Domino's Pizza's fair value points to a potential 18% upside to its current price, a discount that could narrow quickly once sentiment shifts.
Exploring Other Perspectives
The most optimistic analysts framed Domino's Pizza around one big swing factor. They expected stronger carryout traction and product variety to help lift earnings toward about US$751.1 million on roughly US$5.7b of revenue by 2029. That is far above the broader consensus and was set before this earnings and dividend update, so you may want to compare how this fresh information could shift both the upbeat and more cautious stories you have just read.
Explore 4 other Domino's Pizza fair value estimates, including one that suggests as much as 36% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Domino's Pizza research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Domino's Pizza. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Domino's Pizza's overall financial health at a glance.
Looking for more investment ideas beyond Domino's Pizza?
If Domino's Pizza has helped sharpen your view on earnings quality and cash returns, you can apply the same perspective to a broader watchlist. The Simply Wall St Screener lets you quickly filter for different profiles so you can identify other candidates that fit your approach before you commit fresh capital.
- For investors who want growth potential without ignoring balance sheet strength, scan our 21 high quality undiscovered gems that match those filters in a single view.
- If income and resilience matter most to you, focus on dependable payers by reviewing a curated set of 5 dividend fortresses that meet a higher yield bar.
- When capital preservation is a top priority, narrow your search to businesses that score well on stability by using the 30 resilient stocks with low risk scores as a starting universe.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com