


- Catena AB is investing SEK 131 million in a 5,800 m² logistics facility in Pirkkala, Finland, fully leased for seven years to a Finnish industrial automation tenant, with construction scheduled from autumn 2026 to autumn 2027.
- The Pirkkala project becomes Catena’s 20th Finnish property and is structured as a corporate transaction, adding EPC B rated, energy efficient space that is estimated to generate an annual operating surplus of about SEK 9.7 million.
- The focus now turns to how Catena's investment narrative could be influenced by this fully let, energy efficient Pirkkala development.
Catena Investment Narrative Recap
To own Catena, you need to believe in long term demand for logistics real estate in Sweden and nearby markets, supported by tenant appetite for well located, energy efficient assets. The short term focus stays on execution of the development pipeline and keeping occupancy solid while funding costs and client caution remain live pressure points.
The Pirkkala facility is fully leased on a seven year contract, so it looks helpful for cash flow visibility rather than a major near term swing factor. The bigger risk still sits with funding growth when capital is selective, together with any pockets of regional oversupply and slower tenant decision making.
The Finland project fits neatly alongside earlier expansion moves into Denmark, where Catena has also secured a logistics location described as attractive. Both directions point to the same operational theme. Management is trying to build scale across key Nordic corridors instead of relying only on Swedish hubs.
For you as a shareholder, the link to potential catalysts is straightforward. Completion of projects like Pirkkala and the previously announced Danish development adds lettable area that can support rental income, while geographic diversification may help if certain Swedish regions struggle with vacancies or pricing pressure from competitors such as Blackstone.
What The Current Analyst Playbook Implies For Catena
Catena's narrative projects SEK 3.8 billion revenue and SEK 1.9 billion earnings by 2029. This aligns with analysts who are modeling 10.0% yearly revenue growth and an earnings decline of SEK 0.2 billion from SEK 2.1 billion today.
Discover why Catena's fair value indicates a 30% potential upside to its current price that may be temporary.
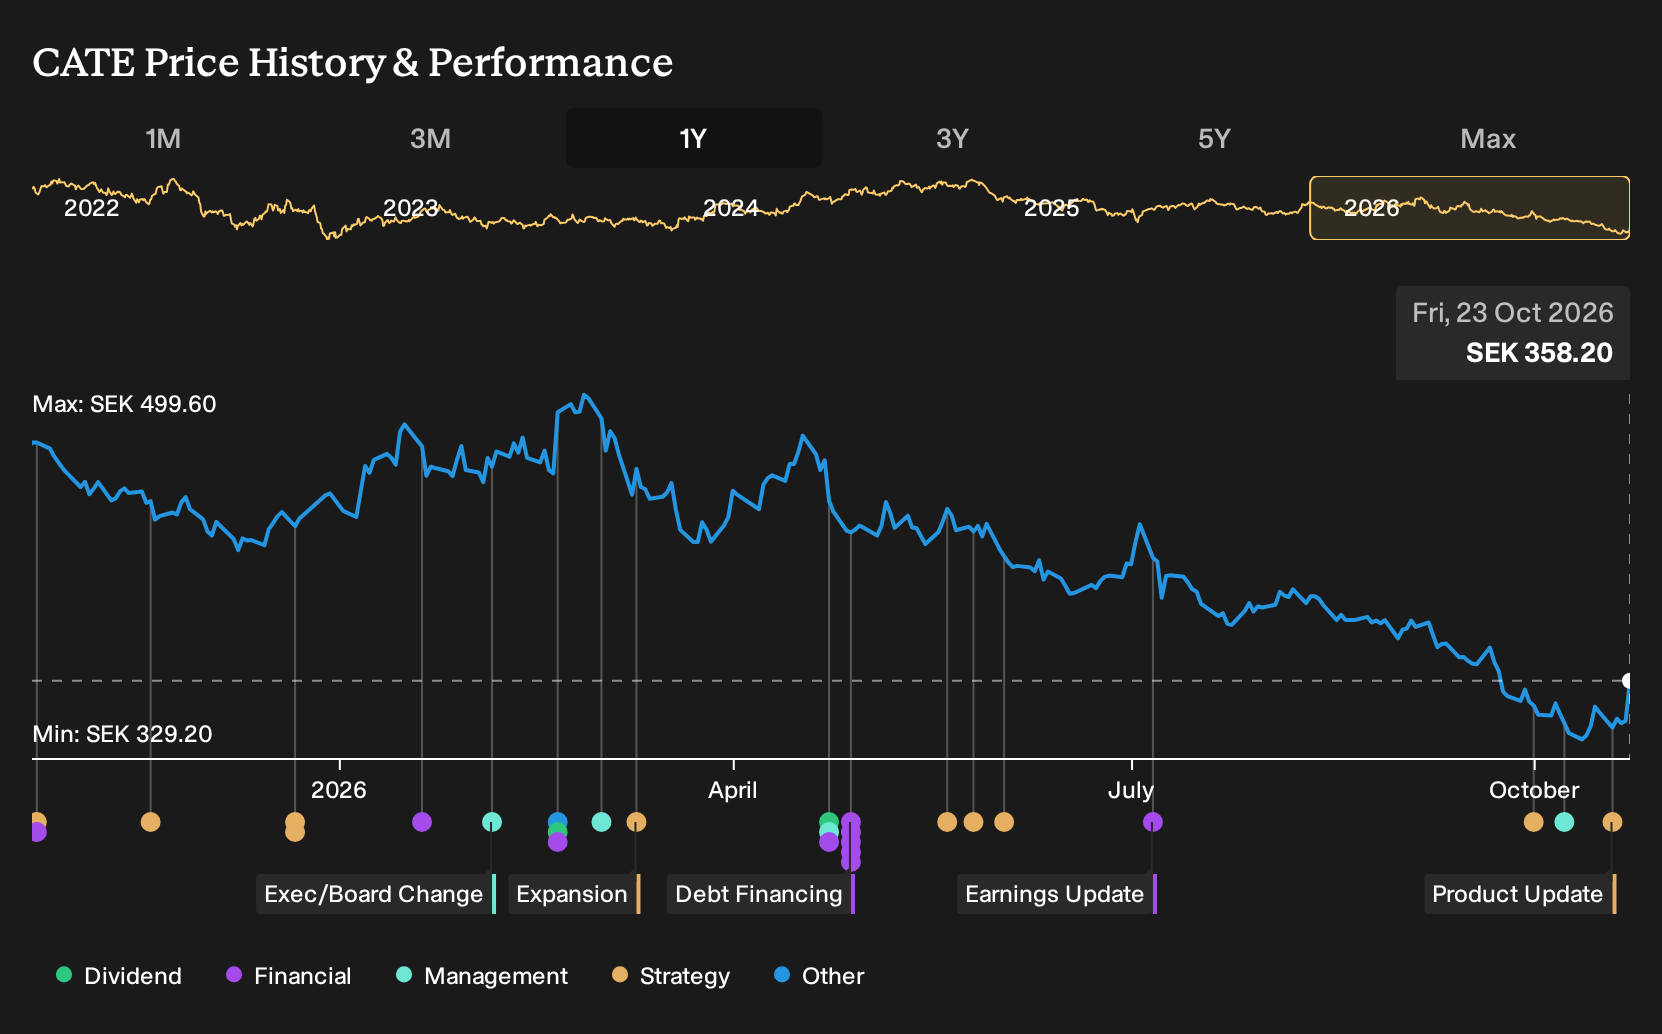
Exploring Other Perspectives
One alternate angle is pure earnings risk. The most pessimistic analysts were pencilling in SEK 3.6b revenue and SEK 1.5b earnings by 2029, well below consensus, because they worry Catena might struggle to keep newer Nordic assets fully used. This Pirkkala project could nudge those views, so it is worth exploring both narratives before deciding.
Explore another Catena fair value estimate, including one that suggests as much as 40% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Catena research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Catena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Catena's overall financial health at a glance.
Looking For More Investment Ideas Beyond Catena?
Once you have a view on Catena, it can help to widen the lens and compare it with other businesses that share some of the qualities you care about, whether that is value, resilience, or balance sheet strength.
- If you are hunting for potential value opportunities with quality fundamentals, start with our hand picked 192 high quality undervalued stocks and see which companies fit that profile.
- For investors who care most about resilient business models and steadier risk profiles, the 221 resilient stocks with low risk scores can surface stocks that match that preference.
- If you want to focus on financial strength and funding flexibility, use the list of solid balance sheet and fundamentals (204 results) as a shortcut to companies with sturdier balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com