


Cmb.Tech (ENXTBR:CMBT) has just booked an estimated gain of about US$59.6 million from selling its 2011-built Suezmax Stella tanker, a fourth quarter 2026 transaction that directly affects reported profit.
The Suezmax Stella sale lands at a moment when Cmb.Tech shares have already been on a strong run, with the 1-day share price return of 3.11% and 7-day share price return of 5.34% adding to a 90-day share price return of 19.62% and a year-to-date share price return of 105.71%, while the 1-year total shareholder return of 120.64% indicates that recent momentum has come on top of sizeable gains for longer term holders.
Scan how Cmb.Tech compares with other shipping and energy plays by reviewing the curated 615 high quality undiscovered gems moving on fresh corporate actions and asset sales.
Cmb.Tech now trades with a big asset gain in the bag and a sharp share price move already logged. Is most of the rerating behind it, or does valuation still argue there is meaningful upside ahead?
Most Popular Cmb.Tech Narrative: 5% Overvalued
Analysts following Cmb.Tech see fair value at about €15.85 using a 7.18% discount rate, compared with the recent close at €16.58. As a result, the narrative leans slightly cautious on upside from here.
Post-merger scale from Golden Zhoushan, funded CapEx and active refinancing of higher cost bridges and leases create room for lower average funding costs, higher operating leverage and greater capacity for dividends or buybacks once the balance sheet converges toward the targeted 50 percent loan to value, enhancing earnings per share.
See why 8 investors see Cmb.Tech as 5% overvalued.
Result: Fair Value of €15.85 (OVERVALUED)
Still, this story can change quickly if spot-exposed tanker and dry bulk markets soften or if the ammonia and hydrogen rollout takes longer than analysts assume.
Find out about the key risks to this Cmb.Tech narrative.
Another View: What Cmb.Tech’s P/E Is Signalling
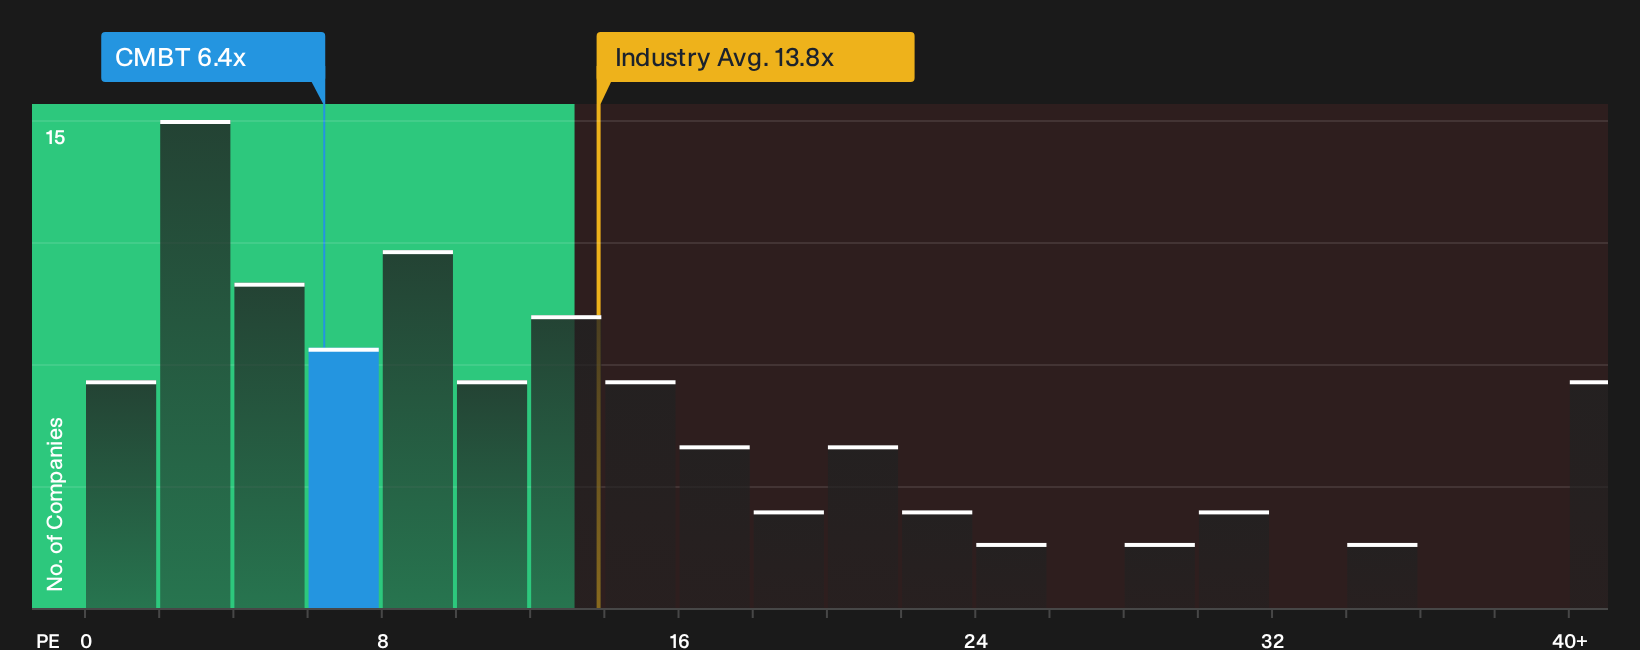
Analyst targets suggest Cmb.Tech is slightly ahead of fair value at €16.58 versus €15.85. The market is telling a different story on earnings, however. A P/E of 6.4x compares with 17.5x for peers and 13.8x for the wider European Oil and Gas group, which points to a steep valuation gap. That kind of discount can flag either mispricing or real concern around forecasts. Which side of that trade do you think is closer to the truth?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far, right, with Cmb.Tech looking optically cheap on P/E but flagged as slightly overvalued on fair value. Act quickly by stress testing the bullish and cautious angles for yourself, starting with the 2 key rewards and 3 important warning signs.
Looking for more Cmb.Tech investment ideas?
If you only stop at Cmb.Tech, you risk missing out on other opportunities that fit your goals even better, so put the broader market to work for you.
- Target potential upside with companies that combine quality fundamentals and attractive pricing by starting with the 192 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust finances through the list of solid balance sheet and fundamentals (204 results).
- Dial down overall risk by focusing on steady operators with fewer red flags using the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com