


Auckland International Airport (NZSE:AIA) has attracted fresh attention after reporting updated traffic statistics for September 2026, including passenger volumes, aircraft movements and freight weight across both its Auckland and Queenstown operations.
The recent traffic update follows a mixed year for Auckland International Airport’s investors, with the share price at NZ$8.39 and short term momentum improving on a 2.69% 7 day share price return. The 1 year total shareholder return of 4.26% and 3 year total shareholder return of 20.15% indicate steadier gains over a longer holding period.
Scan other airport and infrastructure plays showing similar traffic and earnings momentum using the curated list of solid balance sheet and fundamentals (204 results).
Auckland International Airport looks like a solid infrastructure play on current traffic and revenue trends, yet the share price near NZ$8.39 after a modest recent gain raises a sharper question. Is investors’ enthusiasm already reflected in the valuation, or not?
Most Popular Narrative: 35.3% Overvalued
Auckland International Airport’s most followed valuation storyline puts fair value at NZ$6.20 per share, well below the current NZ$8.39 price, which creates a clear tension between a prized asset and what investors are currently willing to pay.
WATCH, accumulate below ~NZ$5.75. The binding constraint is price, not durability, a top-decile monopoly moat, a fortress balance sheet and a competent jockey, let down for the buyer only by a ~22–24× EBITDAFI tag that compresses the owner's return to ~9–10% and erases the margin of safety.
See why 1 investors see Auckland International Airport as 35% overvalued.
Result: Fair Value of NZ$6.20 (OVERVALUED)
Still, this overvaluation story can crack if regulators cut allowed returns, or if the NZ$6.6b build runs over budget and forces more dilution.
Find out about the key risks to this Auckland International Airport narrative.
Another View On Auckland International Airport’s Value
While the leading narrative pegs Auckland International Airport at NZ$6.20 per share and labels the stock as overvalued, the SWS DCF model lands in a very different place. It puts future cash flow value at NZ$35.60 per share, implying the current NZ$8.39 price is trading at a steep discount. Which story do you think better reflects the risk and reward on offer?
Look into how the SWS DCF model arrives at its fair value.
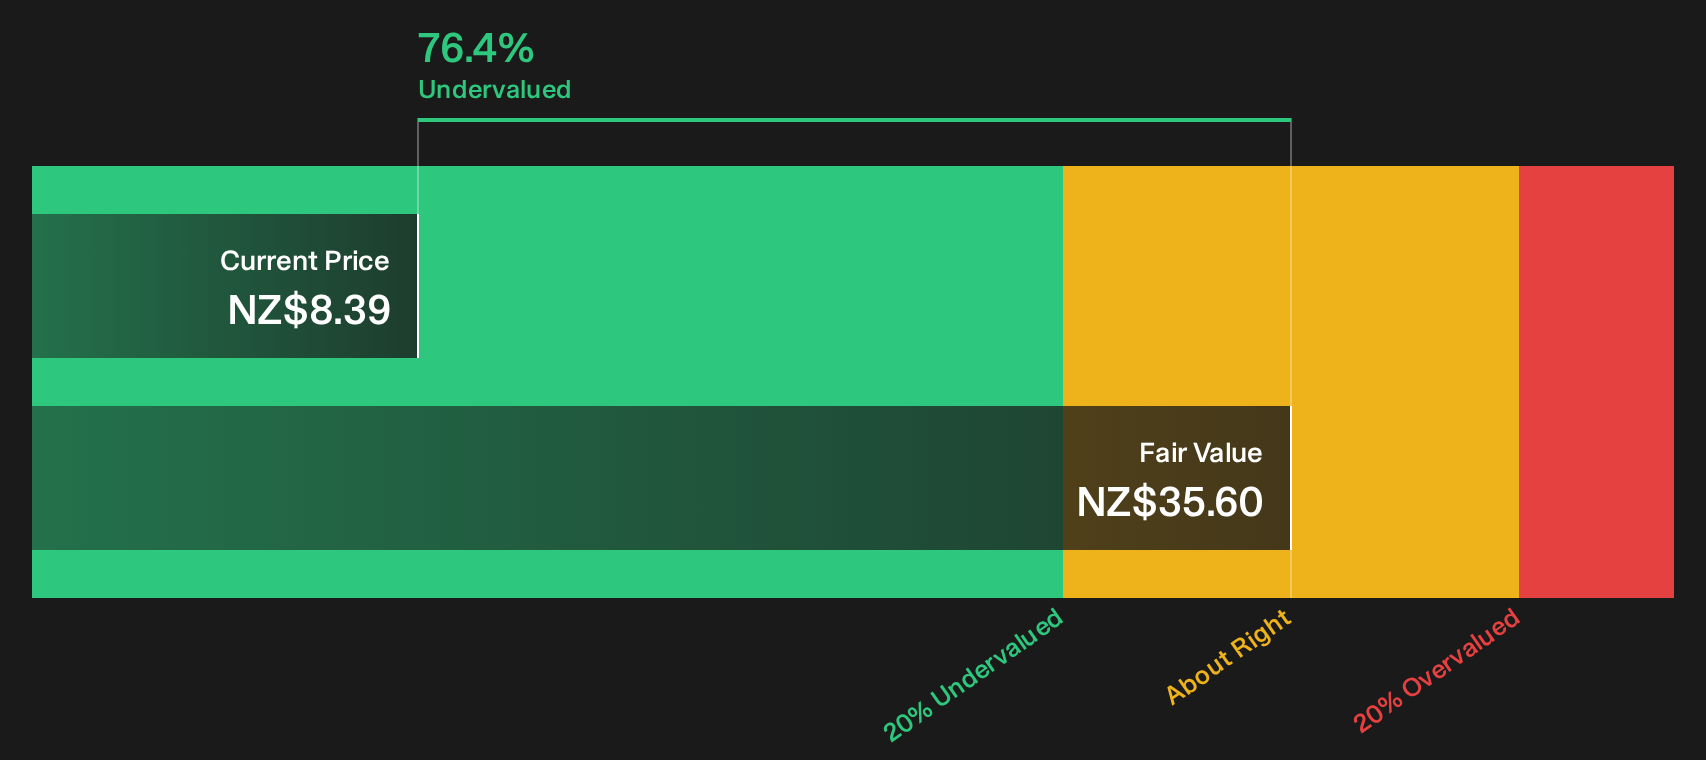
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Auckland International Airport for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of caution and optimism around Auckland International Airport leaves you on the fence, move quickly and pressure test the thesis against the numbers yourself. To see how those potential upsides stack up against the risks, take a closer look at the 2 key rewards.
Looking for more Auckland International Airport investment ideas?
If Auckland International Airport has your attention, do not stop here. Broaden your watchlist with other opportunities that could sharpen your overall portfolio mix.
- Explore companies with lower risk profiles through the 221 resilient stocks with low risk scores.
- Look for potential mispricings by using the 192 high quality undervalued stocks, which highlights companies that combine quality fundamentals with attractive entry points.
- Consider adding income-focused ideas to your watchlist by reviewing the 226 dividend fortresses, which focuses on yields of 5% or more.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com