


Rexford Industrial Realty came into this Q3 2026 earnings print with a mixed reputation. The story has been about high quality Southern California warehouses set against patchy profitability. Then the stock jumped 6.7% to US$38.71 on the first full trading day after results, which suggests expectations were tight.
The headline is not eye catching earnings per share. Investors focused on core Funds From Operations per share of US$0.60 and yet another raise to full year core FFO guidance. The real surprise was on the balance sheet, where lower net leverage and a clearer path on 2027 debt took center stage.
Love Rexford Industrial Realty's prime Southern California footprint but concerned about patchy profitability and leverage risks? Take a look at our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
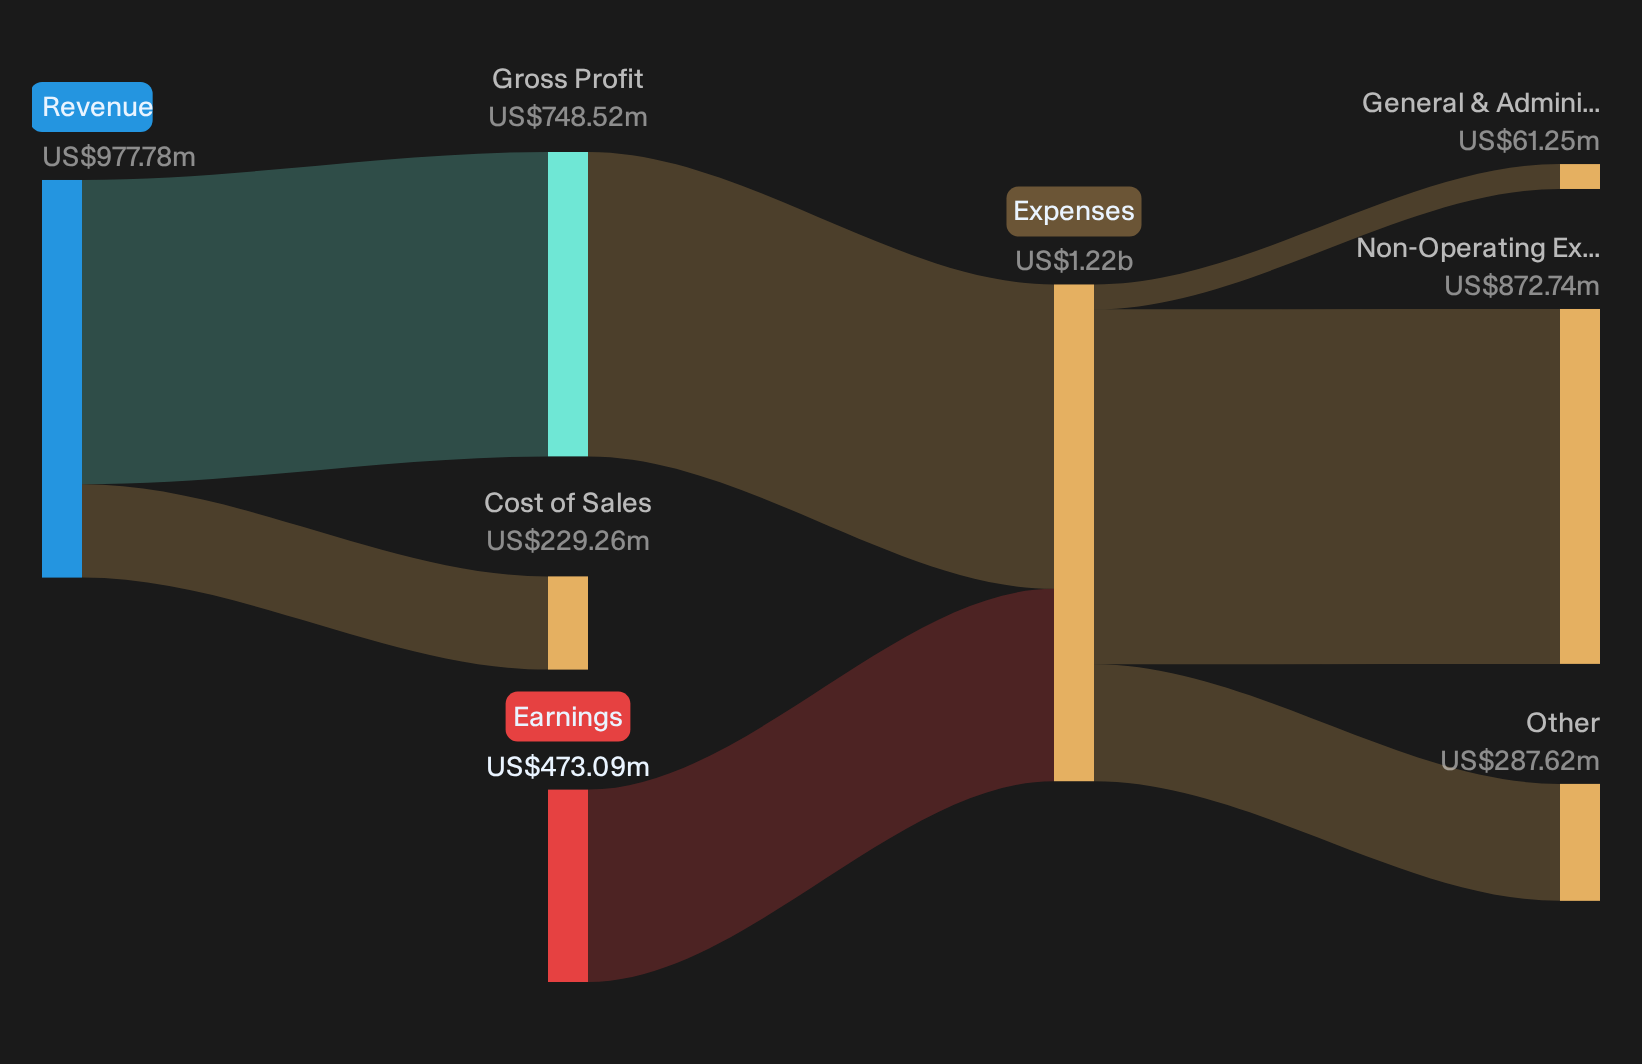
- Revenue (Q3 2026 vs. Q3 2025): US$239.1m vs. US$253.2m (declined 5.6%)
- Net Income (Q3 2026 vs. Q3 2025): US$14.6m profit vs. US$87.1m profit (down 83.2%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.07 per share vs. US$0.37 per share (fell 82.1%)
- Funds From Operations (FFO, Q3 2026 vs. Q3 2025): Not disclosed for Q3 2026 vs. US$440.5m in Q3 2025 (comparison not meaningful without the current figure)
Rexford raised core FFO and NOI guidance after reshaping its portfolio. Ask Charlie what made Rexford hike FFO guidance again.
Rexford Bull Case: Recycling And Repositioning Put To Work
Supporters argue that Rexford Industrial Realty can convert portfolio churn and infill projects into steadier cash flow and stronger per share earnings power.
"The key factor is that Rexford Industrial Realty successfully executes its pivot toward higher return repositioning and small bay infill product, while using asset sales to reduce debt and support per share earnings power."
The latest quarter lines up with that script. Rexford closed 1.5b of dispositions, repaid 425m of 2027 debt, and bought back about 10% of shares since Q2 2025. At the same time, 600,000 square feet of development and repositioning leasing is set to add more than US$14m of annualized NOI, and core FFO per share guidance has been raised for the third time.
Rexford Bear Case: Rent Pressure And Pipeline Execution Still Bite
Skeptics worry that rent resets and a large pipeline could erode the benefit of all that capital recycling if execution wobbles.
"Market rents across Rexford Industrial Realty's portfolio continue to face pressure, with cash re-leasing spreads at a decline of 11.3% in Q2 2026 and guidance now calling for full year 2026 cash re-leasing spreads in a decline of 10% to 15%, with similar mid-teens pressure expected in 2027 and 2028."
That concern is visible. Management still expects low to mid teens cash re leasing spread declines over the next couple of years as peak era leases reset. Q3 core FFO per share held flat year on year at US$0.60, with revenue and net income both down versus Q3 2025, which shows the pressure on earnings even as occupancy and guidance improve.
The price and this Narrative do not agree. → Uncover what this Narrative says Rexford Industrial Realty is actually worth.
Hunt For Mispriced Earnings Power
Rexford Industrial Realty just showed how a single quarter can reshape views of balance sheet risk and earnings quality. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 1 - 34% below our estimate - converts large AI infrastructure and multicloud database contracts into subscription-led, cash-focused cloud services.
- Company 2 - 20% below our estimate - captures hyperscale data center build demand through communications, infrastructure and industrial projects supported by a rising backlog.
- Company 3 - 45% below our estimate - integrates a recent bank acquisition to expand low cost deposits and fee income across a broader lending and wealth platform.
That is three of the list. See the full list of 27 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com