


HCA Healthcare (HCA) heads into its upcoming third quarter 2026 report with expectations for slightly lower earnings, modest revenue growth, and freshly revised EPS estimates that have put changing analyst sentiment under the spotlight.
Recent trading has been constructive for HCA Healthcare, with a 30 day share price return of 7.46% and a 90 day move of 22.72% helping offset a slight year to date decline of 0.29%. The latest close at $469.03 sits against a 1 year total shareholder return of 5.64% and a 3 year total shareholder return of 113.01%, which points to momentum built over a longer stretch rather than just the pre earnings run up.
Compare HCA Healthcare's setup with a curated group of peers by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results)
HCA Healthcare now trades slightly above the average analyst target, while internal models imply a far larger gap to estimated fair value. Which reference point deserves more weight as you price the recent run up?
Most Popular Narrative: 4% Overvalued
Against HCA Healthcare's last close at $469.03, the most followed narrative sets fair value at $452.29. This puts the stock modestly above that mark while still tying the thesis tightly to insured volume, capital spending and cost discipline.
Broad-based insured volume growth at HCA Healthcare, with 2Q26 same facility equivalent admissions for insured patients excluding exchanges up 3.2% year over year and total admissions and ER visits also rising, points to continued demand in its markets that can feed future revenue and EBITDA.
See why 35 investors see HCA Healthcare as 4% overvalued.
Result: Fair Value of $452.29 (OVERVALUED)
Still, the narrative around HCA Healthcare can be knocked off course if policy shifts hit Medicaid support harder than expected, or if weak outpatient surgery volumes linger longer than analysts model.
Find out about the key risks to this HCA Healthcare narrative.
Another View On HCA Healthcare's Value
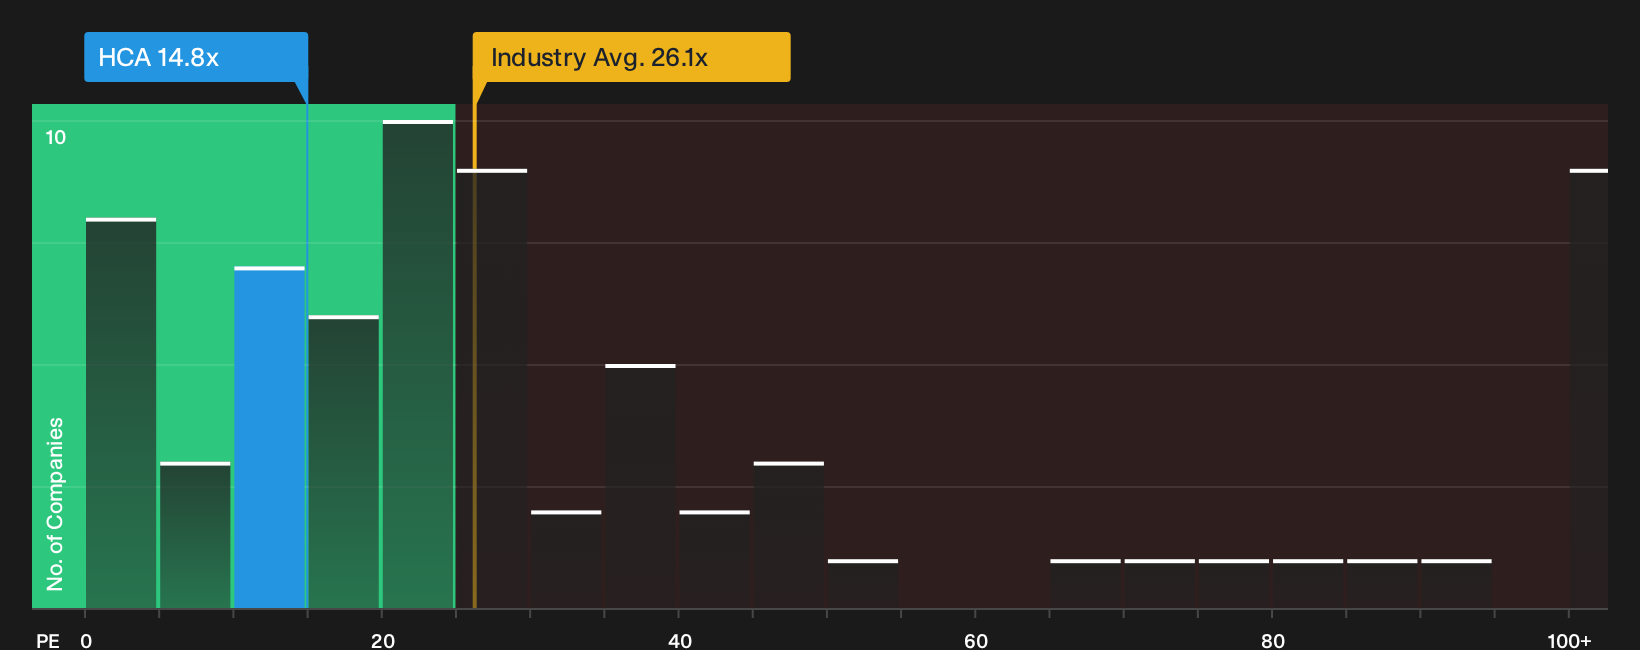
Analyst fair value at $452.29 points to HCA Healthcare as 4% overvalued, yet simple P/E work tells a different story. The stock trades at 14.8x earnings versus 16x for peers, 26.1x for the US Healthcare industry, and a fair ratio of 27.3x that the market could move toward. That gap frames either a valuation buffer or a signal that earnings quality and balance sheet risk are being priced in more harshly than for rivals, so which interpretation fits your thesis best.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around HCA Healthcare's current pricing only matter if you act on them rather than just watch from the sidelines, so pressure test the upside and downside for yourself by weighing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond HCA Healthcare?
If HCA Healthcare has sharpened your focus, do not stop here. Broadening your watchlist now can help you spot opportunities others overlook.
- Target potential mispricing and hunt for companies that look attractively valued on fundamentals with the 27 high quality undervalued stocks.
- Strengthen your income playbook by reviewing the 5 dividend fortresses that combine higher yields with a focus on resilience.
- Dial down portfolio stress by scanning the 30 resilient stocks with low risk scores that prioritise balance sheet strength and steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com