


UL Solutions (ULS) has been busy on three fronts: expanding its extended producer responsibility services, rolling out a new certification track for modular DC energy storage, and upgrading its HVACR testing hub in Texas.
All this activity around EPR services, energy storage certification and HVACR testing comes at a time when UL Solutions’ share price has been volatile, with a 30-day share price return of 12.33% following a year-to-date share price decline of 9.23% and a 1-year total shareholder return decline of 7.59%, indicating short-term momentum rebuilding after a weaker stretch.
Scan a curated set of testing, certification and energy transition plays that echo UL Solutions’ positioning by checking out 42 power grid technology and infrastructure stocks today.
After a sharp 30-day rebound, yet a weaker year-to-date and 1-year record, UL Solutions now sits in an awkward middle ground. Is most of the easy upside already used up, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 25% Undervalued
Against the last close of $73.44, the most followed narrative pegs UL Solutions at a fair value of about $98.23. This sets up a clear gap between market price and modeled worth that investors need to understand before leaning on the recent share price rebound.
The analysts have a consensus price target of $98.23 for UL Solutions based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $120.0, and the most bearish reporting a price target of just $79.0.
See why 5 investors see UL Solutions as 25% undervalued.
Result: Fair Value of $98.23 (UNDERVALUED)
Still, softer net income growth alongside higher expected tax pressures could challenge the UL Solutions earnings narrative and reveal how sensitive the P/E assumptions really are.
Find out about the key risks to this UL Solutions narrative.
Another View: UL Solutions Looks Expensive On Earnings
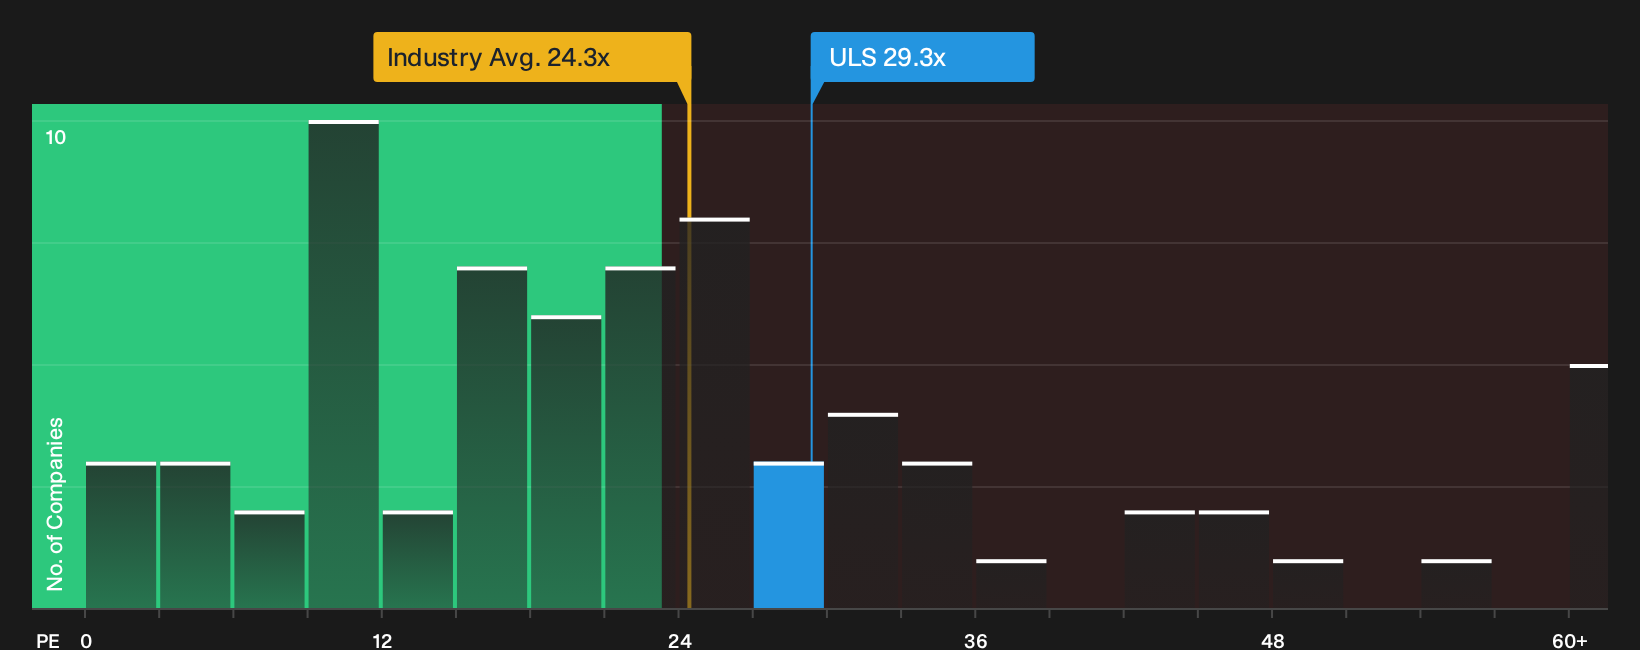
The analyst fair value story presents UL Solutions as about 25% undervalued at $98.23. The earnings multiple tells a very different story. ULS trades on a P/E of 29.3x, compared with 24.3x for the US Professional Services industry and 26.7x for peers, while the fair ratio is much lower at 16.1x.
That gap suggests investors are already paying a premium price for earnings that consensus expects to decline over the next three years, so the margin for error appears limited if the growth narrative weakens from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on UL Solutions so far. If you want to move quickly and judge the balance of risks and upside yourself, review the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond UL Solutions?
Do not stop at UL Solutions. Fresh opportunities sit just a few clicks away, and the next idea that fits your style could already be on the screen.
- Target resilient compounding by scanning companies with strong cash generation and appealing valuations using the 27 high quality undervalued stocks.
- Prioritize sleep-at-night holdings by focusing on businesses with stronger balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Look for potential emerging leaders ahead of wider attention by reviewing a curated pool of 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com