


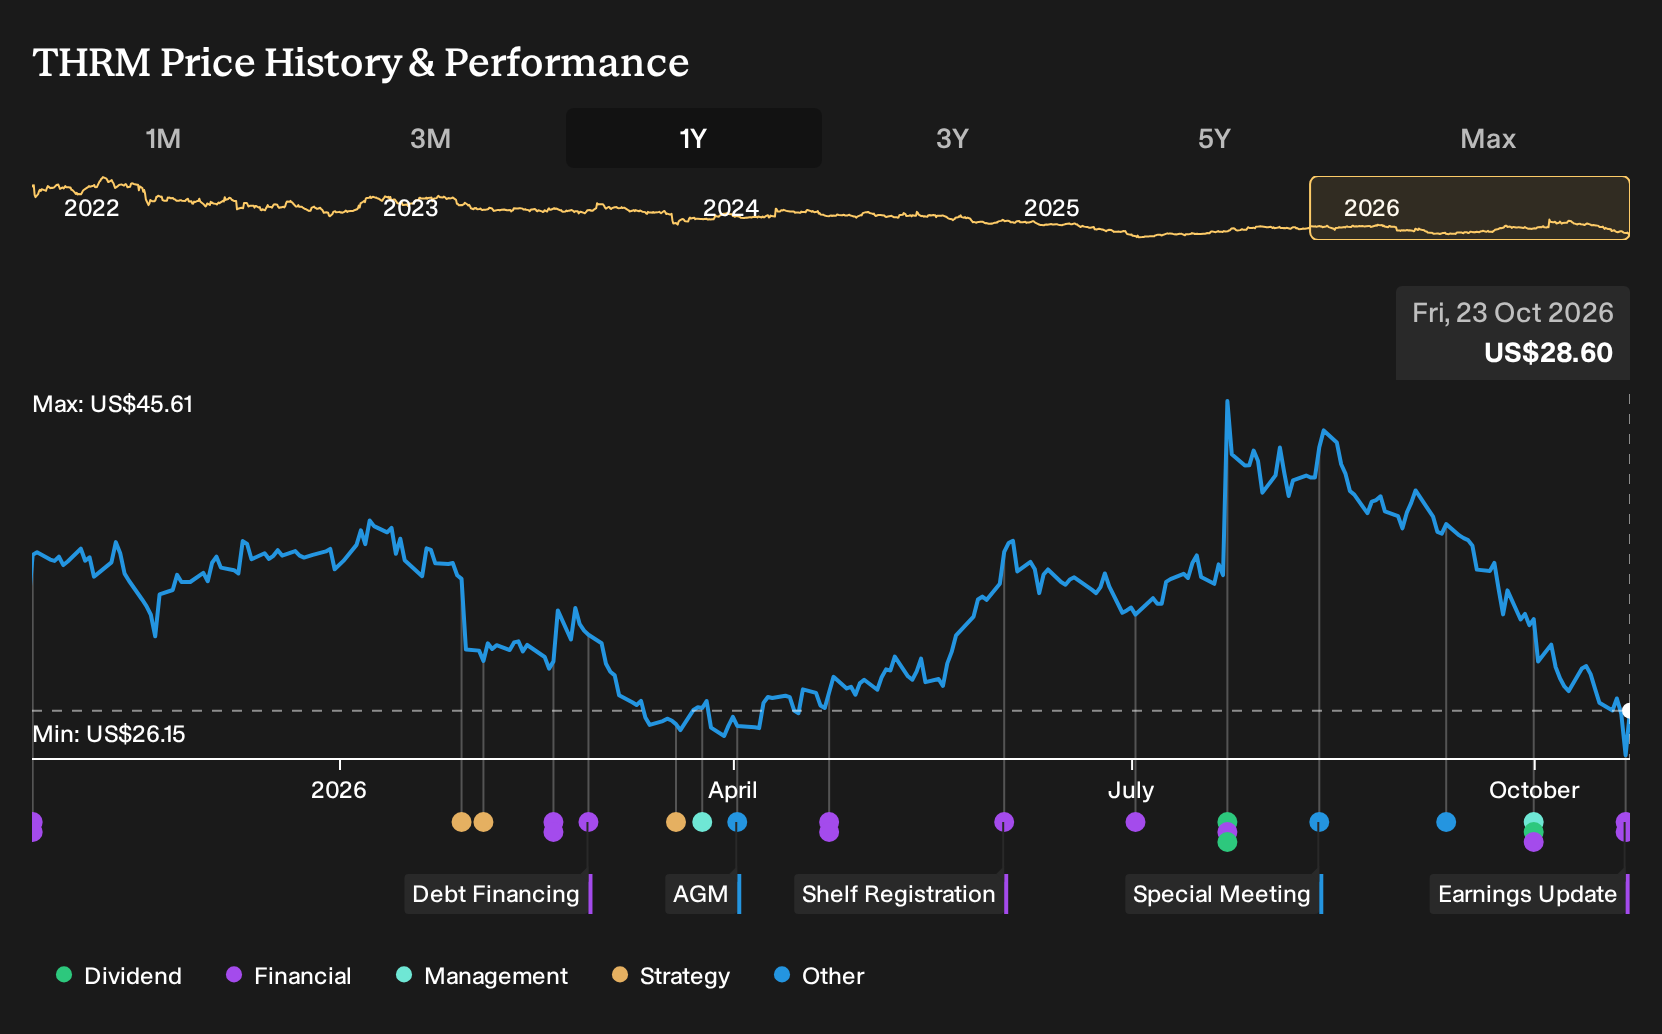
- Gentherm reported a third quarter 2026 net loss of US$2.59 million and adjusted EPS below analyst expectations, while lifting full year product revenue guidance to a range of US$1.825 billion to US$1.925 billion after completing the Modine Performance Technologies acquisition and a US$60 million share buyback.
- The combination of weaker quarterly profitability, higher full year revenue and EBITDA guidance, and a 6.34% share count reduction highlights Gentherm’s focus on both integrating its new assets and returning capital to shareholders despite near term cost pressures.
- We will look at how Gentherm’s investment narrative is shaped by higher 2026 revenue guidance tied to the Modine Performance Technologies deal.
Gentherm Investment Narrative Recap
To own Gentherm, you need to believe the thermal management platform can offset near term earnings pressure with broader exposure across automotive, commercial, home, office and medical end markets. The raised 2026 product revenue guidance tied to Modine Performance Technologies points investors toward integration quality and execution as the key short term swing factor.
The immediate risk sits in margins. Gentherm just reported a third quarter net loss of US$2.59 million, with lower profitability linked to inflation, logistics and mix, while integration and footprint costs also sit in the background. If these inputs continue to bite, the higher revenue run rate may not quickly translate into stronger EBITDA or cash generation.
The most relevant update for that thesis is the new full year 2026 product revenue outlook of US$1.825 billion to US$1.925 billion, which now includes Modine Performance Technologies. This puts hard numbers around the larger platform investors have been underwriting and frames how quickly the combined group can scale into commercial vehicles, power generation and data center related flow control.
For you as a shareholder, the key question is whether Gentherm converts that higher top line base into healthier margins once integration work and inflation pressures settle. The risk is that ongoing material, labor and logistics costs or slower traction in newer home, office and medical channels keep profit contribution muted, which would leave the story more about size than about quality of earnings.
What Gentherm’s Long Term Forecasts Assume
Gentherm's narrative projects US$2.4b revenue and US$191.1 million earnings by 2029. Analysts are building this on 15.6% yearly revenue growth and an earnings increase of about US$164.5 million from US$26.6 million today.
Uncover why Gentherm's fair value indicates a 68% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist in the Gentherm story comes from views on operating efficiency. The most optimistic analysts were already modeling roughly US$3.5b of 2029 revenue and US$269.1 million of earnings before this buyback and guidance update. You can compare those more upbeat assumptions with today’s margin pressure and decide which narrative feels closer to your own.
Explore 3 other Gentherm fair value estimates, including one that suggests as much as 191% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gentherm research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Gentherm. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gentherm's overall financial health at a glance.
Looking for more Gentherm like investment ideas?
If Gentherm has sharpened your view on how guidance, earnings pressure and capital returns shape a thesis, it can help to line that thinking up against a wider watchlist built from other opportunities across the market.
- If resilience matters most to you, start with companies that pair steadier fundamentals with muted risk scores through the 30 resilient stocks with low risk scores.
- If reliable balance sheets are your anchor, filter for businesses with cleaner leverage and stronger fundamentals using the list of solid balance sheet and fundamentals (25 results).
- If you prefer situations that fly under the radar, scan a curated pool of lesser known opportunities with solid footing via the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com