


Eisai (TSE:4523) is back in focus after the company flagged a series of oncology data presentations for LENVIMA based regimens at the ESMO Congress 2026, following recent FDA approval of WELIREG plus LENVIMA in advanced RCC.
Eisai’s oncology update lands after a period of improving sentiment, with the share price up 9.02% over the past 90 days and 6.04% year to date, while the 1 year total shareholder return of 16.31% contrasts with weaker 3 and 5 year outcomes. This suggests momentum has recently been rebuilding from a longer term slump.
Scan Eisai’s oncology momentum against a curated peer group by checking out 10 healthcare AI stocks, which could be lining up their own catalyst rich pipelines in cancer and drug discovery.
The oncology story around Eisai has clearly caught the market’s eye after recent gains. The harder question now is whether that improving sentiment already more than reflects what this business is worth.
Most Popular Narrative: 11% Overvalued
Eisai last closed at ¥5,076 against a widely followed fair value narrative of ¥4,582, so the oncology and neurology excitement currently prices in a premium. That gap increases the importance of whether the pipeline and recurring earnings shift play out as expected.
The refocusing of oncology around biomarker guided and minimal residual disease approaches, including in licensed assets such as taletrectinib and serplulimab alongside the existing LENVIMA franchise that management guides to a ¥250b level of revenue by FY2028, sets up a transition toward more targeted cancer care that can sustain segment revenue and support overall earnings.
See why 4 investors see Eisai as 11% overvalued.
Result: Fair Value of ¥4,582 (OVERVALUED)
Still, pressure on drug pricing and higher biologics production costs could quickly challenge the Eisai narrative if they erode margins faster than expected.
Find out about the key risks to this Eisai narrative.
Another View: Eisai Through The Cash Flow Lens
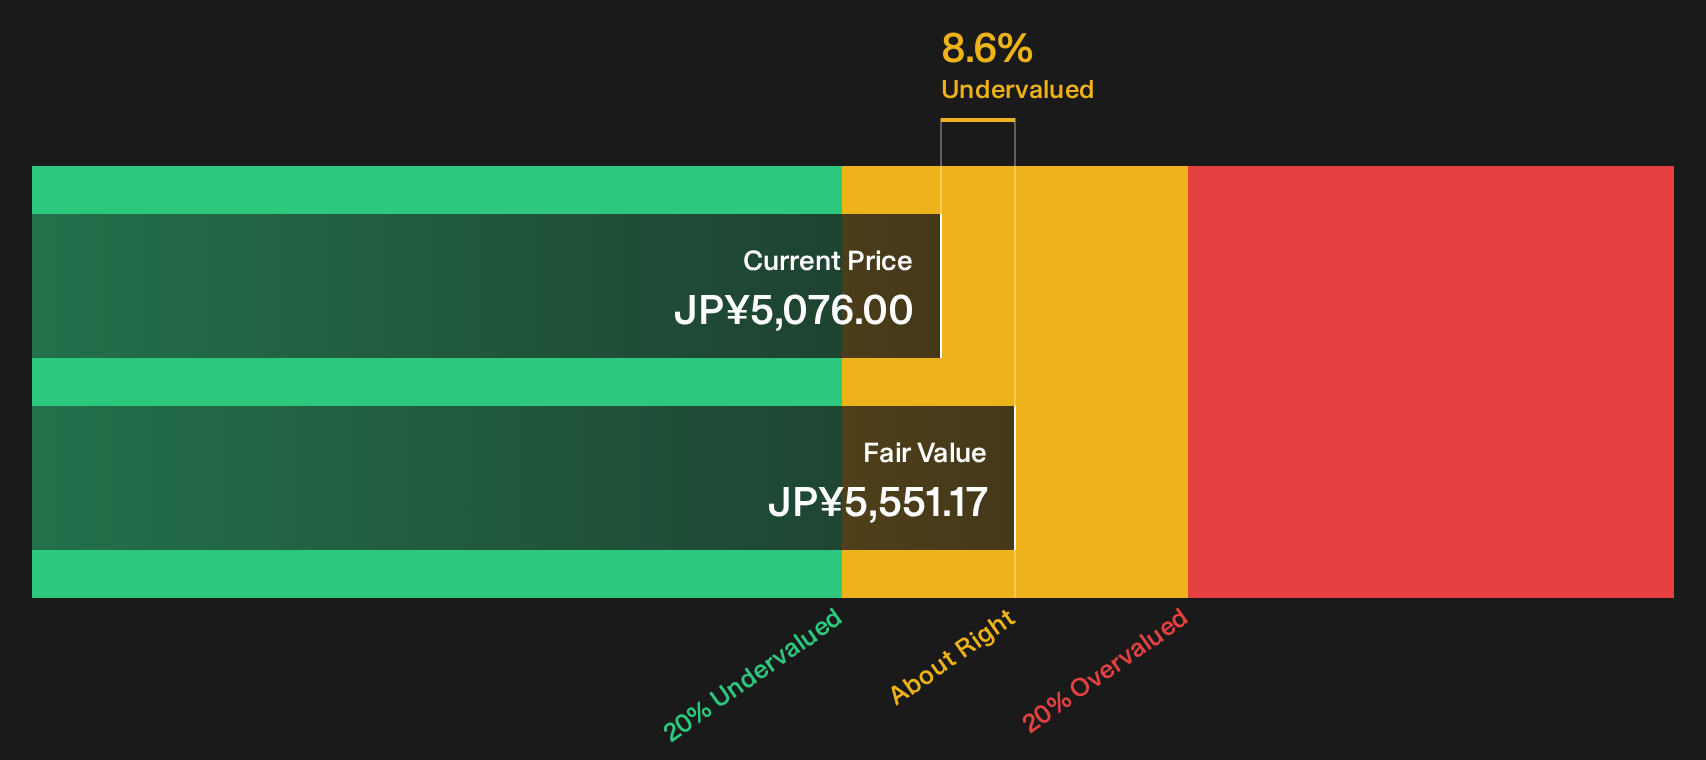
The popular story has Eisai trading 11% above a ¥4,582 fair value, yet the SWS DCF model points in a different direction. On that framework, the shares at ¥5,076 sit about 8.6% below an estimated future cash flow value of ¥5,551. That clash raises a simple question: which set of assumptions do you trust more, the narrative fair value or the cash flow math?
For a closer look at how that cash flow estimate comes together, take a moment to Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eisai for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Eisai’s story so far. If you want a view that is truly your own, move quickly through the data and weigh both sides using 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Eisai?
If Eisai has you thinking differently about risk, return, and timing, back that curiosity with action and review fresh opportunities that fit your playbook.
- Target resilient compounding potential by reviewing companies highlighted in 14 high quality undervalued stocks that pair quality fundamentals with prices below their assessed worth.
- Prioritise capital protection and smoother rides by using the 22 resilient stocks with low risk scores to focus on businesses with more measured risk profiles.
- Hunt for lesser known potential by checking the 72 high quality undiscovered gems and see which underfollowed stocks match your criteria before the crowd arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com