


J&T Global Express (SEHK:1519) just reported Q3 2026 operating metrics that gave investors fresh data to work with. Global parcel volume reached 9.58 b, up 24.8% year over year, with average daily volume above 100 million for a second straight quarter.
The trading action has been choppy. J&T Global Express has a 1 day share price return of 2.35% and a 30 day share price return of 1.88%, yet the share price return year to date is down 14.27% and the 1 year total shareholder return is down 14.35%, pointing to weak longer term momentum despite the strong Q3 operating update.
Scan how J&T Global Express compares with other logistics and transportation players by reviewing our curated list of list of solid balance sheet and fundamentals (204 results)
J&T Global Express now has strong parcel momentum but a share price that has lagged. Does that mix still tilt the risk reward in favour of buyers once you crunch the current valuation?
Most Popular Narrative: 34% Undervalued
On the most followed valuation narrative, J&T Global Express screens as undervalued, with a fair value of HK$13.48 against the latest close near HK$8.93. That gap rests on specific assumptions about parcel growth, profitability and how investors might price the business in the future under an 8.57% discount rate.
The rapid expansion of e-commerce, especially in Southeast Asia and emerging markets like Latin America, continues to drive strong parcel volume growth for J&T (for example, 58% volume growth in Southeast Asia and 22% in new markets in H1 2025), supporting both top-line revenue growth and reinforcing a long-term structural demand tailwind.
See why 3 investors see J&T Global Express as 34% undervalued.
Result: Fair Value of HK$13.48 (UNDERVALUED)
Still, the bullish J&T Global Express narrative runs into real friction if China price competition keeps crushing local EBIT or if heavy capex in new markets drags on cash generation.
Find out about the key risks to this J&T Global Express narrative.
Another View: J&T Global Express Looks Expensive On Earnings
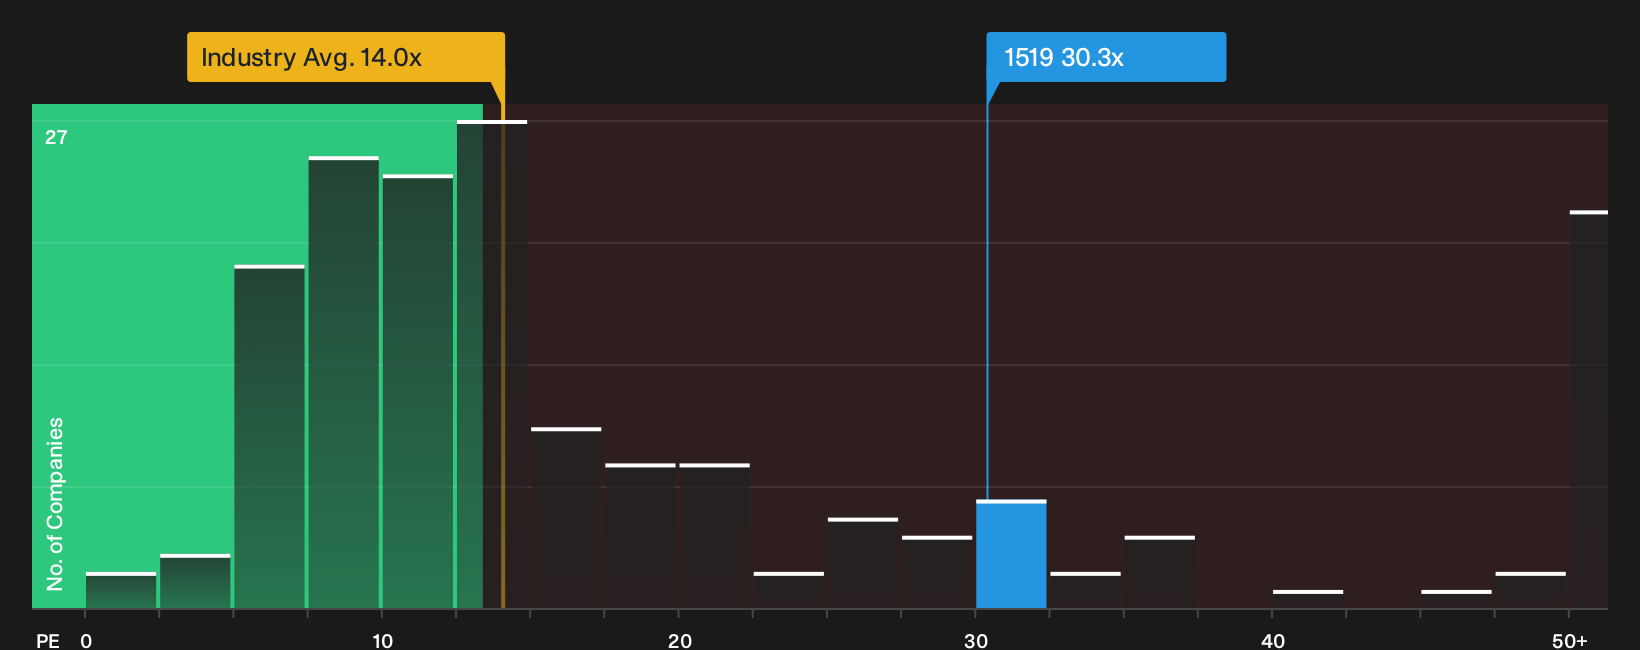
The DCF style fair value for J&T Global Express points to upside, but the P/E picture is far less generous. The stock trades on about 30.3x earnings, while peers in the Asian logistics group sit near 14.1x and a fair ratio is 16.9x. That is a wide premium. How comfortable are you paying that much for each dollar of profit?
Before leaning too hard on the earnings multiple, it can help to see how it fits into a fuller valuation breakdown, including cash flow and balance sheet signals, in our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these often split opinion on J&T Global Express, so move quickly through the data and stress test the bullish and bearish arguments yourself. To see both sides clearly, weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond J&T Global Express?
If J&T Global Express has you rethinking your watchlist, do not stop here. The right watchlist often starts with one idea and expands fast.
- Target potential mispricing by scanning companies that score as 192 high quality undervalued stocks before attention catches up and choices narrow.
- Strengthen portfolio resilience by reviewing a curated 221 resilient stocks with low risk scores that can help anchor returns when volatility picks up.
- Get early to quieter opportunities through a 615 high quality undiscovered gems that surfaces quality businesses before they become crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com