


Akamai Technologies (AKAM) is back in the spotlight after announcing a new wave of enterprise adoption for its cloud computing platform, centered on AI workloads, GPU infrastructure, and international expansion.
Akamai Technologies has seen mixed momentum, with the share price up 2.63% over the last day and 6.51% over the past week, yet down 21.03% across the last month and 18.93% over 90 days. At the same time, the 1-year total shareholder return sits at 24.62%, while longer term 3-year and 5-year total shareholder returns remain weak. This suggests that recent enthusiasm around cloud and AI wins is colliding with lingering investor caution about the longer track record.
Spot opportunities that align with the same AI and cloud momentum as Akamai Technologies by scanning our hand-picked 55 AI infrastructure stocks, which is shaping tomorrow's compute backbone.Akamai Technologies now trades at a sizeable discount to both analyst targets and intrinsic value estimates after that sharp pullback. Is the market correctly pricing in risk, or has caution swung too far?
Most Popular Narrative: 41% Undervalued
Akamai Technologies closed at $93.53 against a widely followed fair value estimate of $158.87, so the current pullback sits against a narrative that treats the recent AI and cloud contracts as materially underappreciated in the price.
Active capital deployment toward cloud infrastructure growth, including an expected 2026 CapEx level of about 40% of revenue and roughly US$5.5b of planned Anthropic related CapEx supported by zero coupon convertible debt financing and new power sourcing arrangements, is intended to build a 95 to 105 megawatt AI infrastructure portfolio. Management expects this portfolio to deliver about US$22m in annual revenue per megawatt and support future cash gross margins in the mid 60s to mid 70s range.
See why 36 investors see Akamai Technologies as 41% undervalued.
Result: Fair Value of $158.87 (UNDERVALUED)
Still, Akamai Technologies carries real execution risk if the capital heavy Anthropic buildout underdelivers, or if legacy delivery revenue erodes faster than security and cloud can replace it.
Find out about the key risks to this Akamai Technologies narrative.
Another View: What Akamai Technologies’ P/E Is Telling You
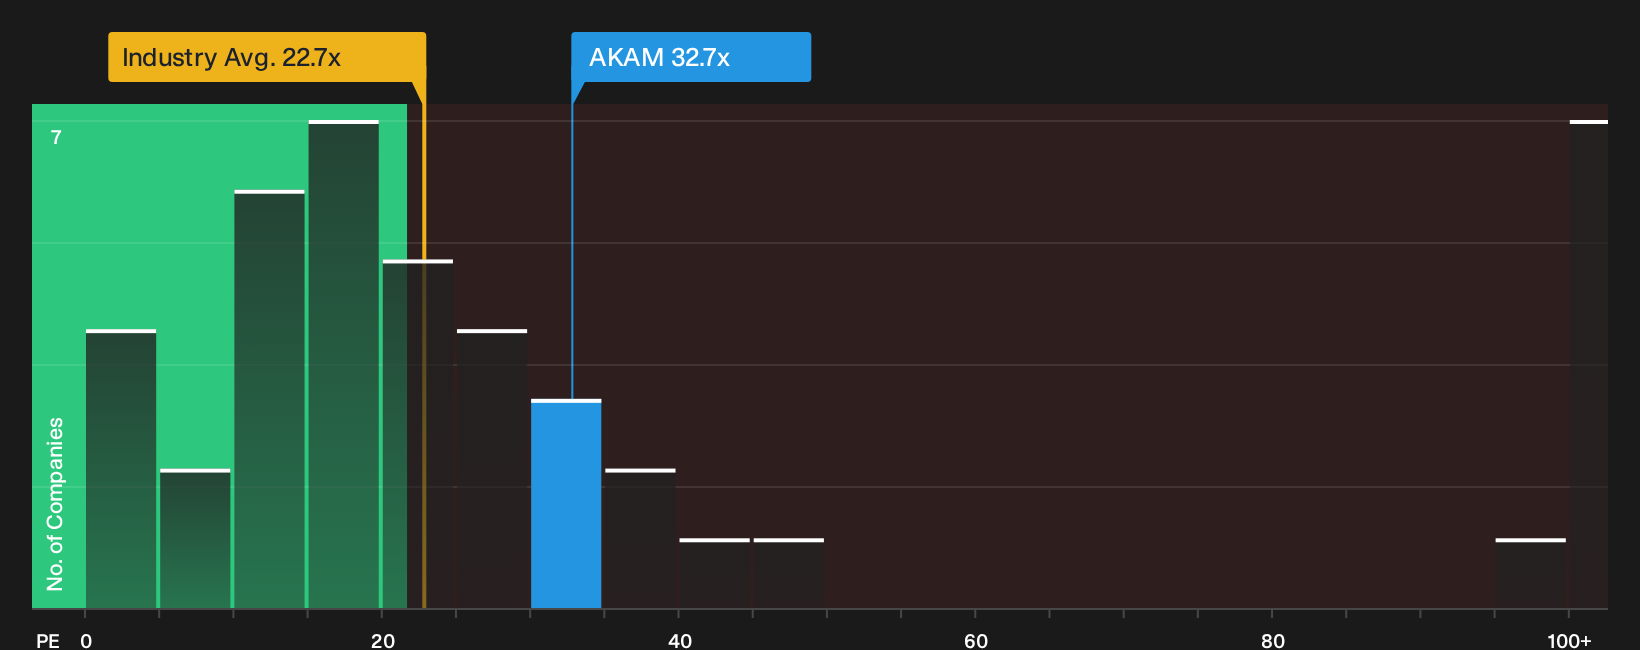
A second lens tells a different story. Akamai Technologies trades on a 32.7x P/E, which is higher than both the US IT group at 22.7x and its peer average of 25.6x, yet still below a fair ratio of 35.7x. Is the stock richly priced or simply catching up to where the model thinks it could move?
Investors who prefer valuation tools built around earnings multiples rather than detailed cash flow models may want to pressure test this gap using our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Akamai Technologies so far, right? If you want to move past the headlines and weigh the trade off between caution and optimism yourself, start with the full picture of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Akamai Technologies?
If you stop your research with Akamai Technologies, you risk missing other opportunities that fit your style, your risk comfort, and your return goals.
- Target cash flow strength by reviewing companies that pass our balance sheet and fundamentals checks in the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricings with the 27 high quality undervalued stocks that focuses on financially healthy businesses trading below their assessed worth.
- Prioritise resilience by scanning the 30 resilient stocks with low risk scores that highlights companies with lower risk scores across key financial indicators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com