


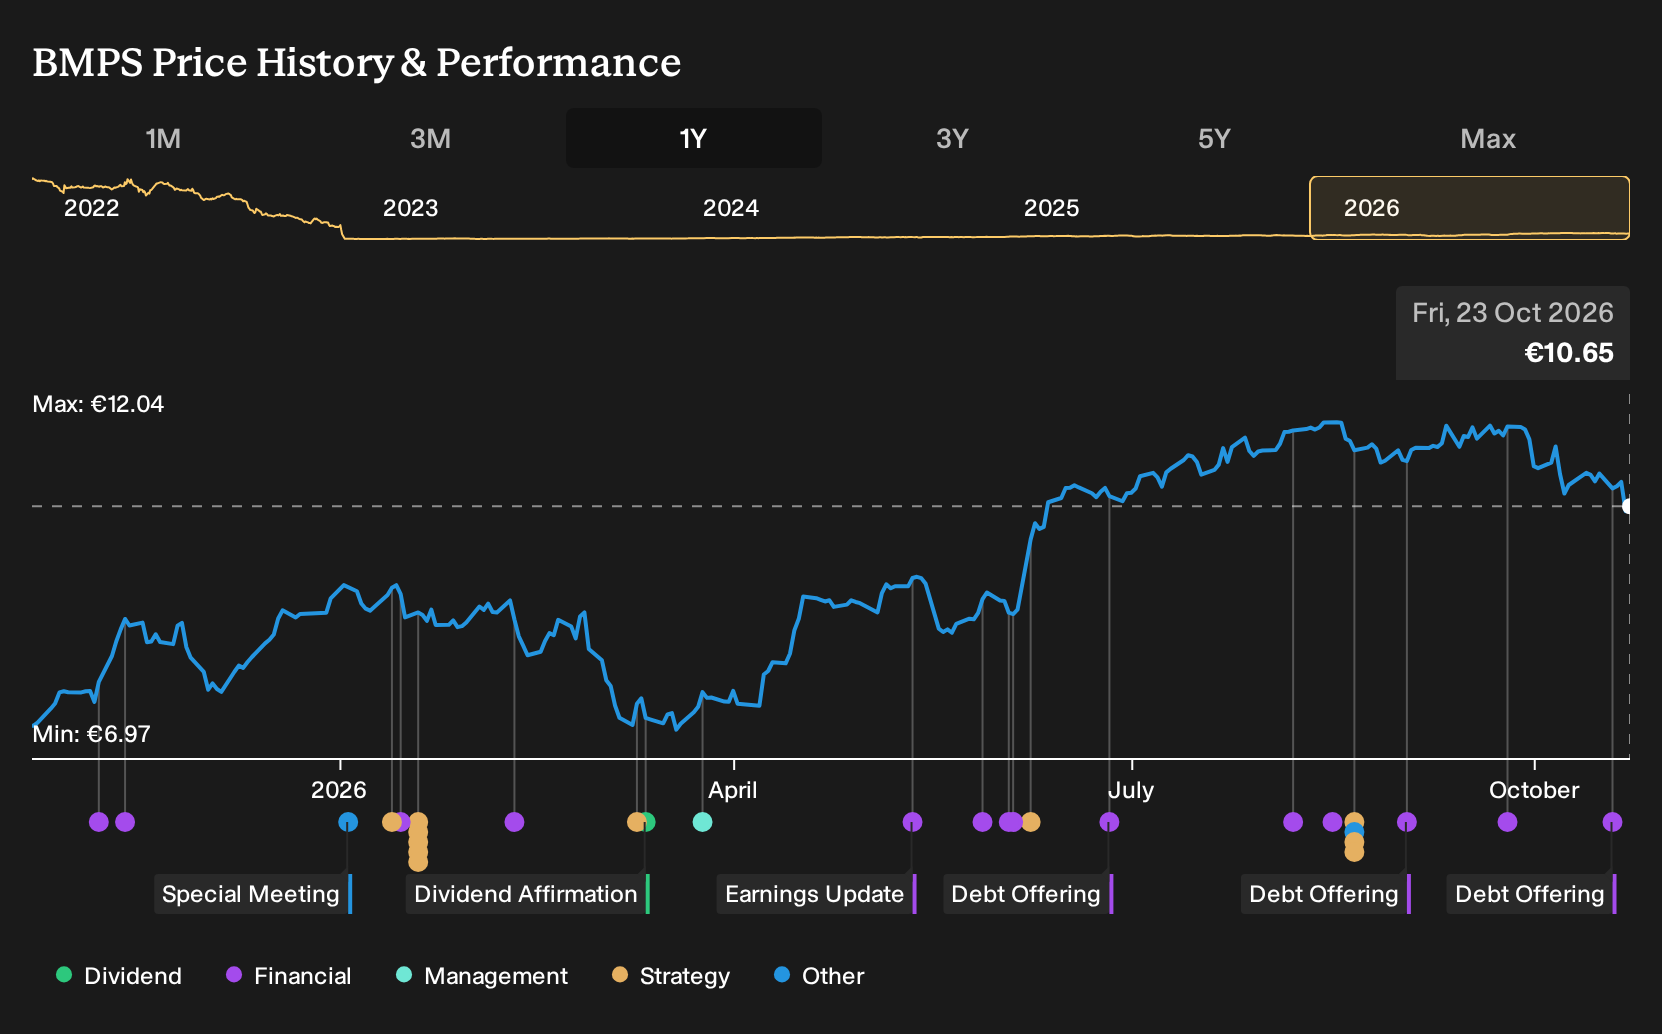
- Banca Monte dei Paschi di Siena has completed a €597.948 million fixed income offering of 3.750% covered mortgage notes due October 21, 2030, priced at 99.658% of the €600 million principal.
- The secured, guaranteed covered bond structure suggests investors have focused closely on collateral quality and legal protections rather than taking unsecured bank risk.
- We will now assess how this sizeable secured bond issue fits into Banca Monte dei Paschi di Siena's broader investment narrative around funding and capital.
Scan how Banca Monte dei Paschi di Siena’s covered bond move compares by reviewing a handpicked list of solid balance sheet and fundamentals (204 results) across the banking and financial sector.
Banca Monte dei Paschi di Siena Investment Narrative Recap
To own Banca Monte dei Paschi di Siena, you effectively need to believe the bank can turn solid recent earnings and strong capital into durable profitability while managing credit quality and integration risk. The new €597.948 million covered bond looks more like routine funding than a turning point, so it does not materially change the main short term drivers.
The near term upside still leans on delivering Mediobanca synergies, increasing the share of revenue from fees, and keeping costs in check as rates evolve. The key risk relates to execution on the broader consolidation plan and existing bad loan levels, as well as any strain from a dividend that is not fully covered by earnings forecasts.
Among recent developments, the focus on acquisitions such as Mediobanca, Banco BPM and Banca Generali is most relevant to this covered bond. The secured funding helps demonstrate market access; however, the real operational story for Banca Monte dei Paschi di Siena remains whether these deals, if completed as planned, can support fee based growth and cost efficiencies.
The stated goal for the enlarged group to improve return on tangible equity and move the cost or income ratio toward 36% sets a clear execution bar. In that context, this mortgage covered bond appears to be infrastructure that supports balance sheet resilience. At the same time, investors are likely to watch more closely how non performing loans, integration milestones and any update on the public exchange offers evolve.
How The Covered Bond Sits Against Banca Monte dei Paschi di Siena’s Forecasts
Analysts frame Banca Monte dei Paschi di Siena against a fairly punchy growth script, with revenue projected to rise by 20.7% a year over the next three years while profit margins are expected to compress from 52.3% to 32.1%. That mix points to a bigger business generating more absolute profit, yet doing so with less earnings power on each euro of income, which matters for how much cushion there is if funding costs or credit losses bite.
The covered mortgage notes just issued plug into that backdrop as one more tool to fund a balance sheet analysts already expect to expand meaningfully. With earnings today at about €2.9b and consensus pointing to €3.2b by 2029, the story investors are weighing is whether a secured funding stack, plus planned mergers and fee growth, can support higher absolute profit even as per unit returns face pressure.
Banca Monte dei Paschi di Siena's narrative projects €9.9b revenue and €3.2b earnings by 2029. This requires 20.7% yearly revenue growth and about €0.3b earnings increase from €2.9b today.
Those forecasts also assume the share count climbs by 7.0% per year for three years, so each slice of the company owned by existing shareholders gradually shrinks unless holdings are increased. Analysts look for earnings per share of €0.99 around October 2029, which reflects both the higher total profit and that extra dilution, and sets the bar for what this enlarged banking group needs to earn to justify the forecasts.
On valuation, the consensus picture is tight. The average analyst price target sits at €11.77 against a current share price around €11.00, a gap of 6.5% that suggests the market is already pricing in much of the planned earnings trajectory and capital story. To line up with that view, investors would effectively be assuming that by 2029 the bank reaches €9.9b of revenue, generates €3.2b of earnings and trades at a P/E of 19.0x, above both its current multiple of 11.4x and the IT Banks sector level of 11.8x referenced in the report.
That higher implied P/E ties the whole narrative together. The forecast 19.0x multiple requires confidence that Banca Monte dei Paschi di Siena can convert its fee growth plans, merger synergies and tighter cost or income ratio ambitions into quality earnings that deserve a richer price tag than the sector. If those building blocks, including secured funding such as the new covered bond, do not play out as consensus expects, the justification for that premium would weaken and the story investors are being asked to buy into would need to be revisited.
Discover how Banca Monte dei Paschi di Siena's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One optimistic twist in the alternate view is capital use. Some of the most bullish analysts were already pencilling in about €10.1b of revenue and €3.6b of earnings by 2029 for Banca Monte dei Paschi di Siena, before this €597.948m covered bond. You can judge whether this extra secured funding nudges those forecasts higher or lower.
Explore 4 other Banca Monte dei Paschi di Siena fair value estimates, including one that suggests potential upside of as much as 17% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Banca Monte dei Paschi di Siena research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banca Monte dei Paschi di Siena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banca Monte dei Paschi di Siena's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banca Monte dei Paschi di Siena?
If you want to stress test your view on Banca Monte dei Paschi di Siena, it helps to compare it with other companies that fit different risk, income, and quality profiles. The Simply Wall St Screener lets you do that quickly by filtering for traits that match how you like to invest.
- If capital preservation is high on your list, start with a basket of companies that our filters flag as relatively resilient by reviewing a 221 resilient stocks with low risk scores that may suit more cautious investors.
- Income focused readers can scan a curated 226 dividend fortresses that aim to combine higher yields with businesses that pass a basic financial health check.
- For those hunting for mispriced opportunities, compare your thesis on Banca Monte dei Paschi di Siena with a wider 192 high quality undervalued stocks that currently screen as both financially solid and potentially underappreciated by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com